China's copper market is entering the traditional September-October peak consumption season, though prices have been sharply fluctuating recently. With the macro headwind now easing and feedstock and spot supply tight, copper prices have solid support, and the key question becomes whether peak-season performance in China's major copper end-use sectors will lift downstream fabricators' output, sales and refined copper demand enough to keep prices supported. According to Mysteel's survey, performance is diverging across sectors, as real estate, home appliances and hardware industries will remain weak, while the power grid, new energy, AI and energy storage are taking over as growth drivers, though not fast enough to fully close the gap left by fading traditional drivers.
Prices stuck between financial and commodity fundamentals
September opened with heightened volatility in copper prices. Early in the month, expectations that the U.S. might impose tariffs on refined copper triggered stockpiling and pulled global visible inventories toward North America, driving SHFE copper steadily higher; the 2610 contract peaked at Yuan 112,330/tonne, closing in on this year's high of Yuan 114,590/tonne. The rally then reversed after market sources suggest the White House had not yet made a final decision on refined copper tariffs, as officials have been weighing on the short-term negative impact of higher tariffs on manufacturing costs, which rapidly unwound the tariff premium that had built up. On September 15, the SHFE 2610 contract briefly fell to a three-week low of Yuan 106,650/tonne. On September 16 (early September 17 Beijing time), the Federal Reserve raised rates by 25bp, lifting the federal funds target range to 3.75%–4.00%, its first hike since July 2023. The U.S. dollar index climbed back above 100 and gold fell, yet copper closed higher. The divergence highlights the competing influence of copper's financial and commodity fundamentals.
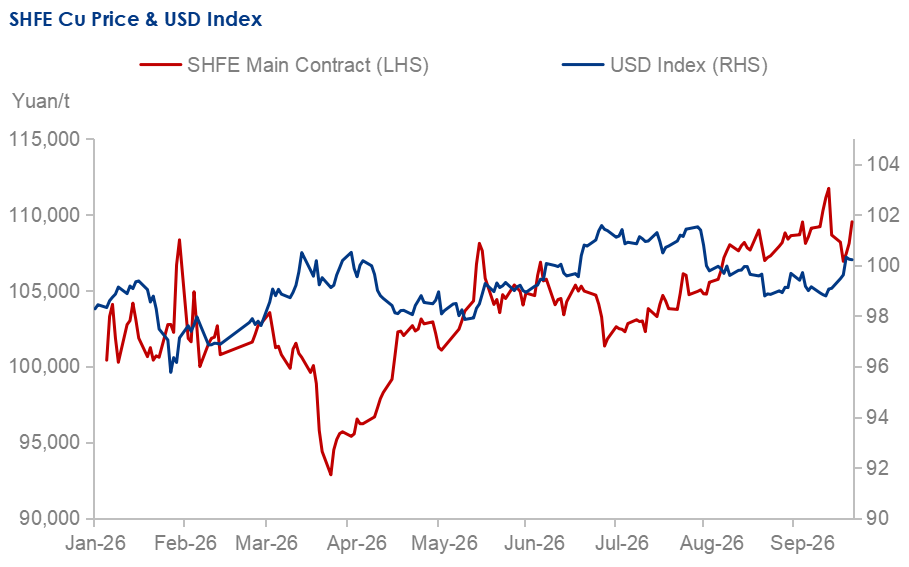
Source: SHFE, Fed, Mysteel
Power grid to remain the most reliable source of growth
Power grid investment is currently the most reliable pillar of copper demand, but its short-term pace has been uneven. In January–July, China's power grid investment reached Yuan 333.9 billion, up just 0.72% year on year. In July alone, investment fell by 56.53% month on month and 22.75% year on year, and August is unlikely to show much improvement. The pullback is largely seasonal, a rush of project launches at the end of H1 pulled forward some progress, while July and August are the critical period for guaranteeing summer power supply, when grid operators shift their focus from new construction to keeping supply stable. Hot and rainy weather also disrupted work. High copper prices, meanwhile, have sharpened bargaining over tenders and deliveries, indirectly slowing investment completion. Mysteel's survey of 19 cable manufacturers (combined annual copper use of about 1.5055 million tonnes) shows August refined copper consumption of 96,800 tonnes, down by 5,100 tonnes, or 4.99%, from July and 10.65% year on year.
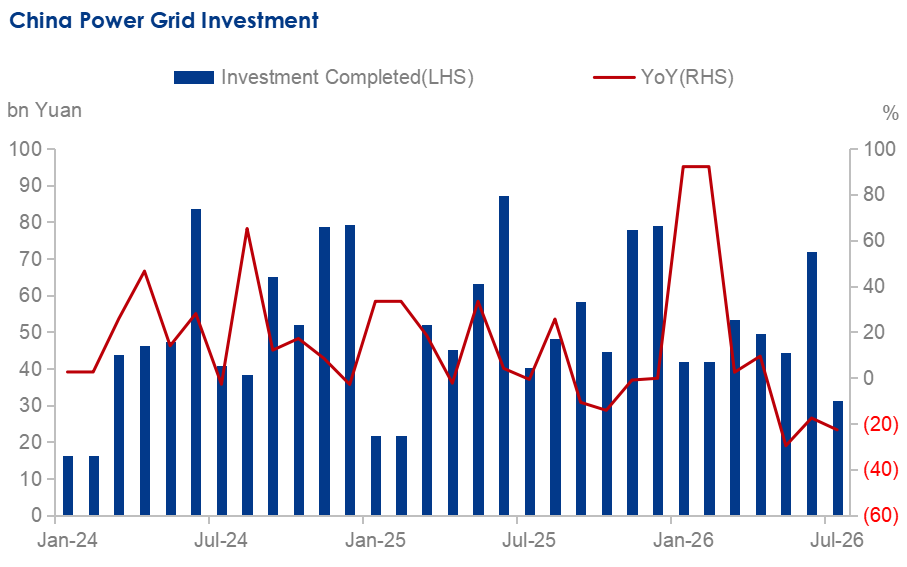
Source: NEA, Mysteel
For September and October, power grid investment will likely become a relatively certain support for copper demand. Underlying demand is stable, following the usual deployment cycle, the fourth batch of State Grid transmission and substation projects should gradually translate into tendering and deliveries, and construction delayed by heat and supply-guarantee work should be made up, pointing to a modest improvement over the two months. Meanwhile, 2026 is also the opening year of the 15th Five-Year Plan, and the China Electricity Council's "China Power Industry Annual Development Report 2026"forecasts nationwide electricity consumption growth of 5%-6% for 2026. Moreover, a lower copper price in mid-September should also help boost orders. Mysteel's survey of refined copper rod producers (9.13 million tonnes of annual capacity, about 48% of the national total) put order books at 101,700 tonnes as of September 11, up roughly 13,000 tonnes from the same period in August.
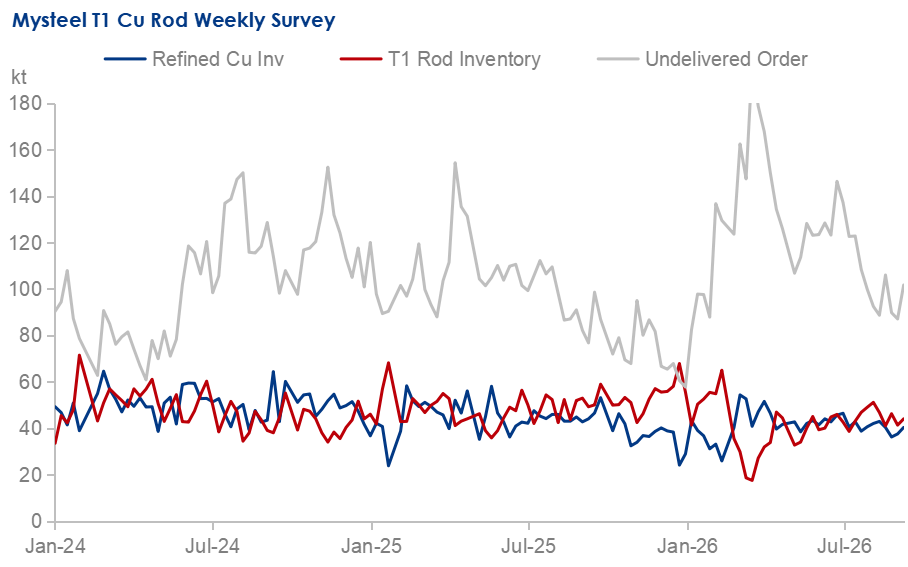
Source: Mysteel
It should be noted that copper price volatility continues to weigh on the pace of downstream raw material procurement and pricing. Wait-and-see sentiment on the tender side will amplify the seesaw effect between copper price volatility and order releases. Overall, however, total copper demand from the power grid sector remains well supported, with demand likely to trend higher in September and October and through the fourth quarter.
Home appliance recovery to be limited
The home-appliance sector is showing early signs of a turning point. China Industry Online (ChinaIOL) data show that after several consecutive months of steep declines, October household air conditioner production schedules see growth, rising from 9.75 million units in September to 11.324 million in October. The rebound, however, reflects producers stocking ahead of the fourth-quarter promotional windows (Double 11 Shopping Festival and Black Friday exports) rather than a genuine pick-up in retail sales, and channel destocking is expected to make only short-lived progress. Support for downstream copper semis and refined copper consumption is therefore likely to stay limited.
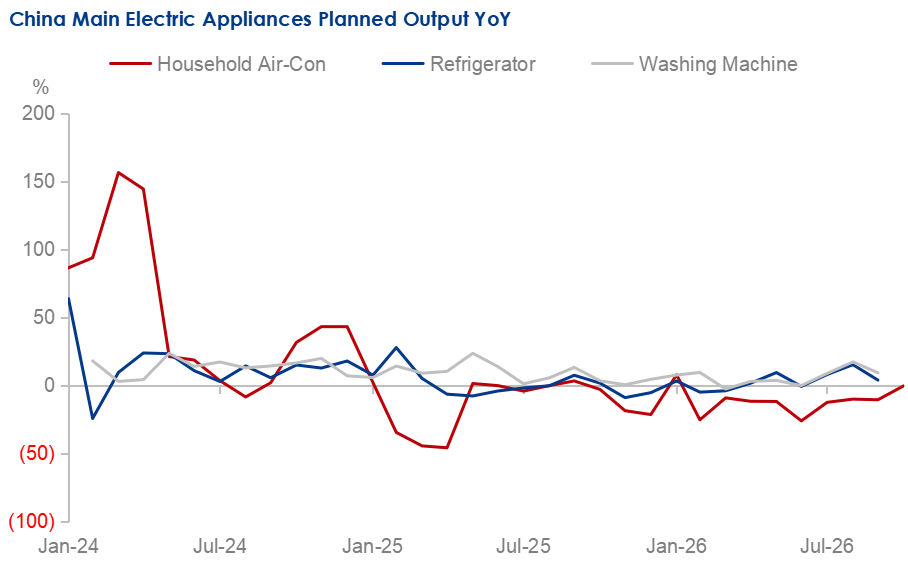
Source: ChinaIOL, Mysteel
This points to only a limited recovery in copper tube demand. Mysteel data show August copper tube output fell by 10.02% month on month to 140,100 tonnes, with capacity utilization down to 60.47%, the steepest decline among surveyed copper semis, and the only product still expected to see output cut in September to a projected 134,900 tonnes. As air conditioner schedules turn positive in October, tube operating rates should stop falling and stabilize, ending the run of declines. However, constrained by weak domestic air conditioner sales and material substitution, even if copper tube production and sales recover, the upside is likely to remain limited.
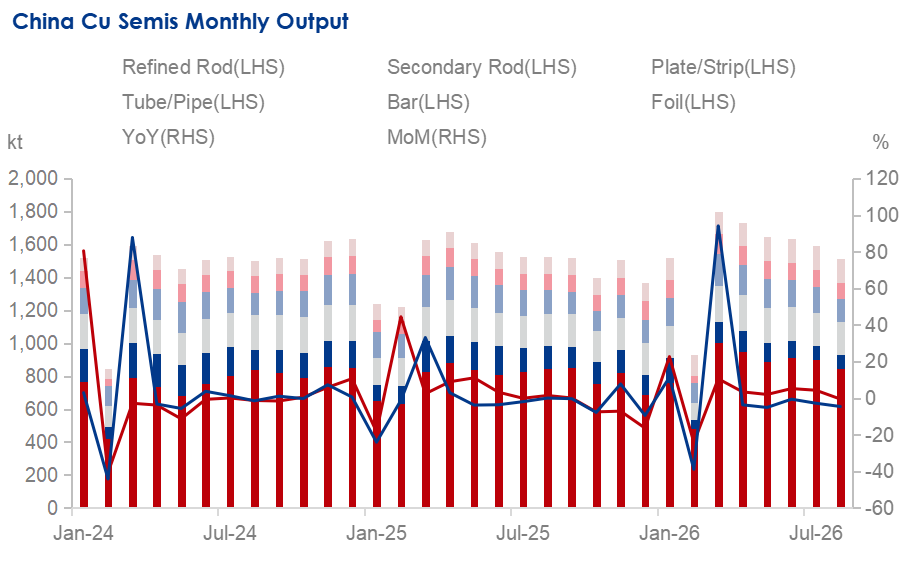
Source: Mysteel
Real estate's drag on copper demand may stop deepening
On real estate, National Bureau of Statistics data for January-August released on September 15 confirmed the property chain's continued weakness. Development investment fell by 19.9% year on year, new starts by 24.8%, completions by 23.7%, and the sales area and value of new commercial housing by 12.1% and by 13.0%, respectively. There are nonetheless marginal signals worth noting, as online-registered second-hand home transactions rose by 10.6% year on year, unsold new commercial housing inventory fell for a sixth straight month at end-August, new home prices in first-tier cities turned from flat to up by 0.1% month on month, and the number of major cities posting narrower year-on-year price declines rose noticeably.
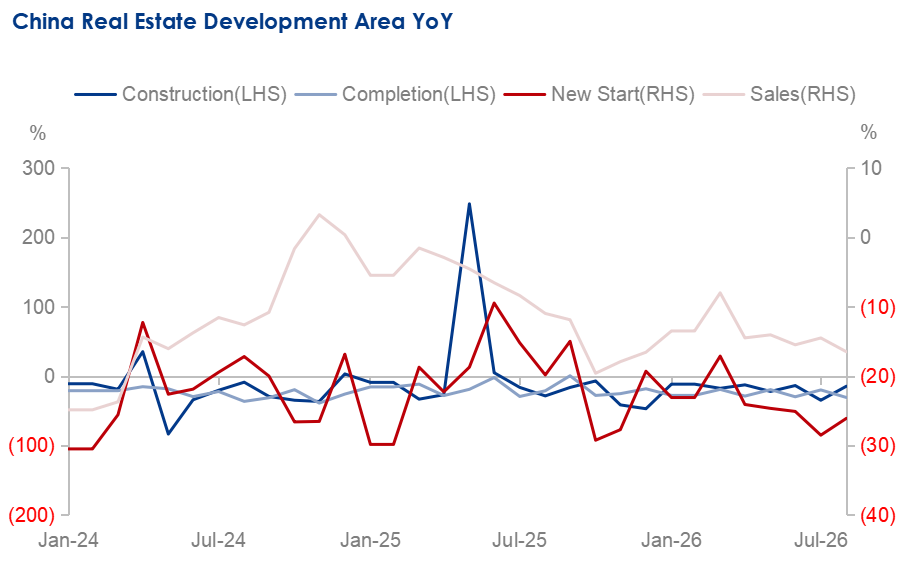
Source: NBS, Mysteel
The implications for copper demand are twofold. On the negative side, declines across new starts, construction and completions mean building wire and cable, copper tube consumption in plumbing and copper bar usage in bathroom hardware will likely remain in lack of strong order support in September and October. Mysteel expects September copper bar output to rise by 0.22% month on month, still down by 1.86% year on year. On the mildly positive side, brisk second-hand transactions support renovation, refurbishment and partial remodeling demand, providing a modest floor for retail demand for wire and cable, switches and sockets, and plumbing fittings. Regarding China's supporting policies, the late-August initiative to acquire existing homes and operate them as rentals is still in its early implementation phase and targets destocking rather than new starts, so its direct boost to refined copper demand in the current period is limited, and real incremental demand must wait for completions to recover. All told, the reasonable expectation for property-linked copper demand in September and October is only a narrower negative contribution.
Automobile market to improve despite cyclical limits
In China's auto market, August saw weaker domestic demand but strong export growth, while demand for new energy vehicles (NEVs) continued to accelerate. Production and sales for vehicles reached 2.684 million and 2.712 million units, up by 4.3% and 4.9% month on month but down by 4.7% and 5.1% year on year. NEV output and sales were 1.653 million and 1.643 million units, up by 18.9% and 17.8% year on year, accounting for 60.6% of new-vehicle sales, above 60% for a second straight month and a new record. Exports were the standout, 1.01 million units in August, up by 65.3% year on year and above one million for a third consecutive month. January–August exports totaled 7.153 million units, up by 66.7%, including 3.435 million NEVs, up by roughly 120% year on year.
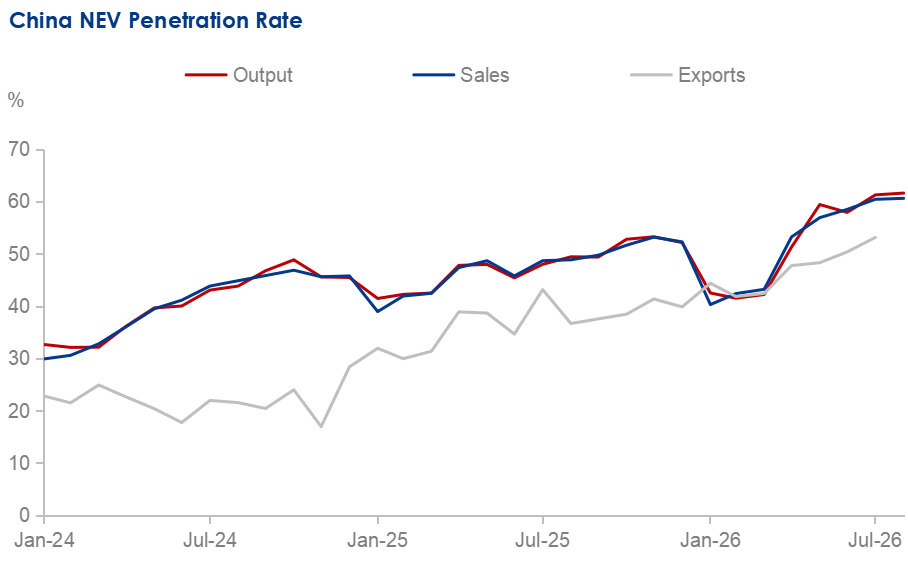
Source: CAAM, Mysteel
Looking ahead, vehicle production and sales in September and October are likely to be stronger month on month but weaker year on year. As the traditional peak season begins, showroom traffic keeps recovering, and the trade-in program and local subsidies will continue at their current pace, providing some support to the market. Meanwhile, the October National Day holiday should further lift sales of larger NEVs. But against last year's high base and persistently firm oil prices, the market is unlikely to replicate the highlighted performance during previous peak seasons.
Conclusion
Overall, during September and October, end-use markets in China will offer support to China's copper consumption, though variations will exist across sectors. The power grid and new energy will underpin aggregate volumes, with October entering a sprint phase, and appliances may show a scheduling turning point but add little at the margin. While autos' structural upgrading will offset the dampening effect of a high base and oil price swings on peak-season performance, the real estate industry may keep dragging on demand, though the drag stops deepening. China's copper market is likely to see modestly improving end-use consumption, a peak season for copper semis that likely falls short of prior years, a still-tight refined copper balance, and widely fluctuating prices at high levels.
More regular analysis and comprehensive data on China's copper industry are available in Mysteel Copper Weekly, Mysteel Copper Monthly, and Mysteel Copper Database. Reach out to us via Mysteel's official website: Latest & Reliable Copper Market Price in China | Mysteel, and follow Mysteel Non-Ferrous for more insights!
Written by Zhaorui Cui, cuizhaorui@mysteel.com
Edited by Mingyuan Wang, wangmingyuan@mysteel.com