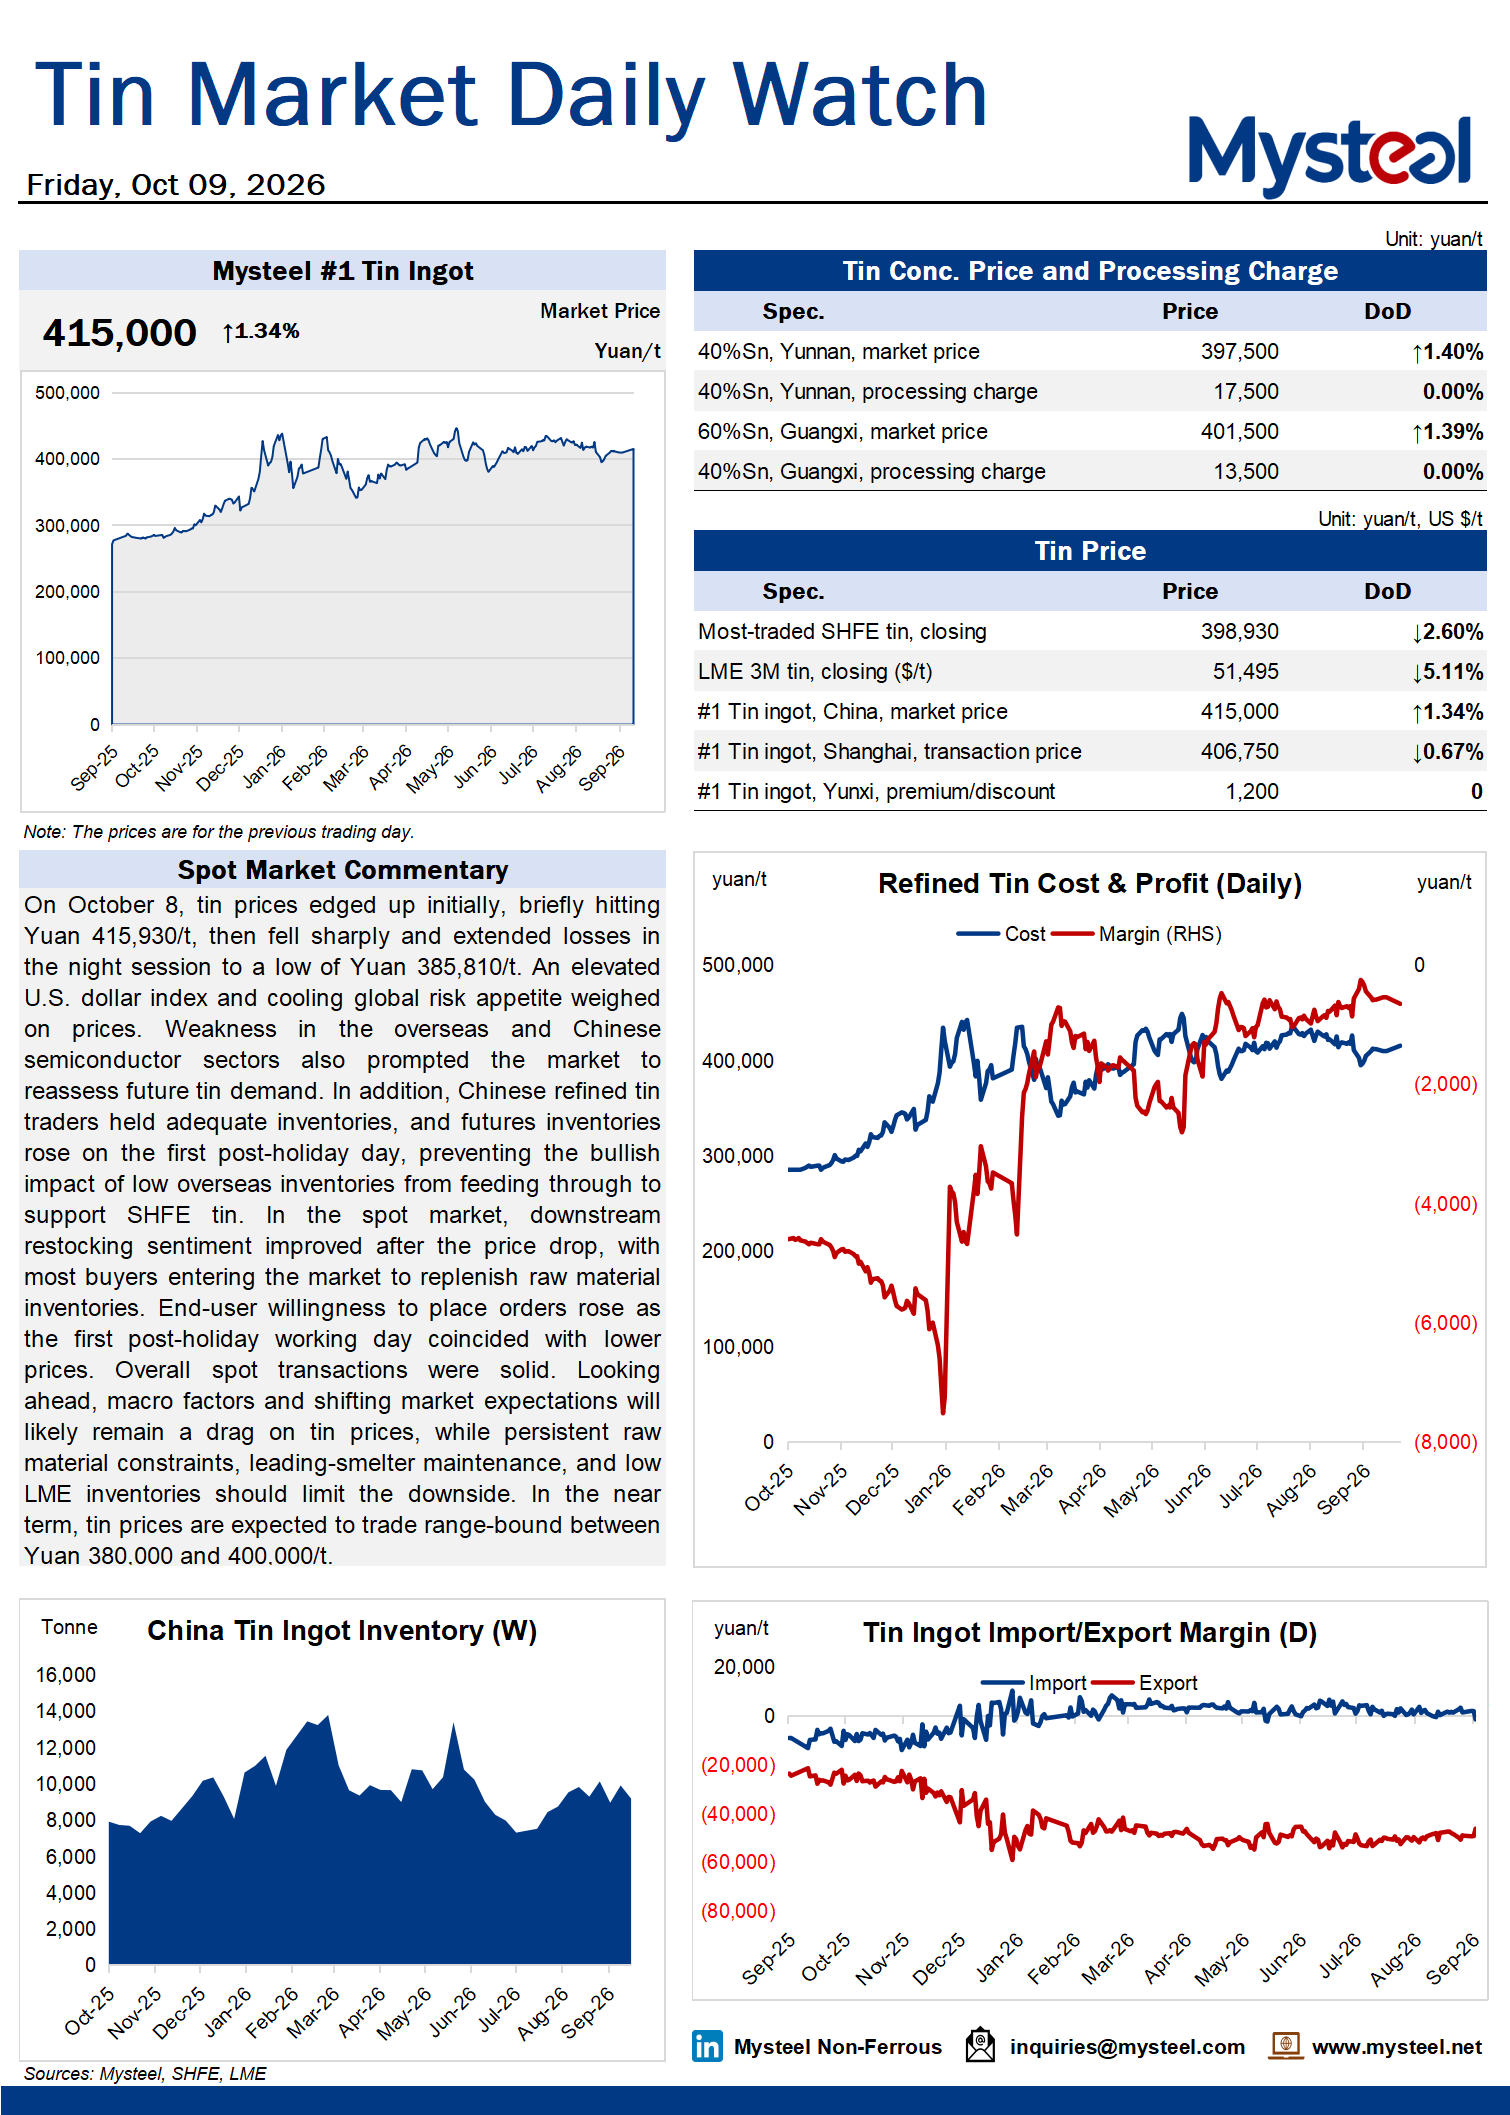
On October 8, tin prices edged up initially, briefly hitting Yuan 415,930/t, then fell sharply and extended losses in the night session to a low of Yuan 385,810/t. An elevated U.S. dollar index and cooling global risk appetite weighed on prices. Weakness in the overseas and Chinese semiconductor sectors also prompted the market to reassess future tin demand. In addition, Chinese refined tin traders held adequate inventories, and futures inventories rose on the first post-holiday day, preventing the bullish impact of low overseas inventories from feeding through to support SHFE tin. In the spot market, downstream restocking sentiment improved after the price drop, with most buyers entering the market to replenish raw material inventories. End-user willingness to place orders rose as the first post-holiday working day coincided with lower prices. Overall spot transactions were solid. Looking ahead, macro factors and shifting market expectations will likely remain a drag on tin prices, while persistent raw material constraints, leading-smelter maintenance, and low LME inventories should limit the downside. In the near term, tin prices are expected to trade range-bound between Yuan 380,000 and 400,000/t.