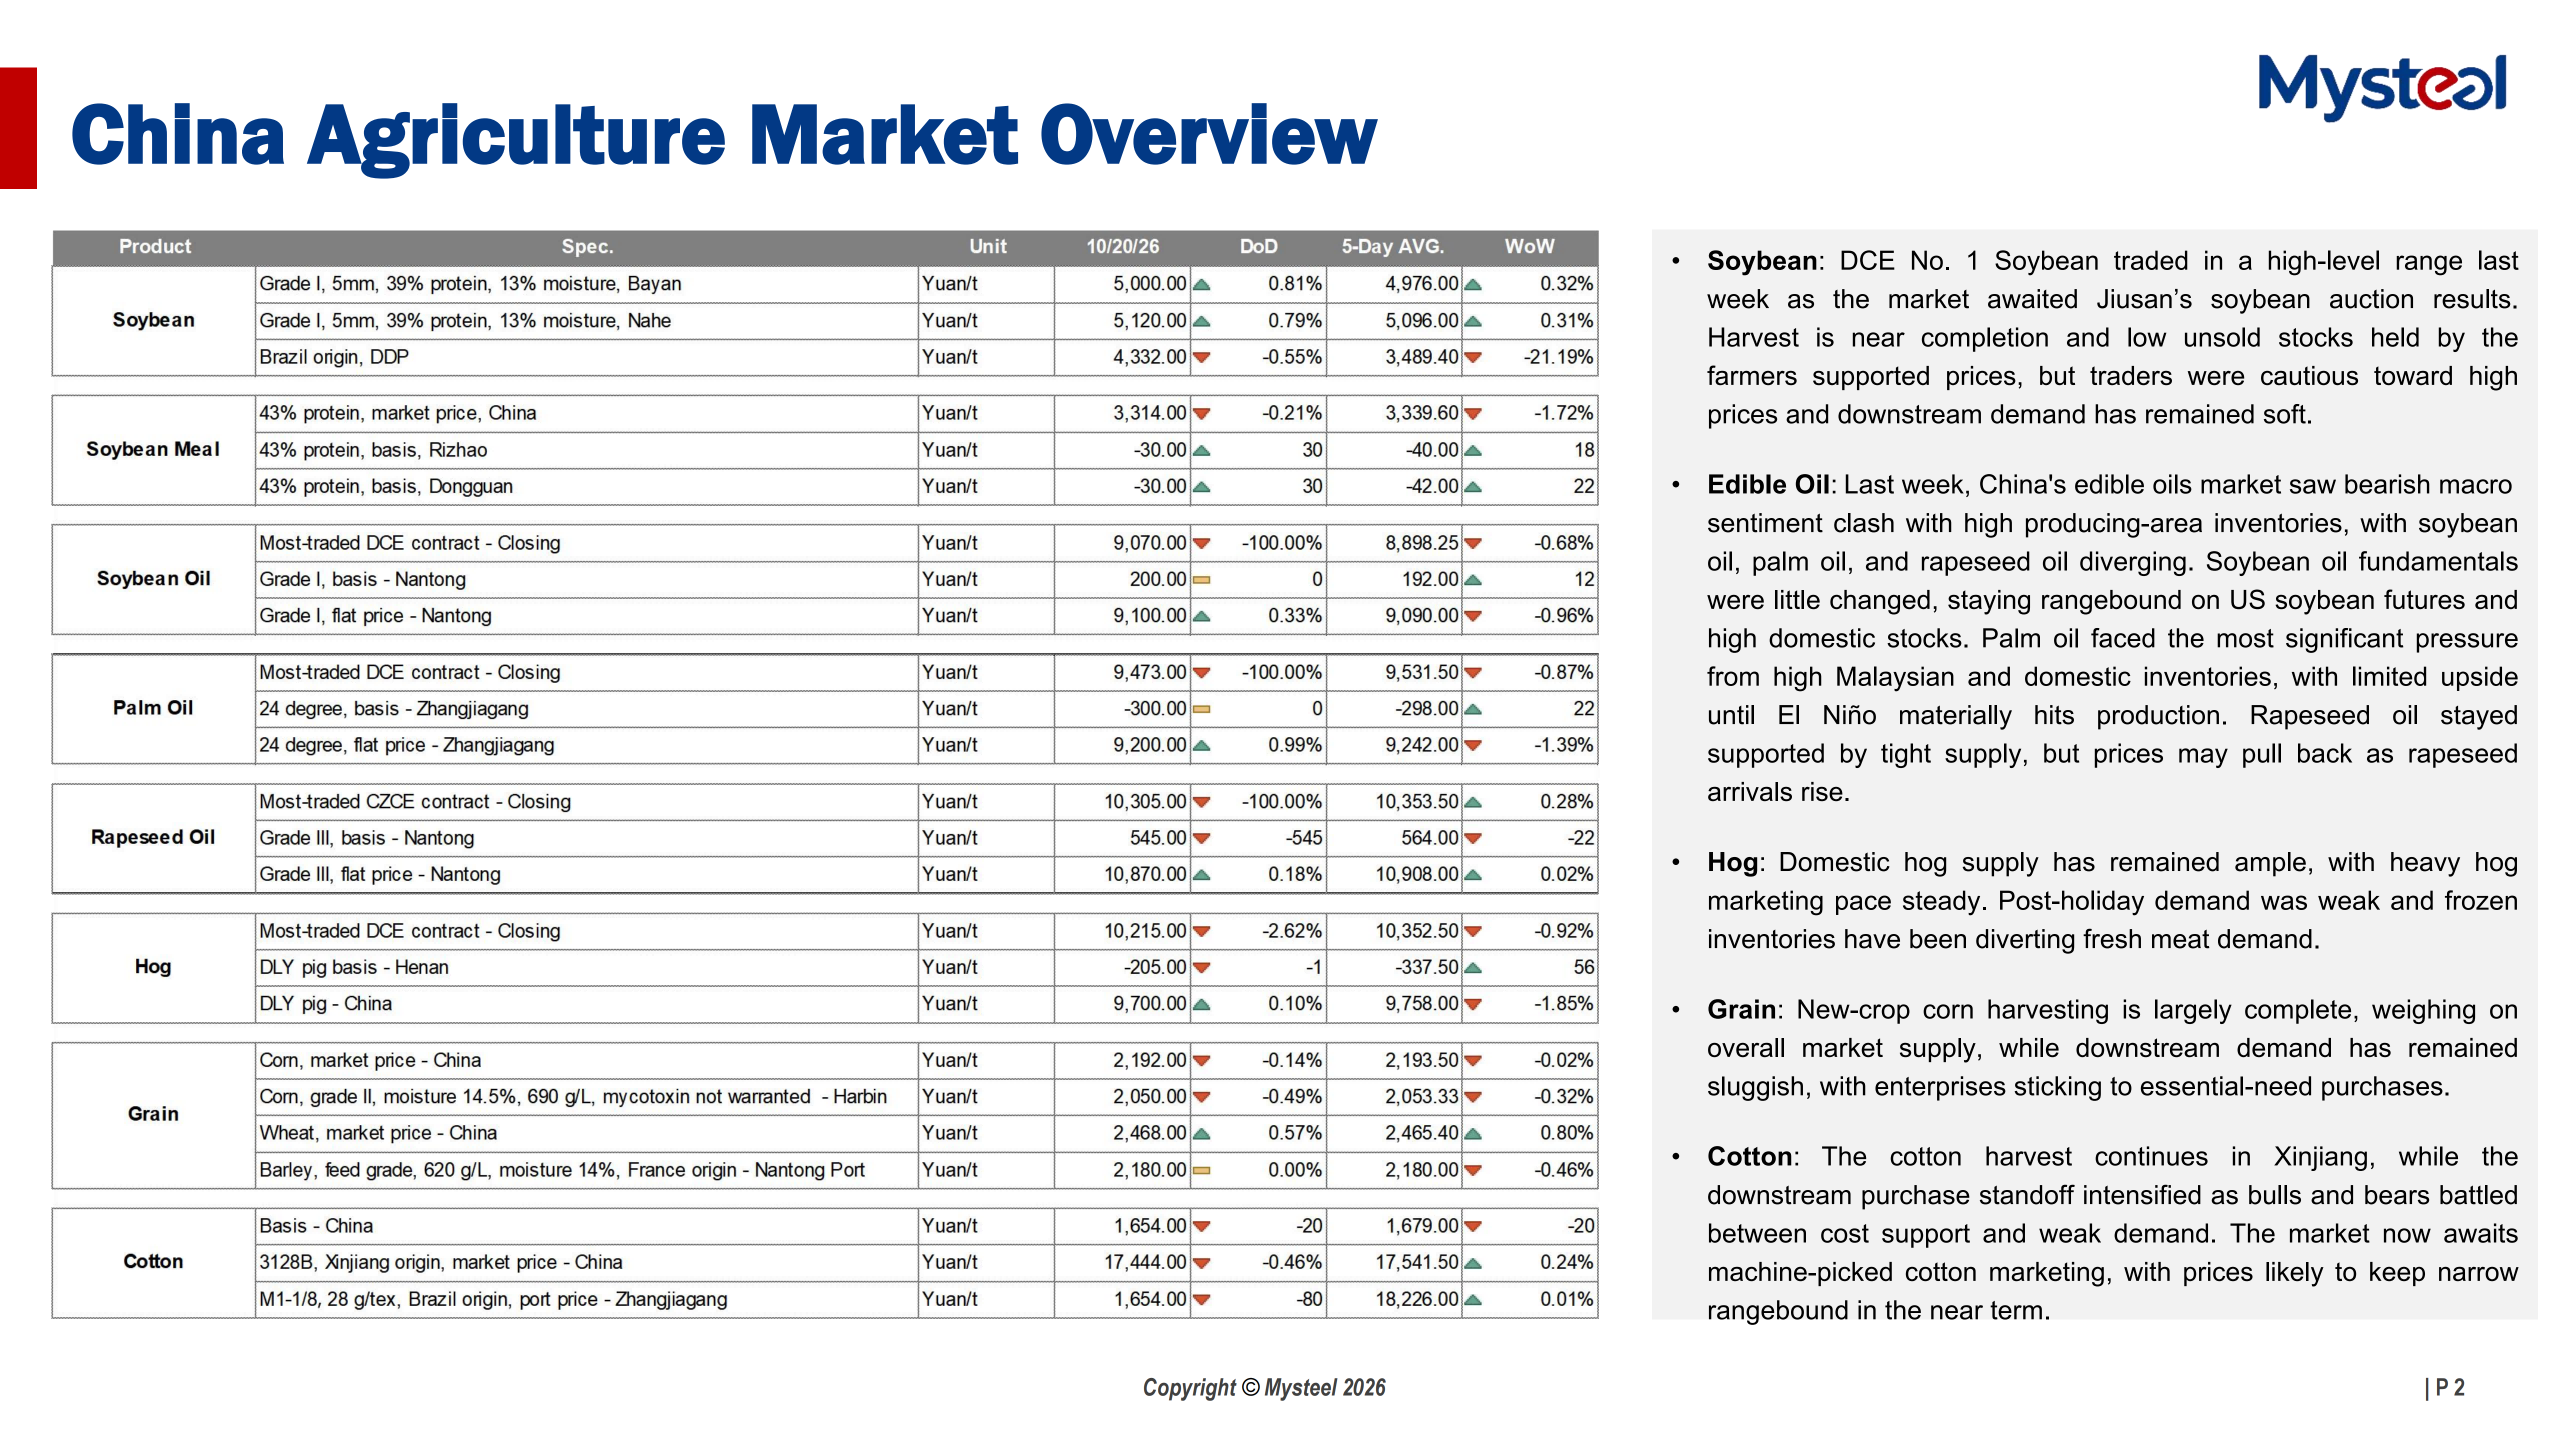
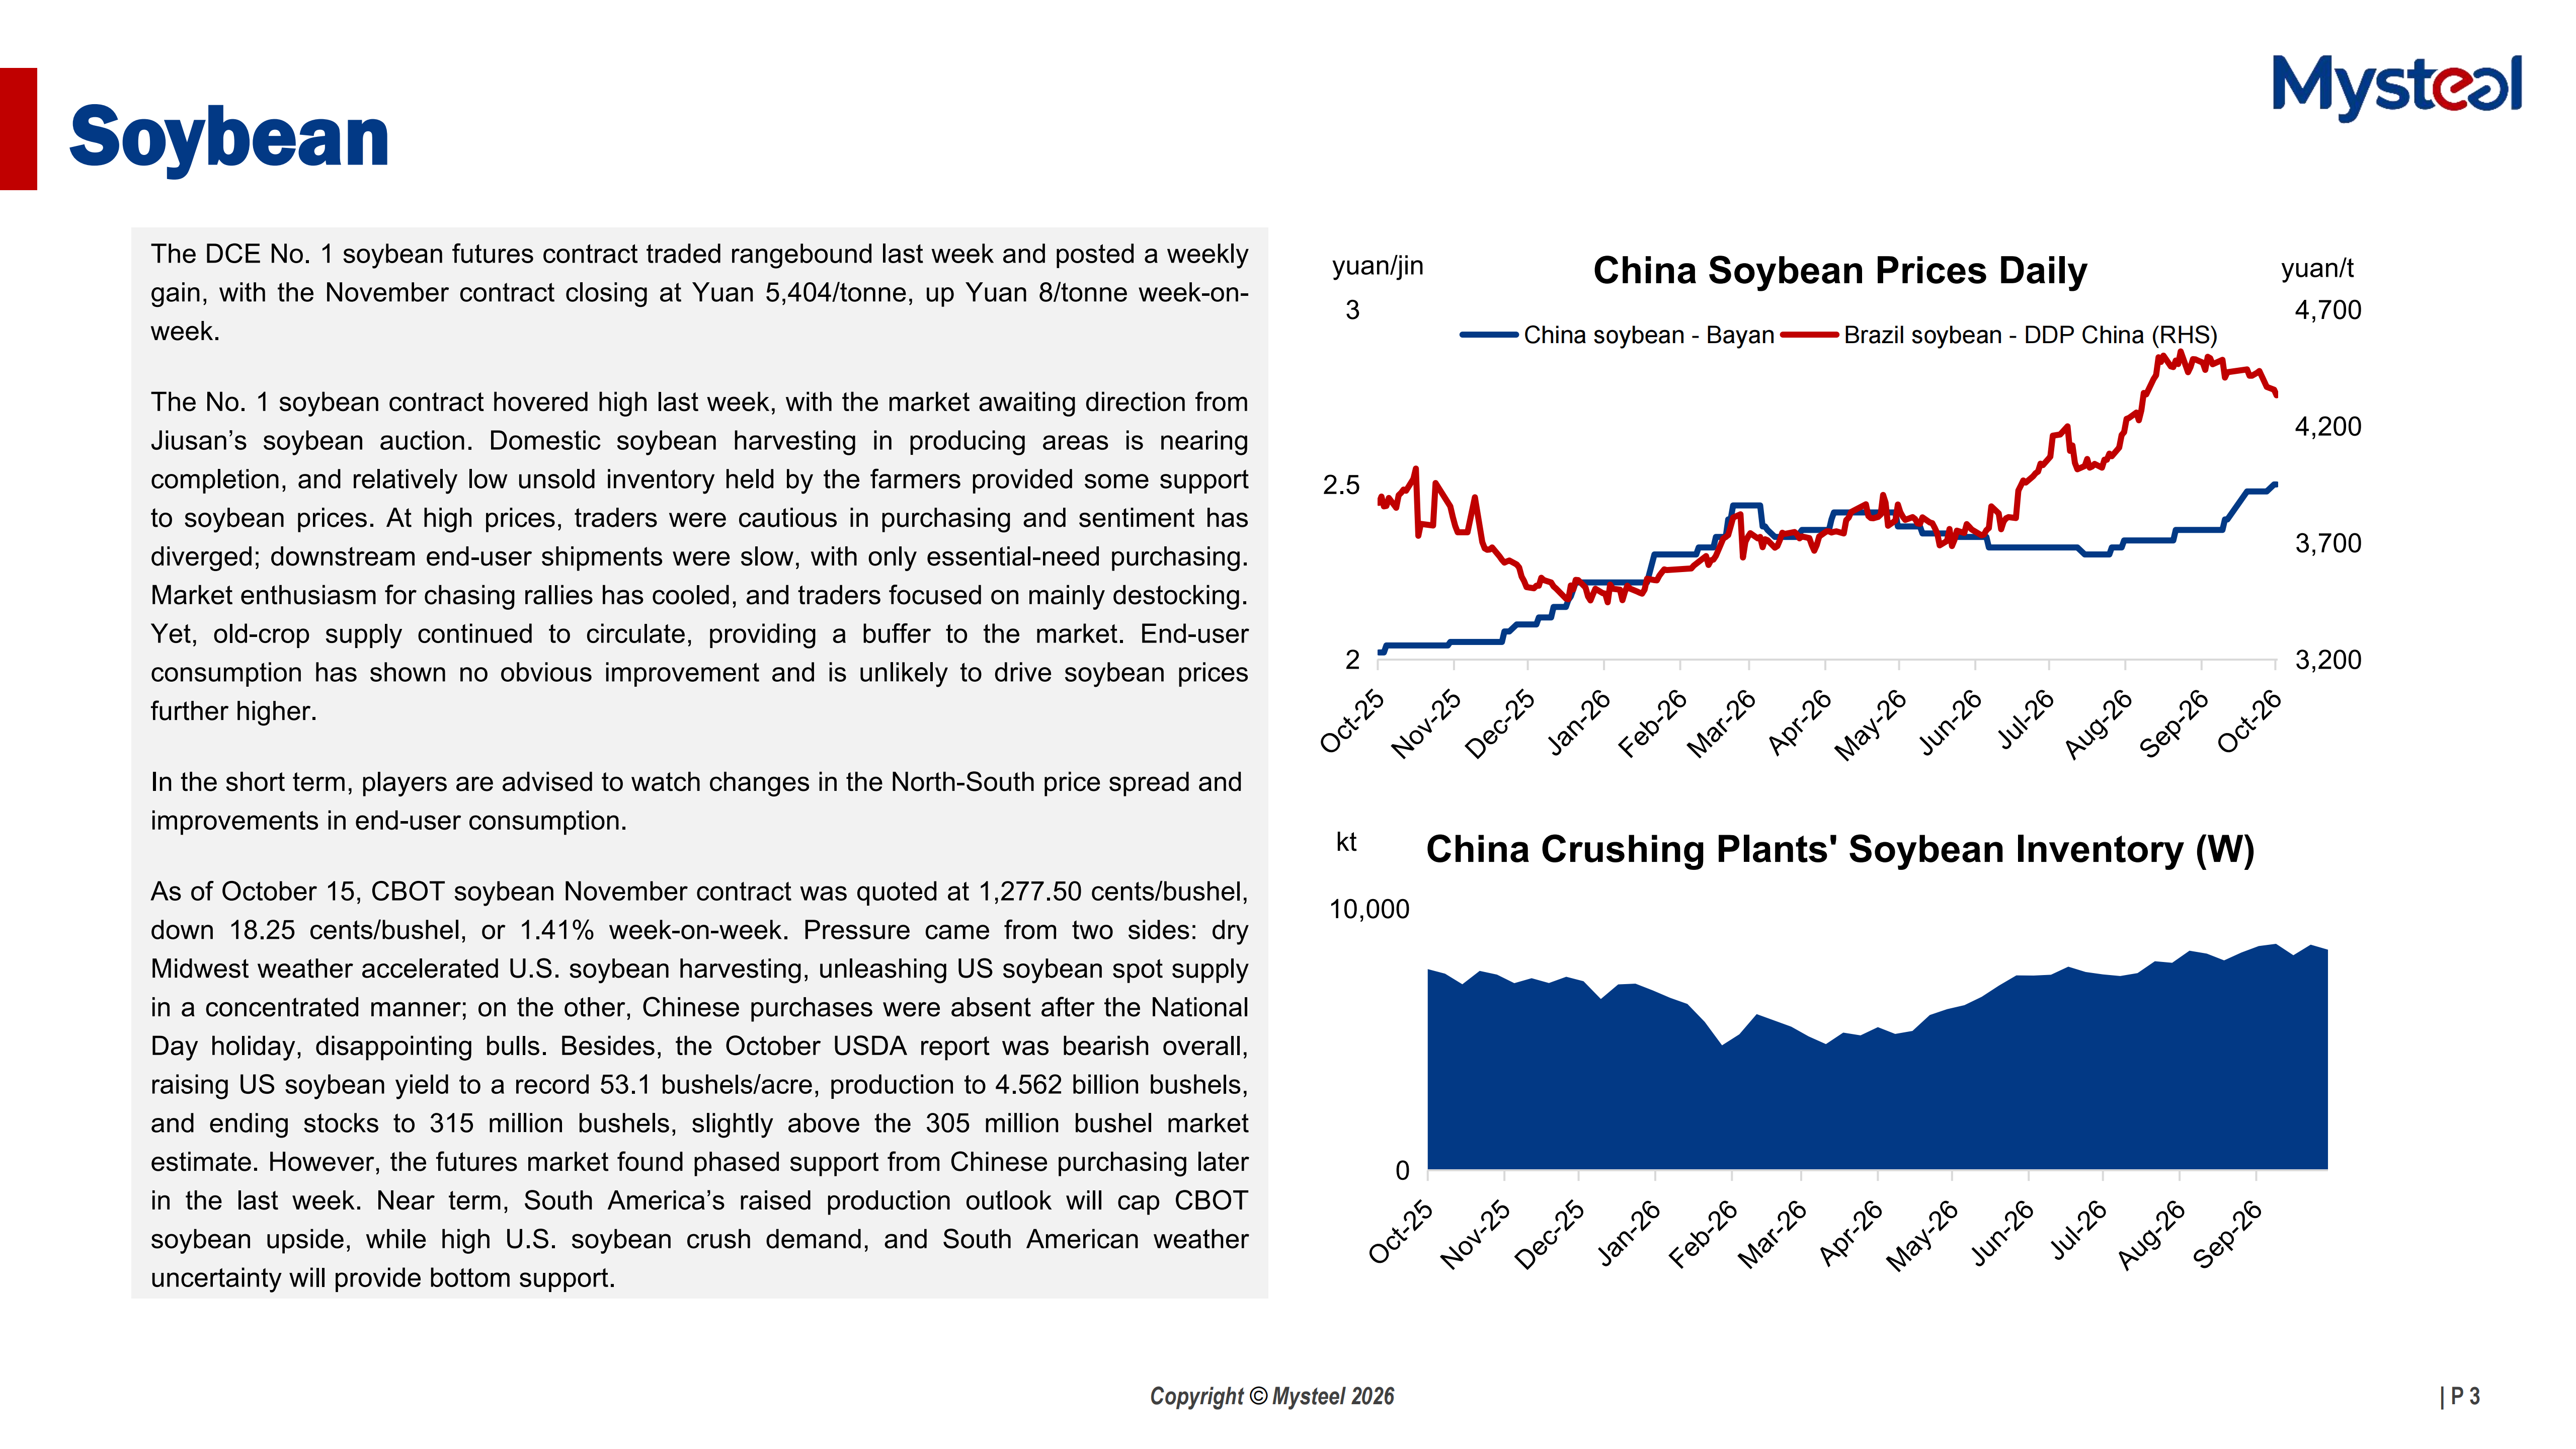
Soybean: DCE No. 1 Soybean traded in a high-level range last week as the market awaited Jiusan's soybean auction results. Harvest is near completion and low unsold stocks held by the farmers supported prices, but traders were cautious toward high prices and downstream demand has remained soft.
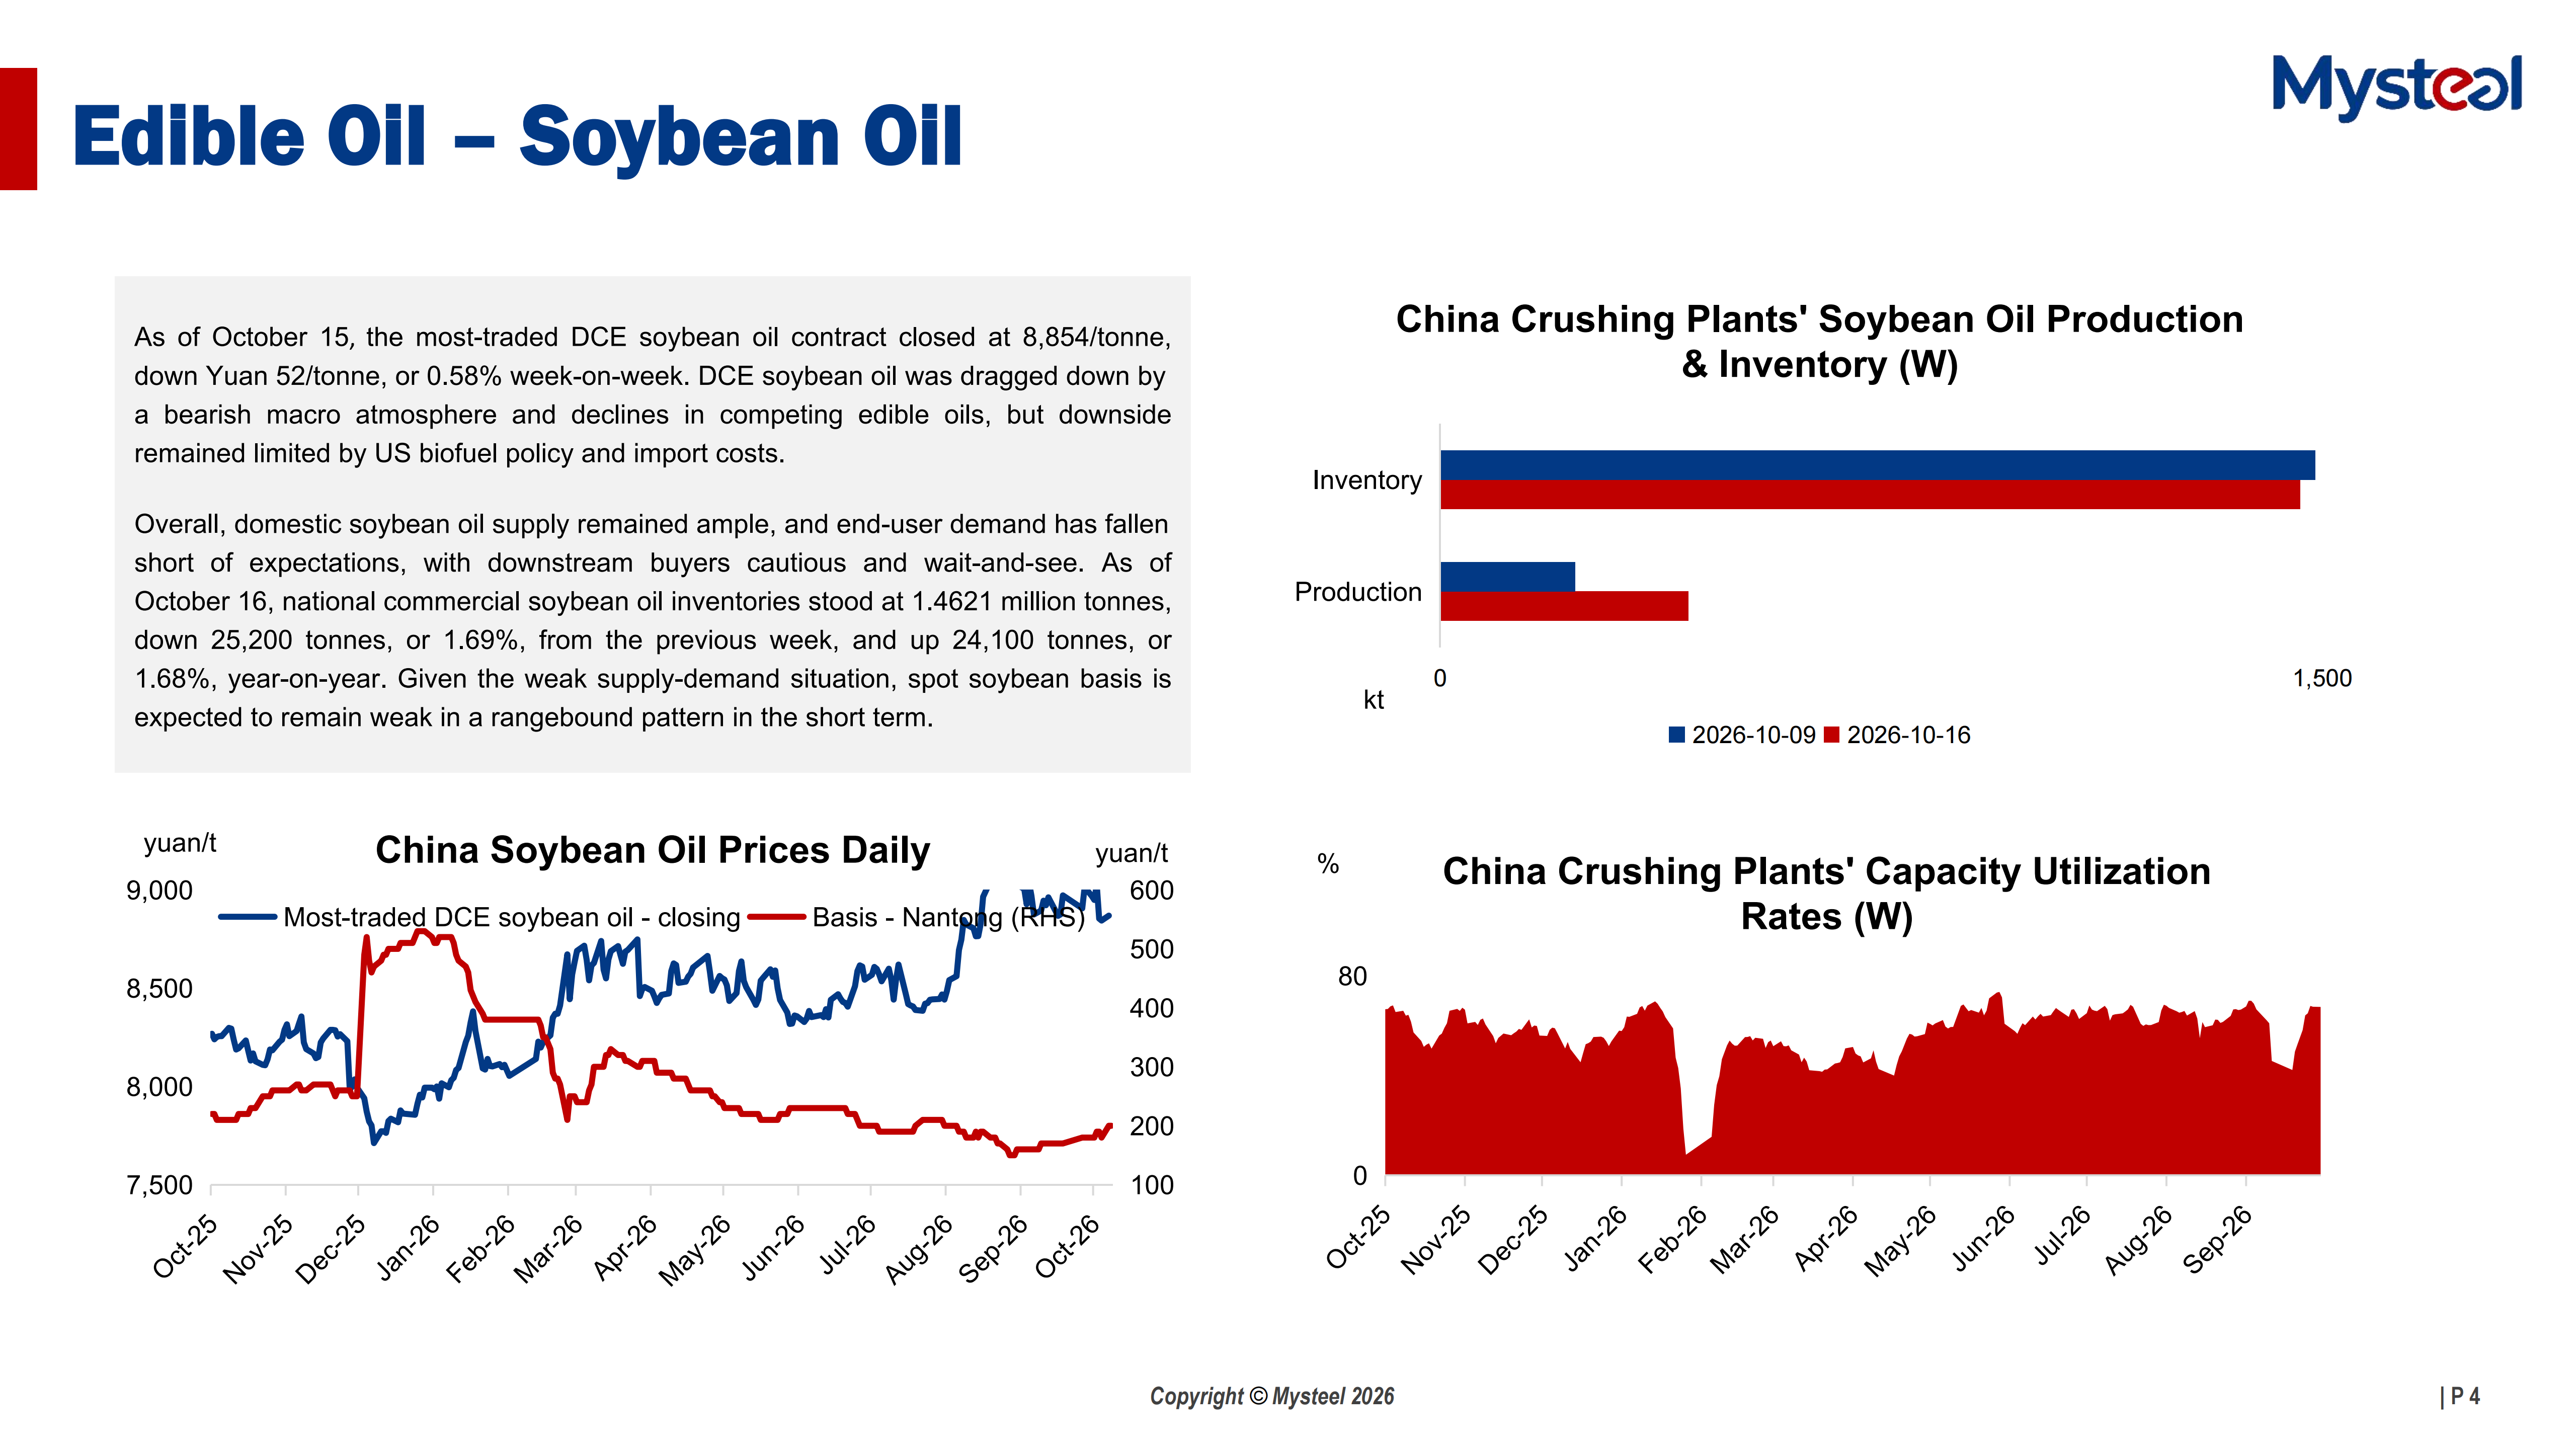
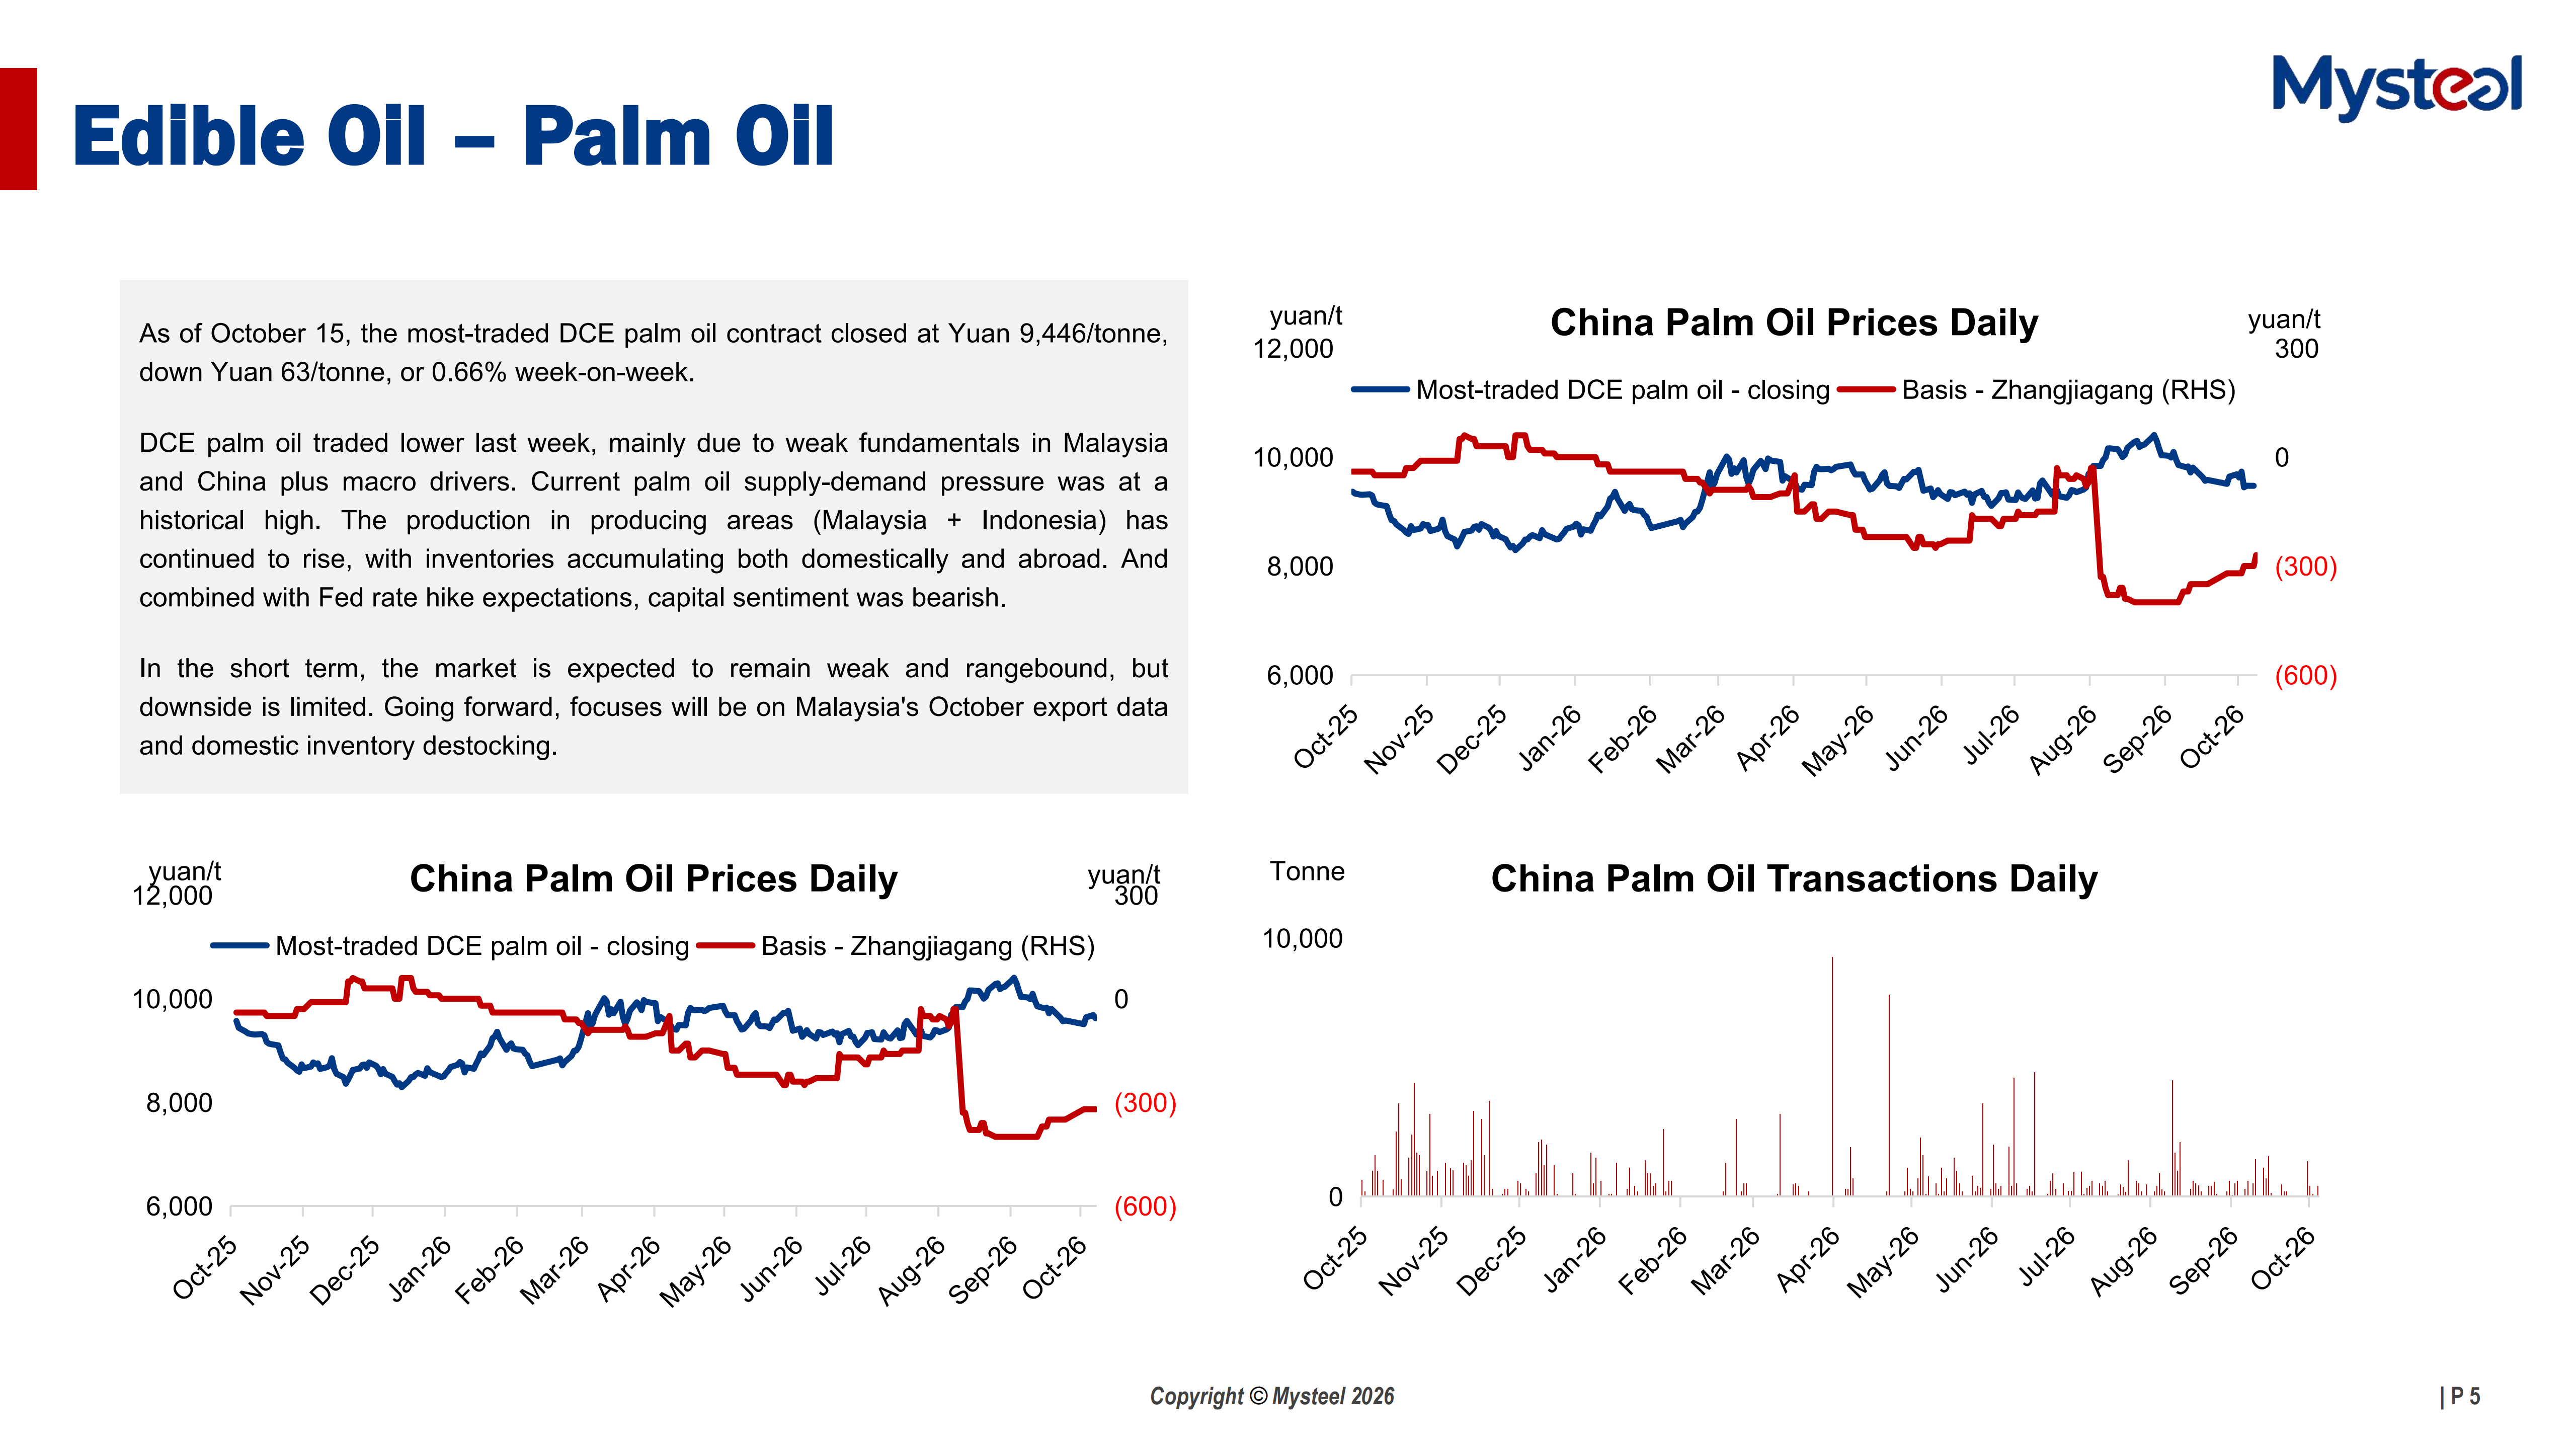
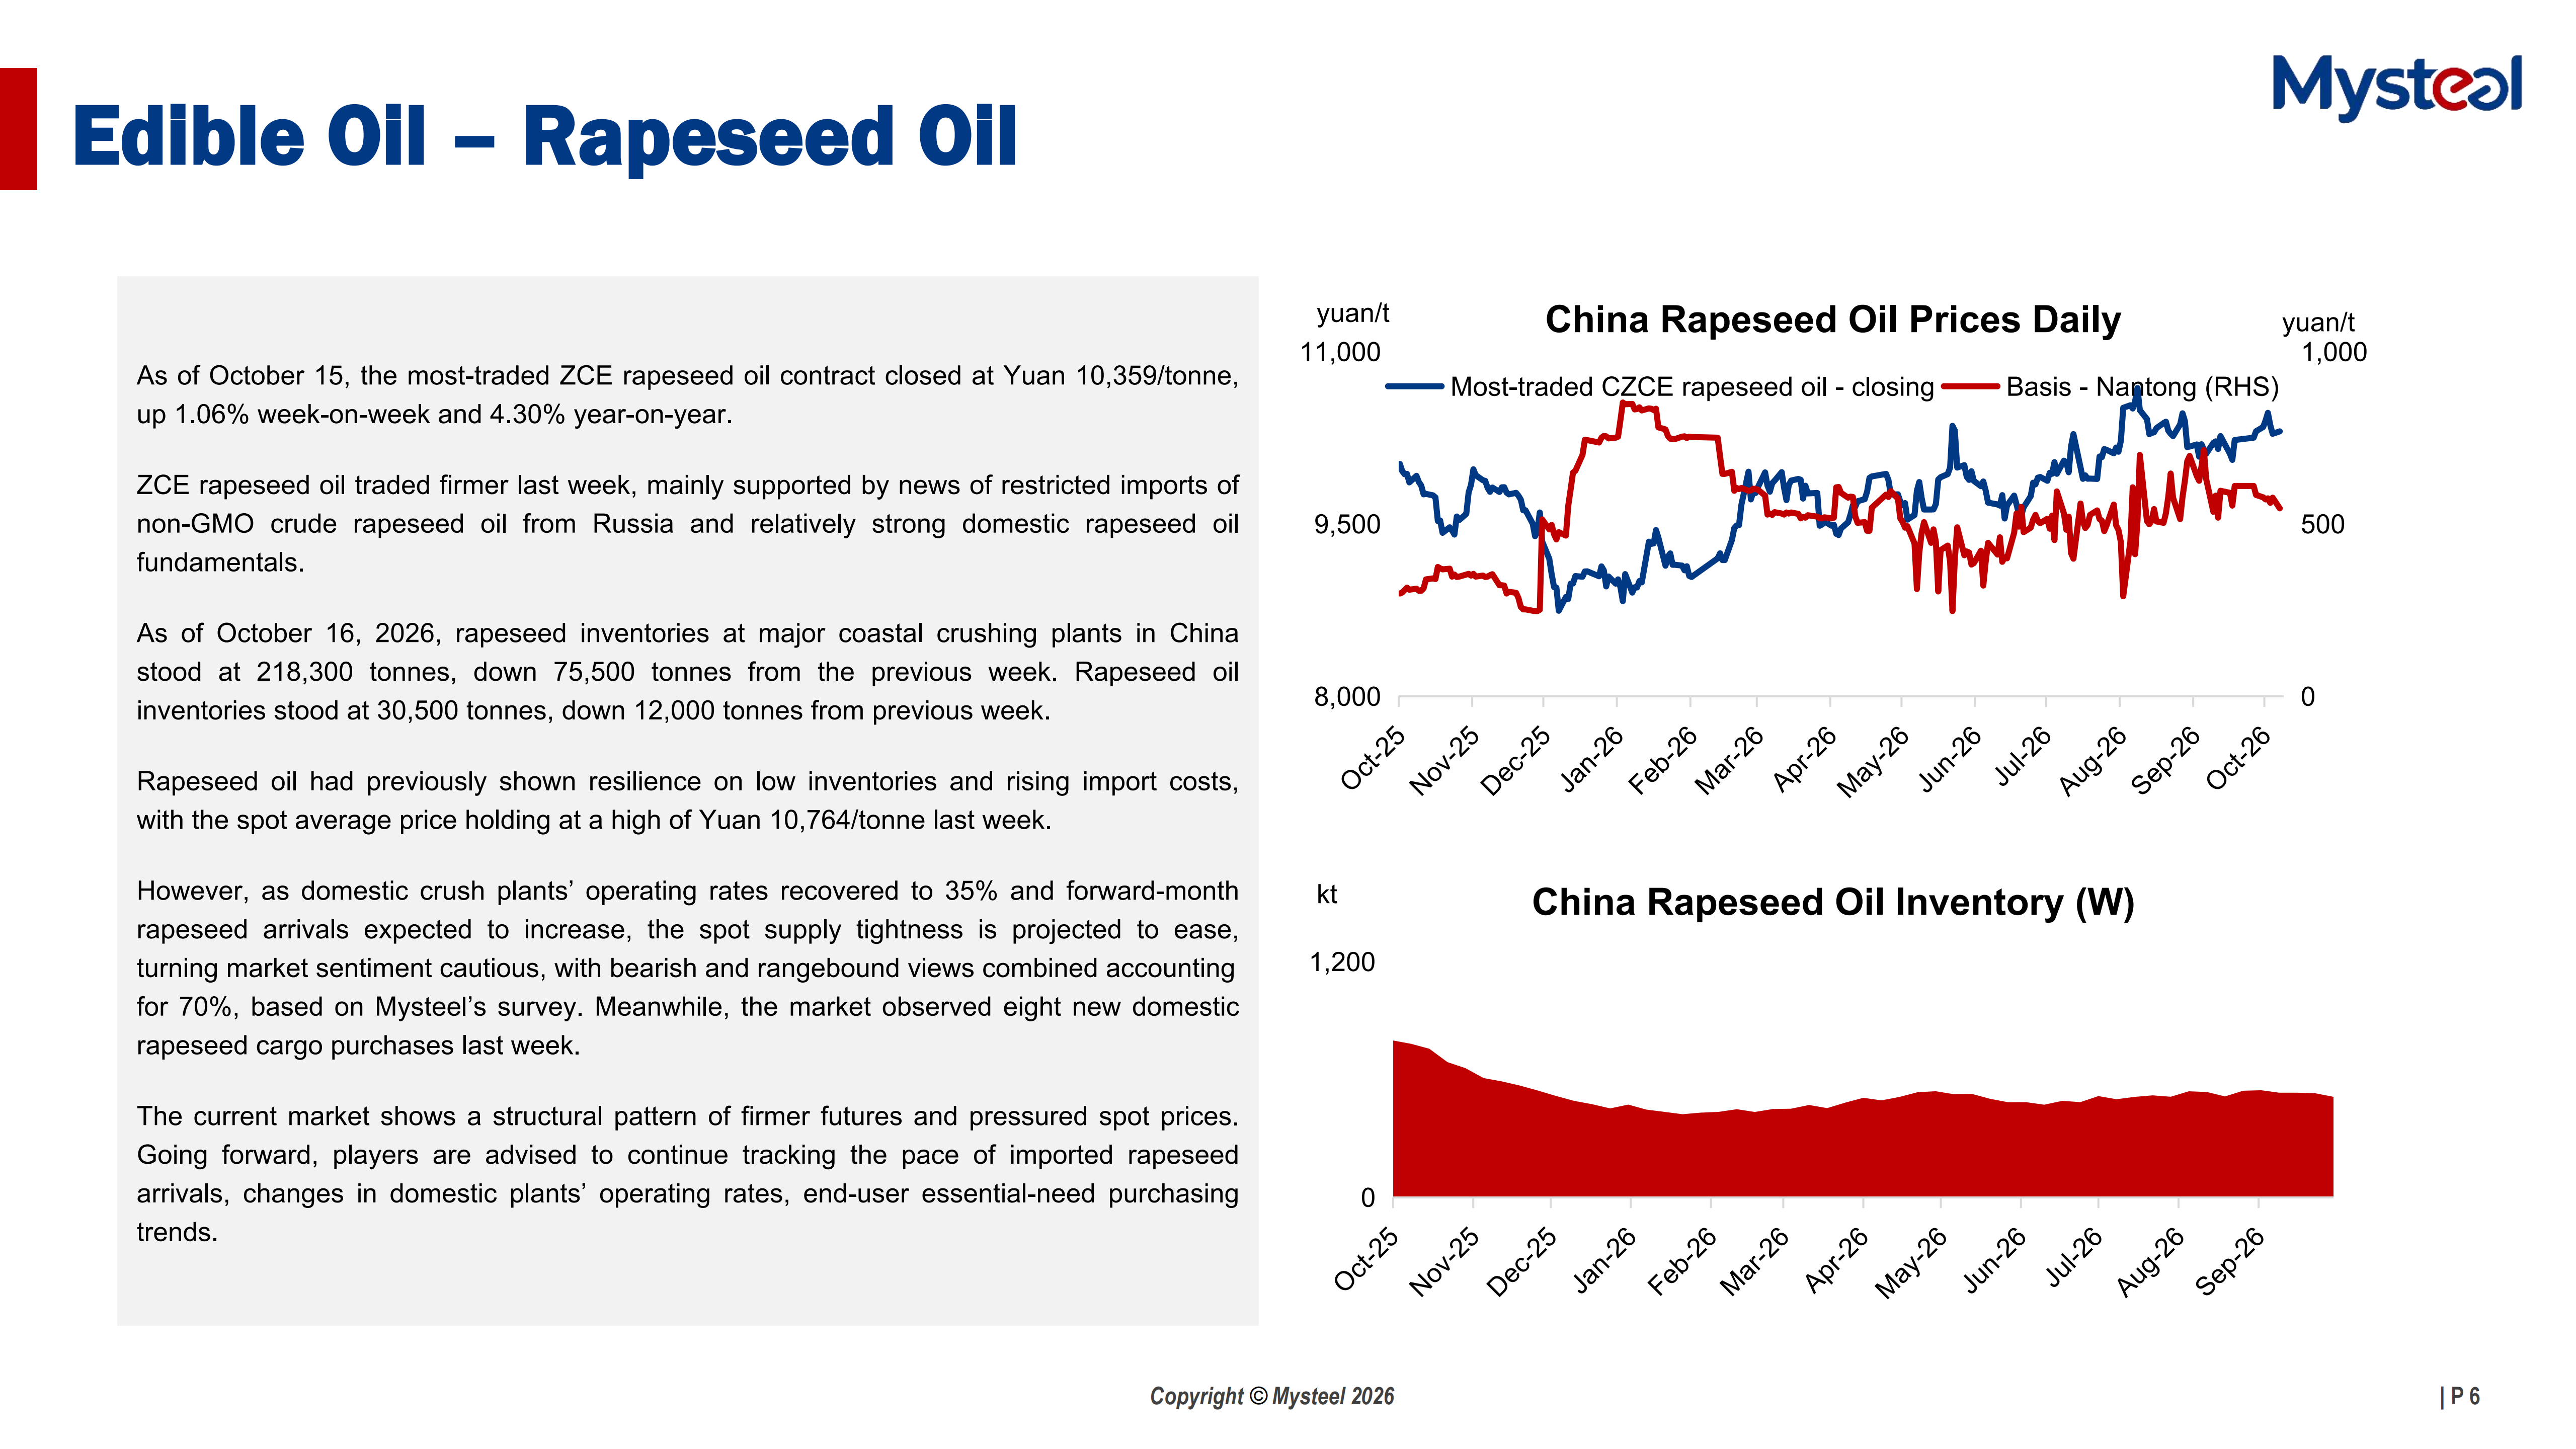
Edible Oil: Last week, China's edible oils market saw bearish macro sentiment clash with high producing-area inventories, with soybean oil, palm oil, and rapeseed oil diverging. Soybean oil fundamentals were little changed, staying rangebound on US soybean futures and high domestic stocks. Palm oil faced the most significant pressure from high Malaysian and domestic inventories, with limited upside until El Niño materially hits production. Rapeseed oil stayed supported by tight supply, but prices may pull back as rapeseed arrivals rise.
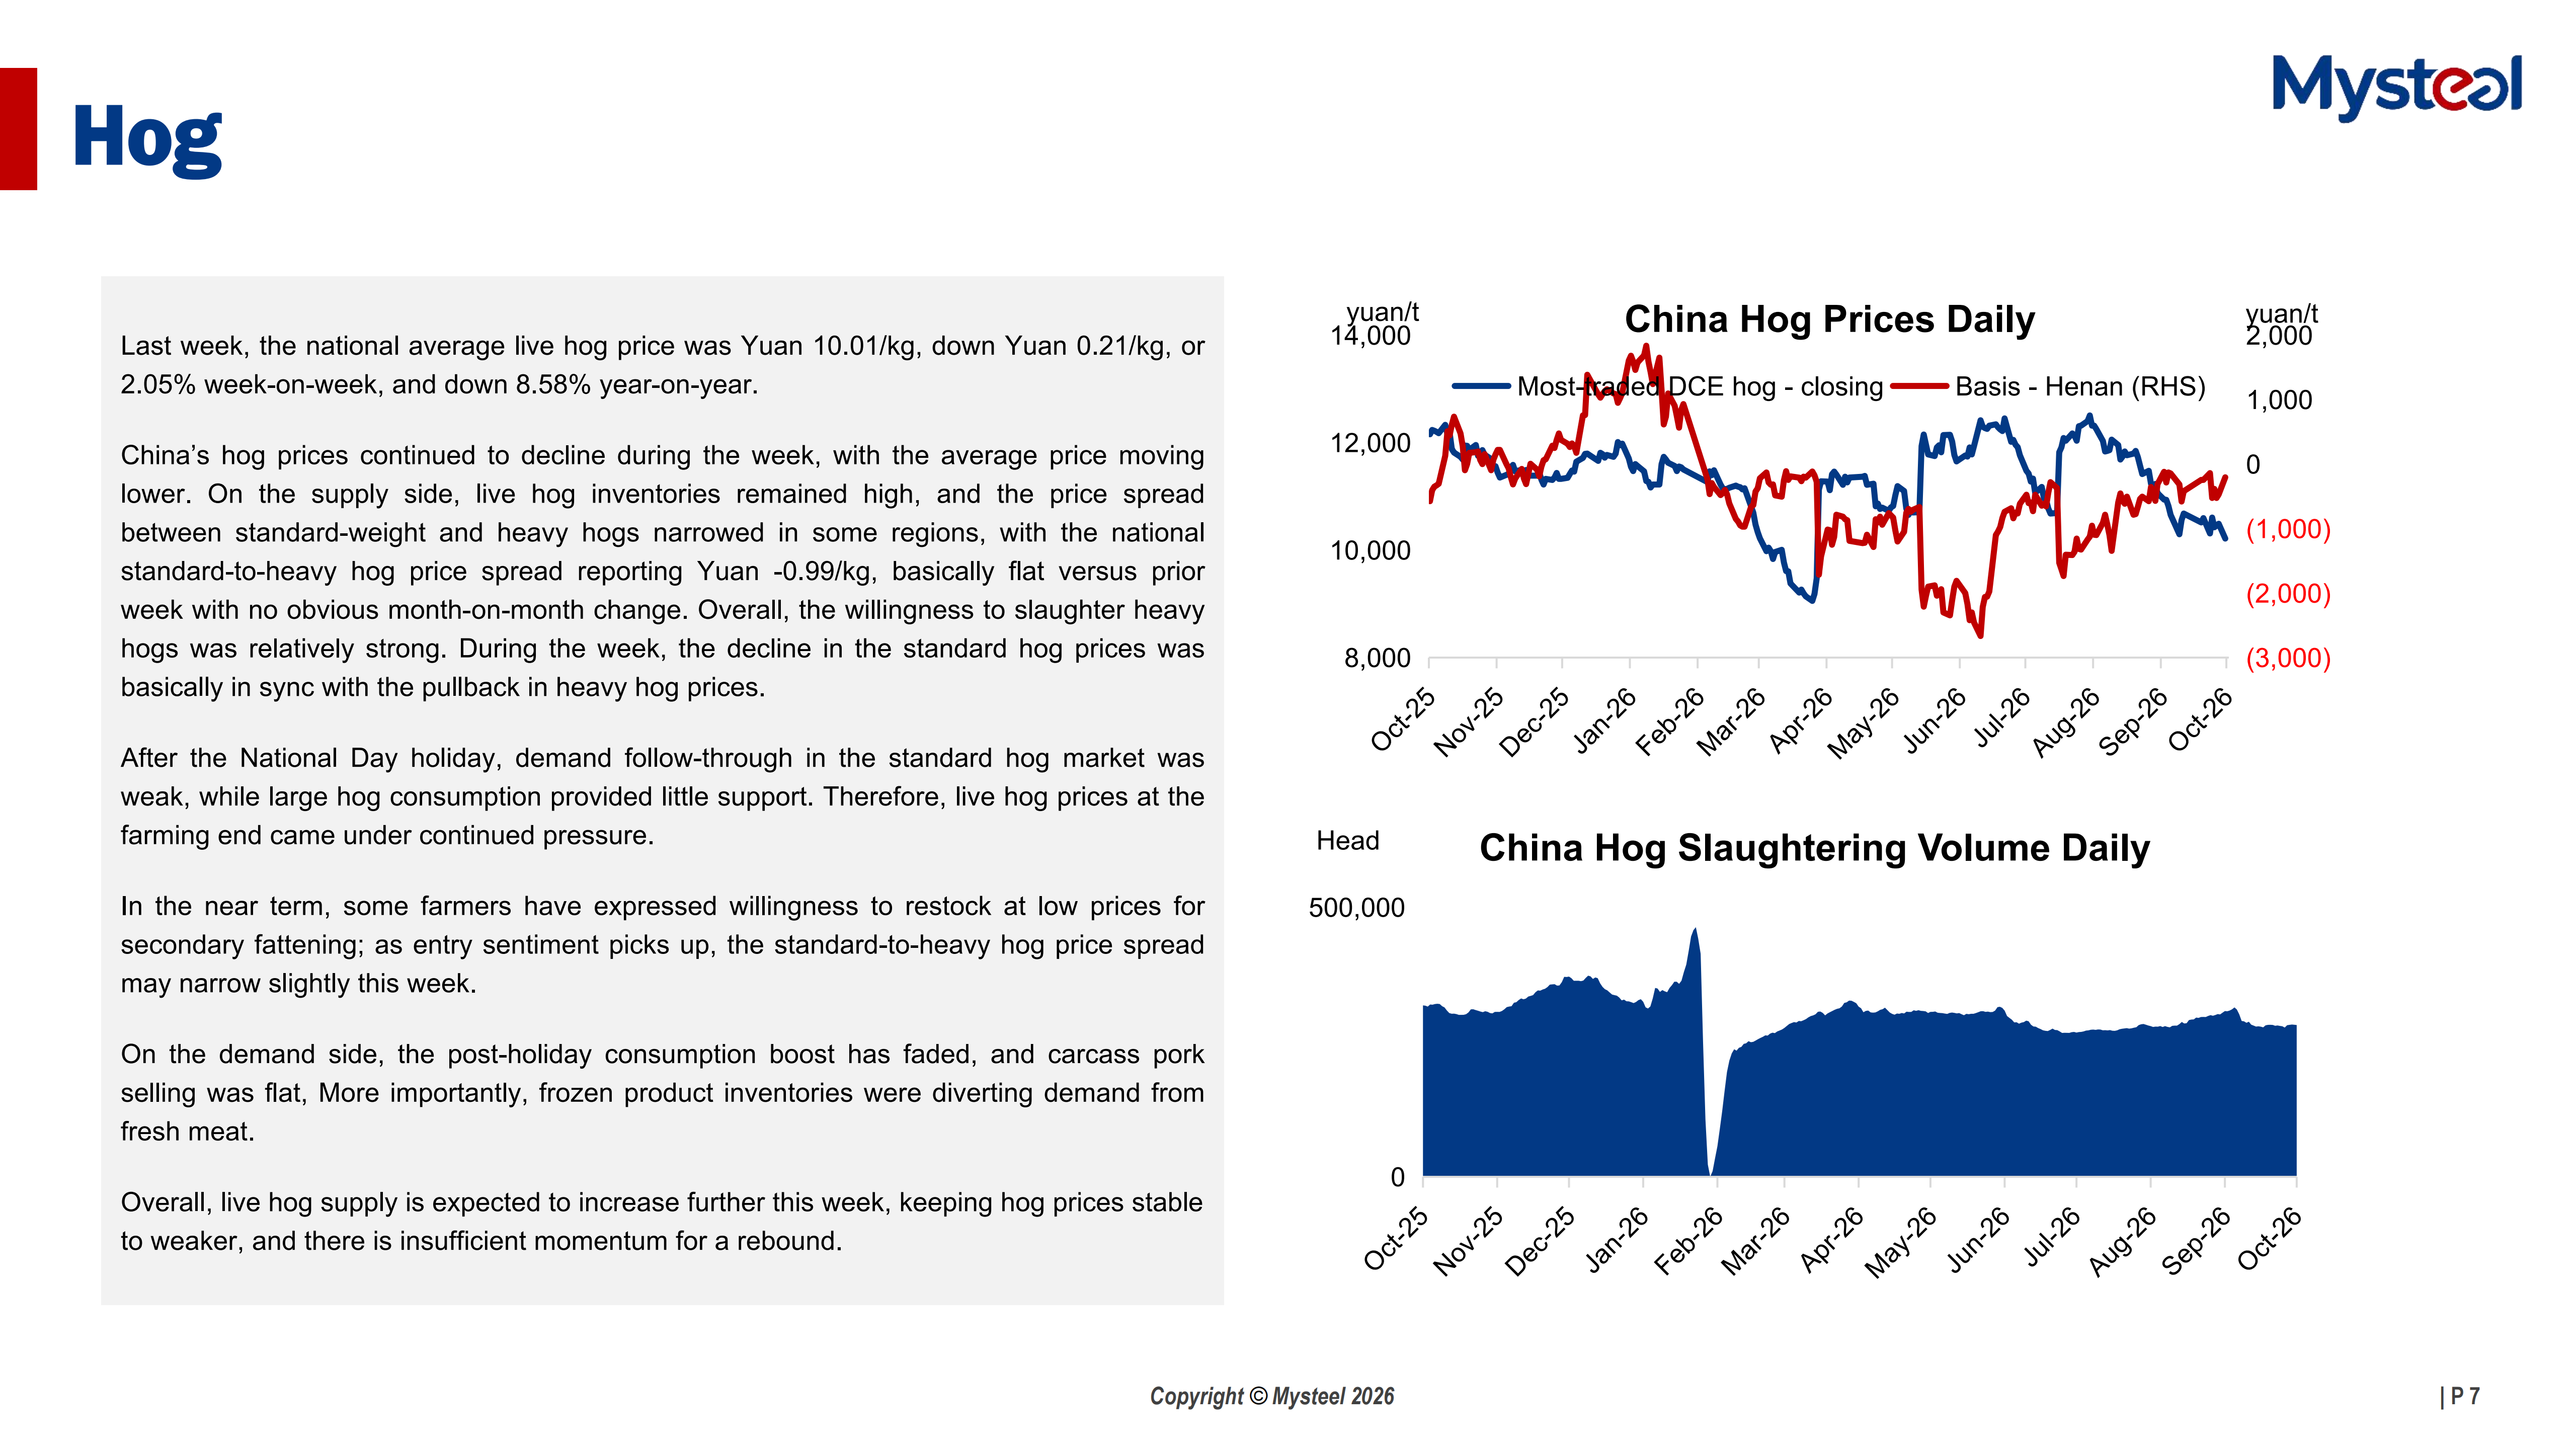
Hog: Domestic hog supply has remained ample, with heavy hog marketing pace steady. Post-holiday demand was weak and frozen inventories have been diverting fresh meat demand.
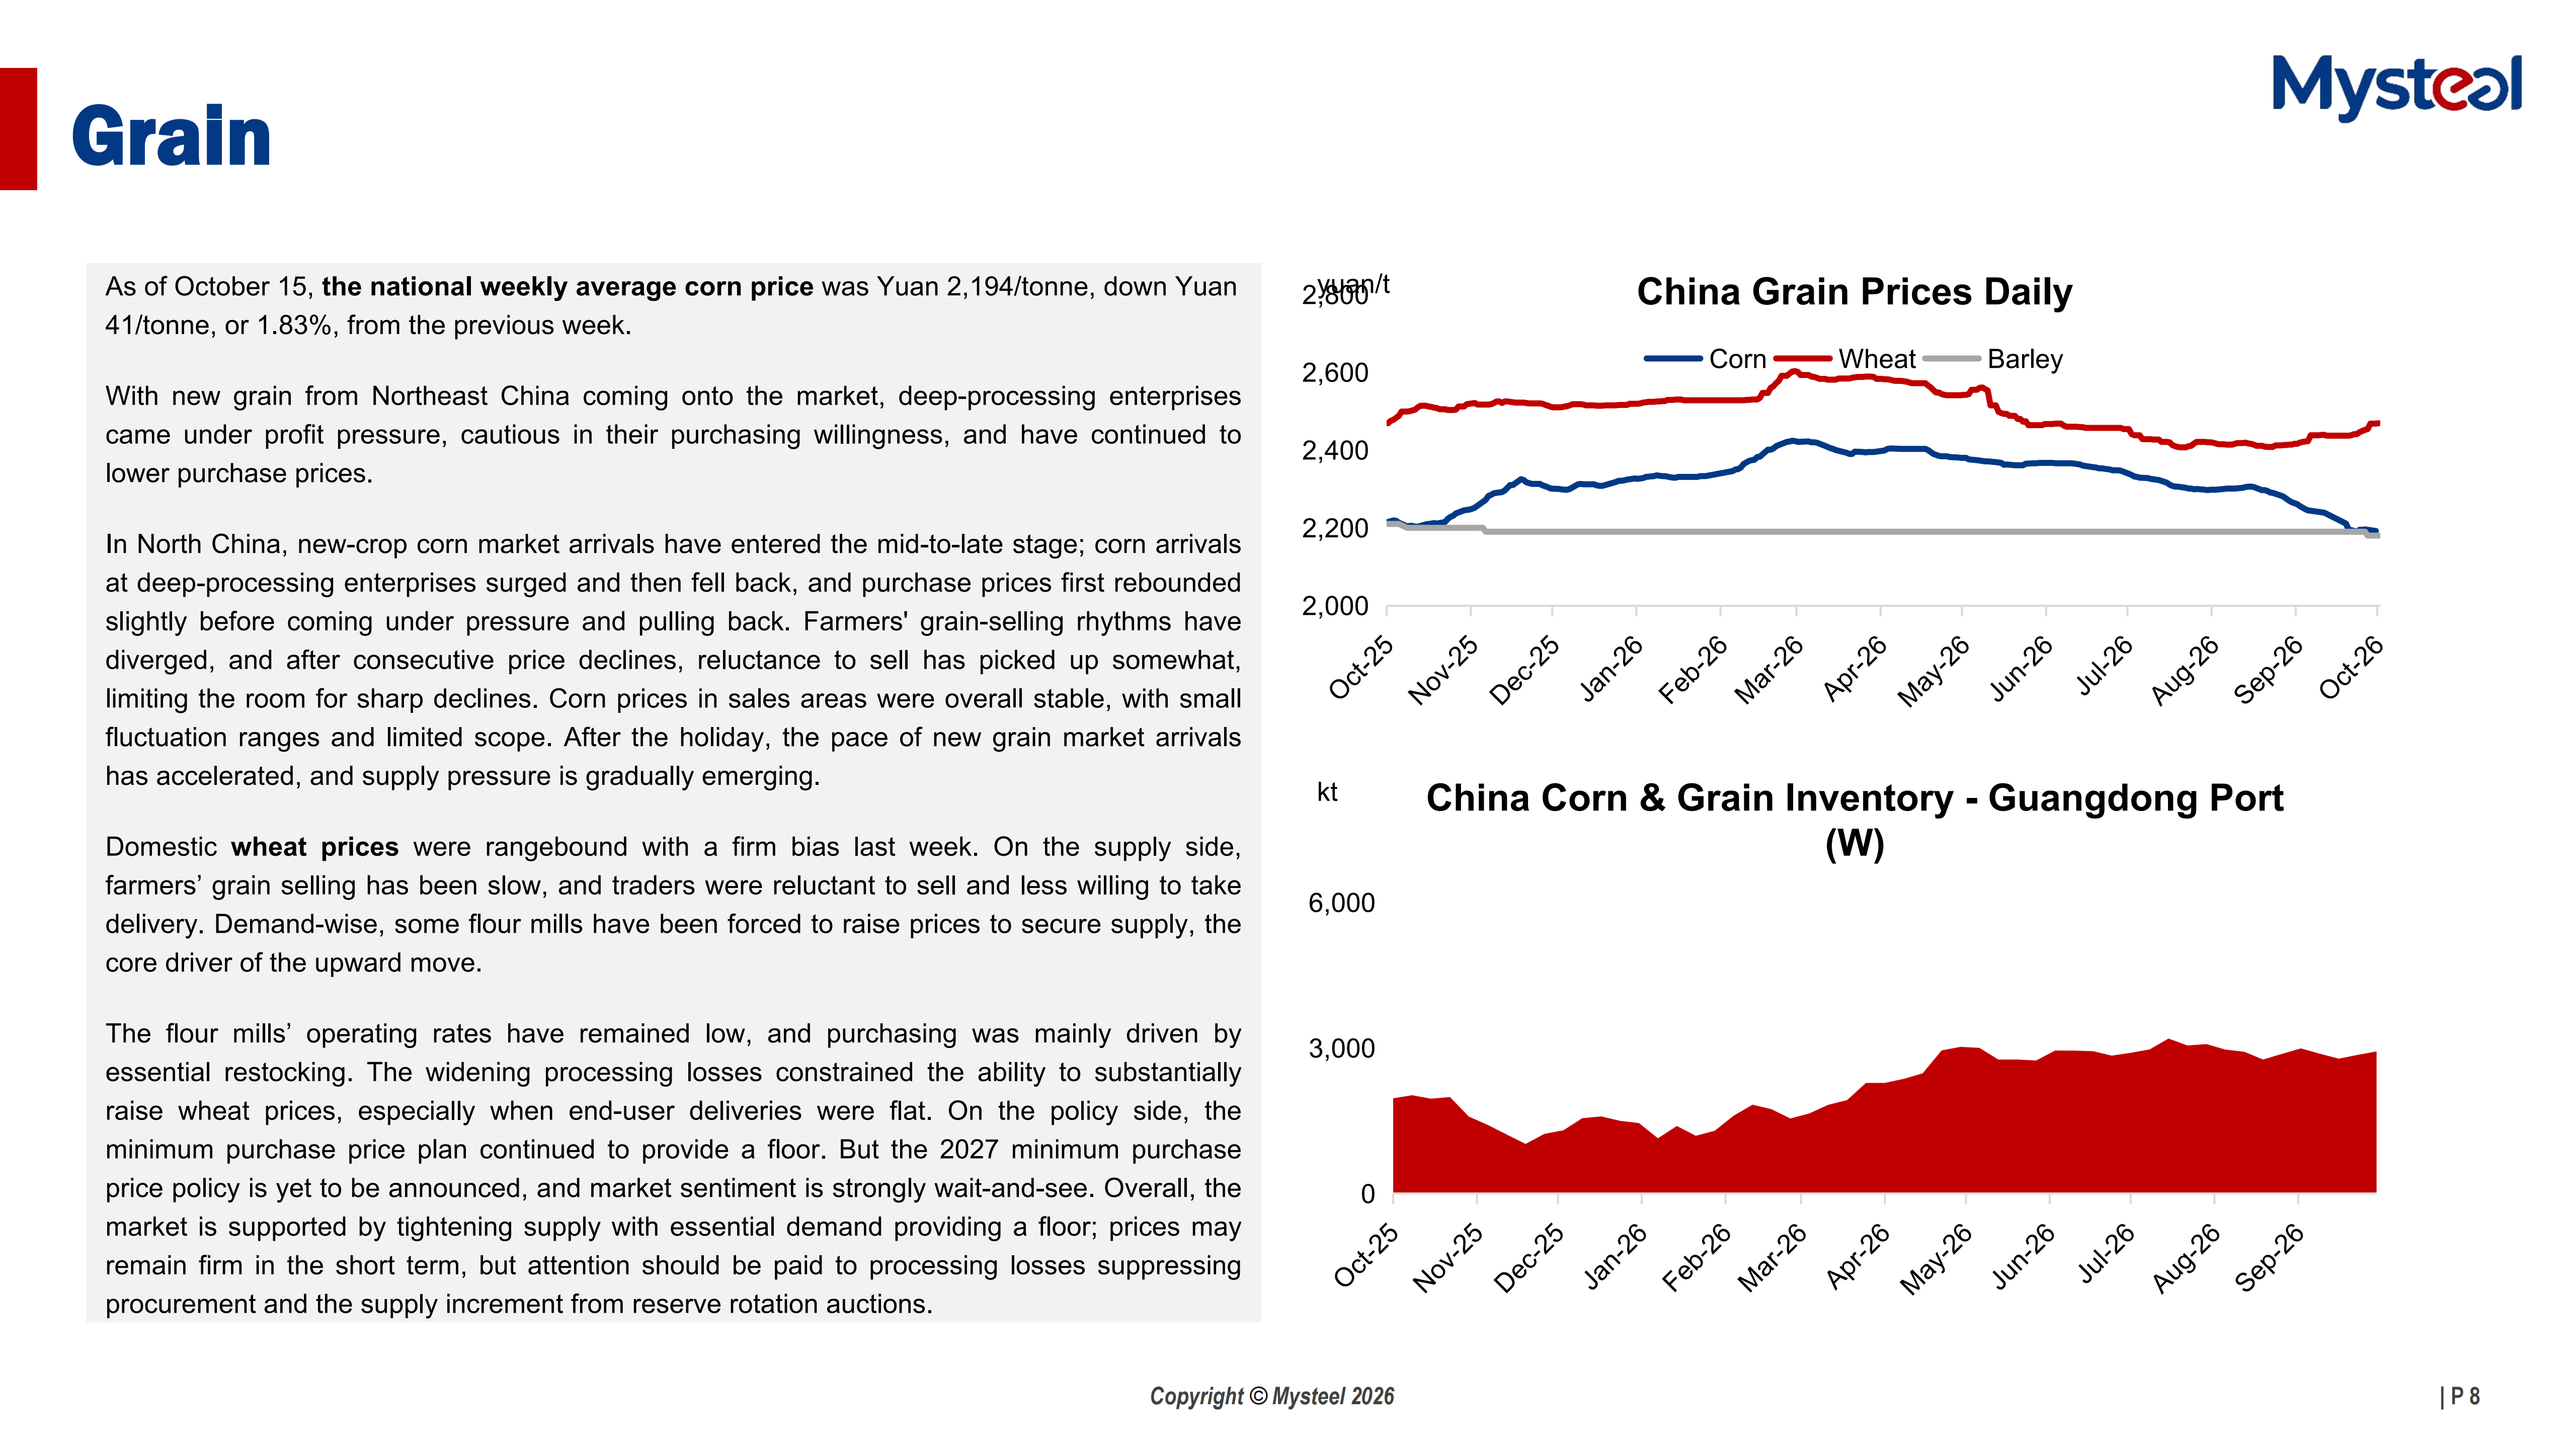
Grain: New-crop corn harvesting is largely complete, weighing on overall market supply, while downstream demand has remained sluggish, with enterprises sticking to essential-need purchases.
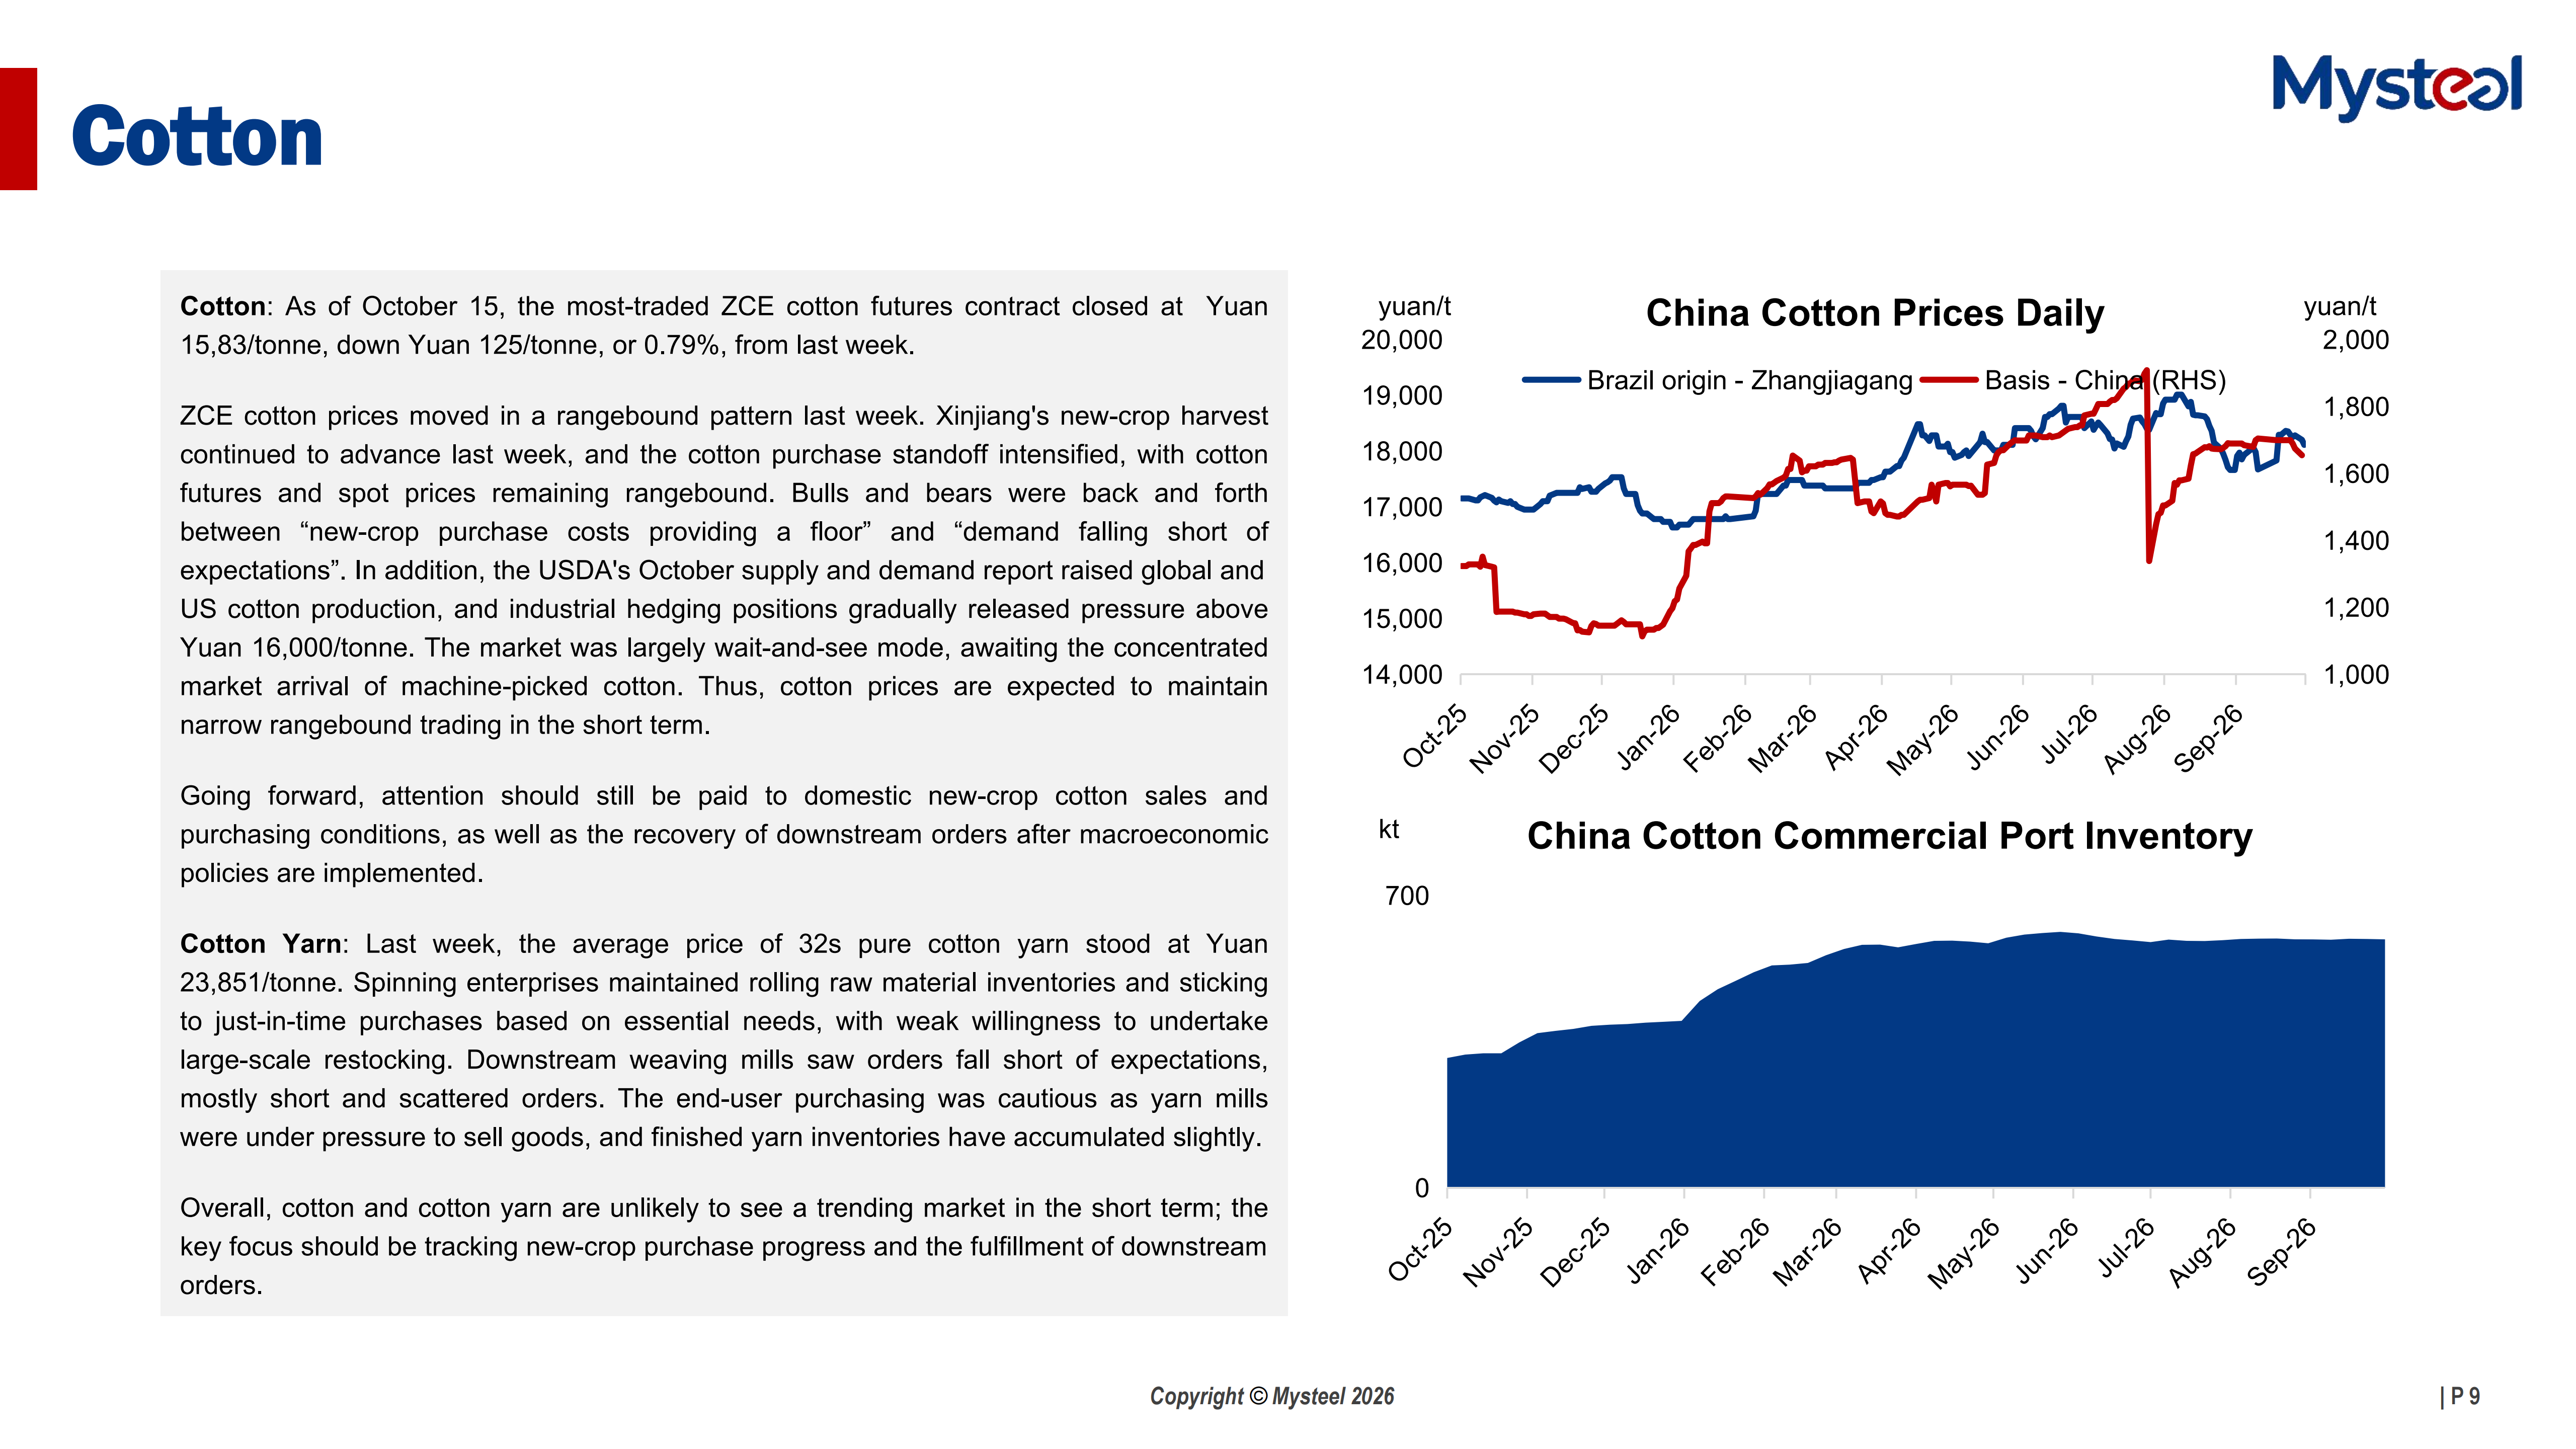
Cotton: The cotton harvest continues in Xinjiang, while the downstream purchase standoff intensified as bulls and bears battled between cost support and weak demand. The market now awaits machine-picked cotton marketing, with prices likely to keep narrow rangebound in the near term.