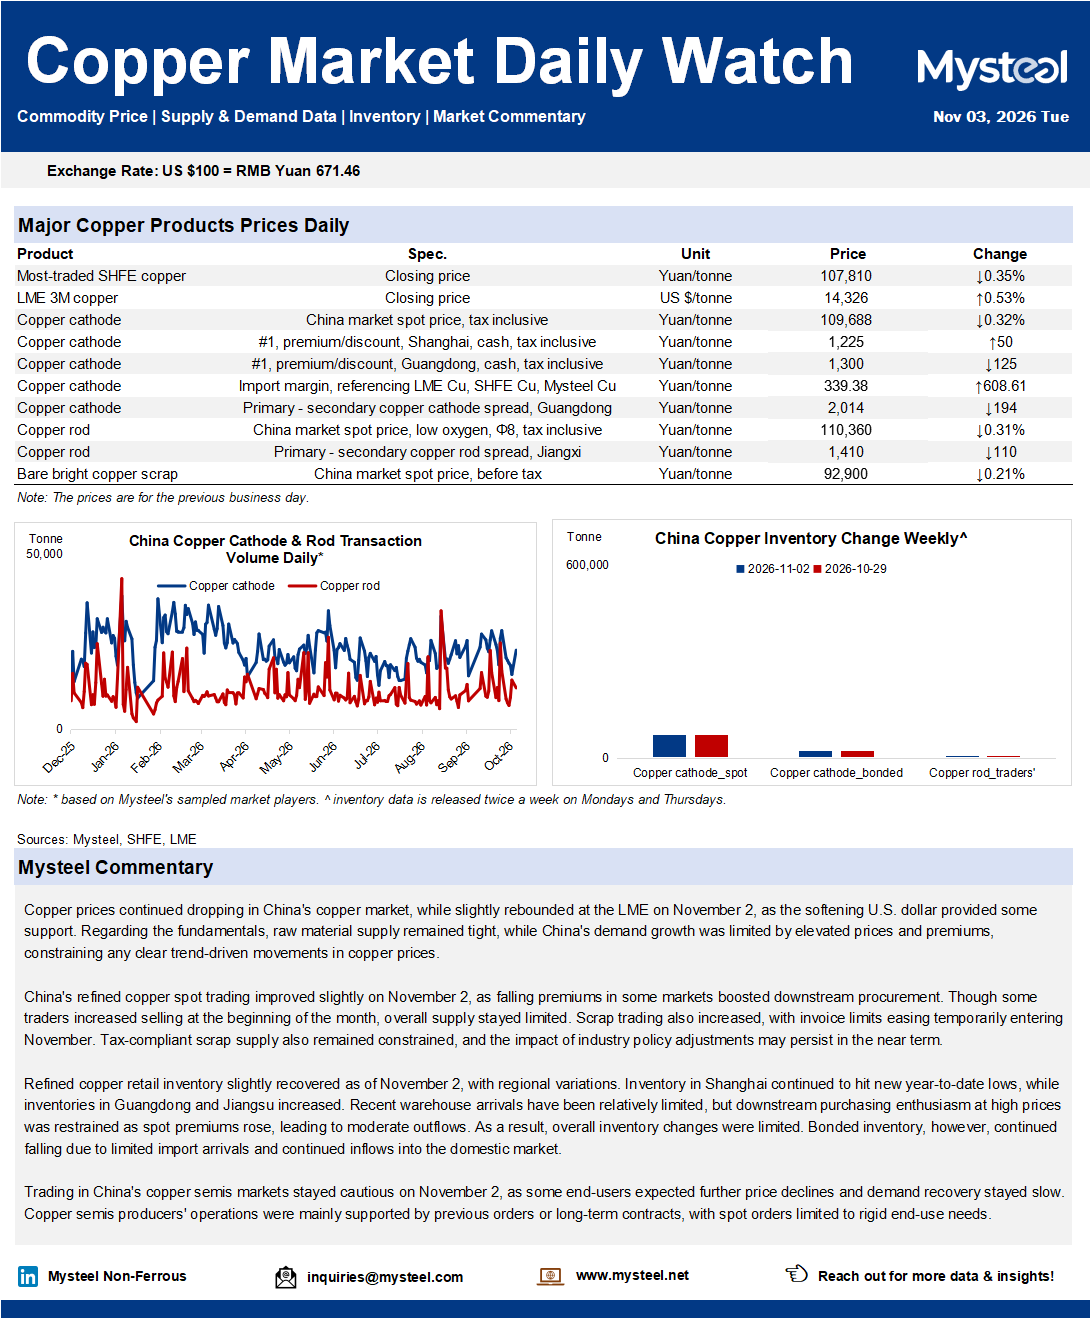
Copper prices continued dropping in China's copper market, while slightly rebounded at the LME on November 2, as the softening U.S. dollar provided some support. Regarding the fundamentals, raw material supply remained tight, while China's demand growth was limited by elevated prices and premiums, constraining any clear trend-driven movements in copper prices.
China's refined copper spot trading improved slightly on November 2, as falling premiums in some markets boosted downstream procurement. Though some traders increased selling at the beginning of the month, overall supply stayed limited. Scrap trading also increased, with invoice limits easing temporarily entering November. Tax-compliant scrap supply also remained constrained, and the impact of industry policy adjustments may persist in the near term.
Refined copper retail inventory slightly recovered as of November 2, with regional variations. Inventory in Shanghai continued to hit new year-to-date lows, while inventories in Guangdong and Jiangsu increased. Recent warehouse arrivals have been relatively limited, but downstream purchasing enthusiasm at high prices was restrained as spot premiums rose, leading to moderate outflows. As a result, overall inventory changes were limited. Bonded inventory, however, continued falling due to limited import arrivals and continued inflows into the domestic market.
Trading in China's copper semis markets stayed cautious on November 2, as some end-users expected further price declines and demand recovery stayed slow. Copper semis producers' operations were mainly supported by previous orders or long-term contracts, with spot orders limited to rigid end-use needs.