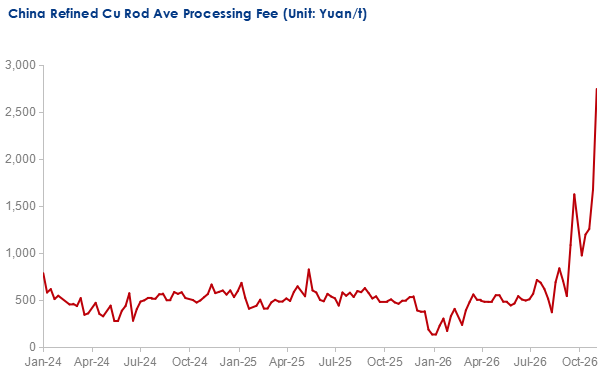
China's copper rod market faced mounting pressure from persistently elevated raw material costs, as record-high refined copper spot premiums have pushed up processing fees and reshaped downstream purchasing patterns. Since mid-October, spot premiums for refined copper in China have climbed steadily amid production cuts at domestic smelters, insufficient replenishment from imported copper and continuously declining domestic inventory. The resulting supply tightness drove premiums to unprecedented levels. Although Shanghai's spot premium for #1 refined copper retreated after peaking at Yuan 2,600/tonne on November 6, it remained relatively high this week. Against this backdrop, refined copper rod processing fees were also been forced upward, widening the price gap between spot and long-term orders and altering the market's transaction structure.
Source: Mysteel
According to Mysteel's survey, processing fees for refined copper rod have risen to Yuan 2,200-2,400/tonne in North China, Yuan 1,700-2,100/tonne in East China and Yuan 1,900-2,200/tonne in South China, all reaching record highs.
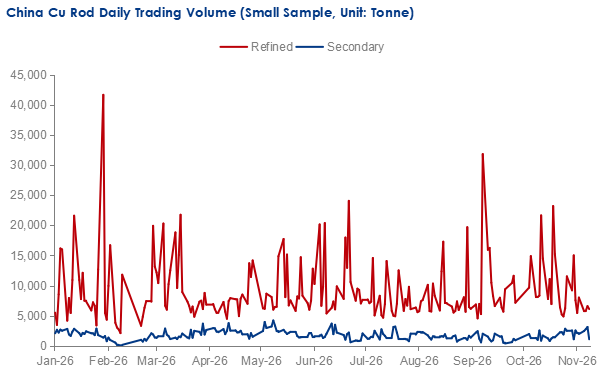
Market feedback indicated that elevated copper prices, spot premiums and processing fees significantly dampened buying sentiment in the refined copper rod market. Transactions increasingly centered on deliveries under long-term contracts, while spot orders became more difficult to conclude due to higher prices. Deliveries to long-term contract customers remained relatively stable, as their procurement arrangements were largely insulated from fluctuations in spot processing fees. By contrast, the higher costs associated with spot purchases made downstream buyers more reluctant to place spot orders. Only a limited number of buyers with rigid procurement requirements continued purchasing according to their usual schedules, leaving overall spot transaction volumes subdued.
In Northwest China, refined copper rod producers faced additional supply constraints, with finished product inventory remaining low. This was partly because upstream smelters diverted refined copper to Shanghai, where spot premiums were higher, reducing the availability of raw materials for local rod producers. As a result, some manufacturers were able to supply only customers under long-term contracts, while spot faced temporary supply interruptions.
Although elevated refined copper prices widened the price spread between refined and secondary copper rods, this did not translate into a significant recovery in demand for secondary copper rod. The main constraint remained the tight supply and high procurement costs of compliant copper scrap, following adjustments to tax invoicing policies in the domestic scrap market.
According to Mysteel's survey, raw material shortages left only a small proportion of secondary copper rod producers able to maintain continuous operations. Some manufacturers continued to face intermittent production suspensions due to disruptions in scrap copper procurement. Their order-taking capacity was therefore closely tied to raw material availability, with production and sales plans adjusted according to daily scrap copper arrivals. Consequently, overall transaction activity remained constrained despite the wider refined-secondary copper rod price spread.
Source: Mysteel
Overall, supply tightness and elevated procurement costs across both refined copper and copper scrap markets limited production and trading activity in China's copper rod sector, albeit through different channels. Refined copper rod producers became increasingly reliant on long-term contracts to secure stable business, while secondary copper rod manufacturers remained constrained by the availability of compliant scrap feedstock.
Looking ahead, China's refined copper spot inventory is likely to remain low in the short term. With futures contract rollover and refined copper annual long-term contract negotiations approaching, spot premiums are expected to fluctuate at elevated levels. This should keep spot processing fees for refined copper rod relatively firm, while transaction activity is likely to remain concentrated on long-term contract deliveries, with spot orders continuing to face resistance from high costs. For secondary copper rod producers, persistent shortages of compliant scrap copper scrap are expected to remain the key constraint on production and procurement. As a result, secondary copper rod transactions are also likely to remain limited in the near term, even if the wider price spread continues to offer a theoretical incentive for substitution.
Written by Mingyuan Wang, wangmingyuan@mysteel.com