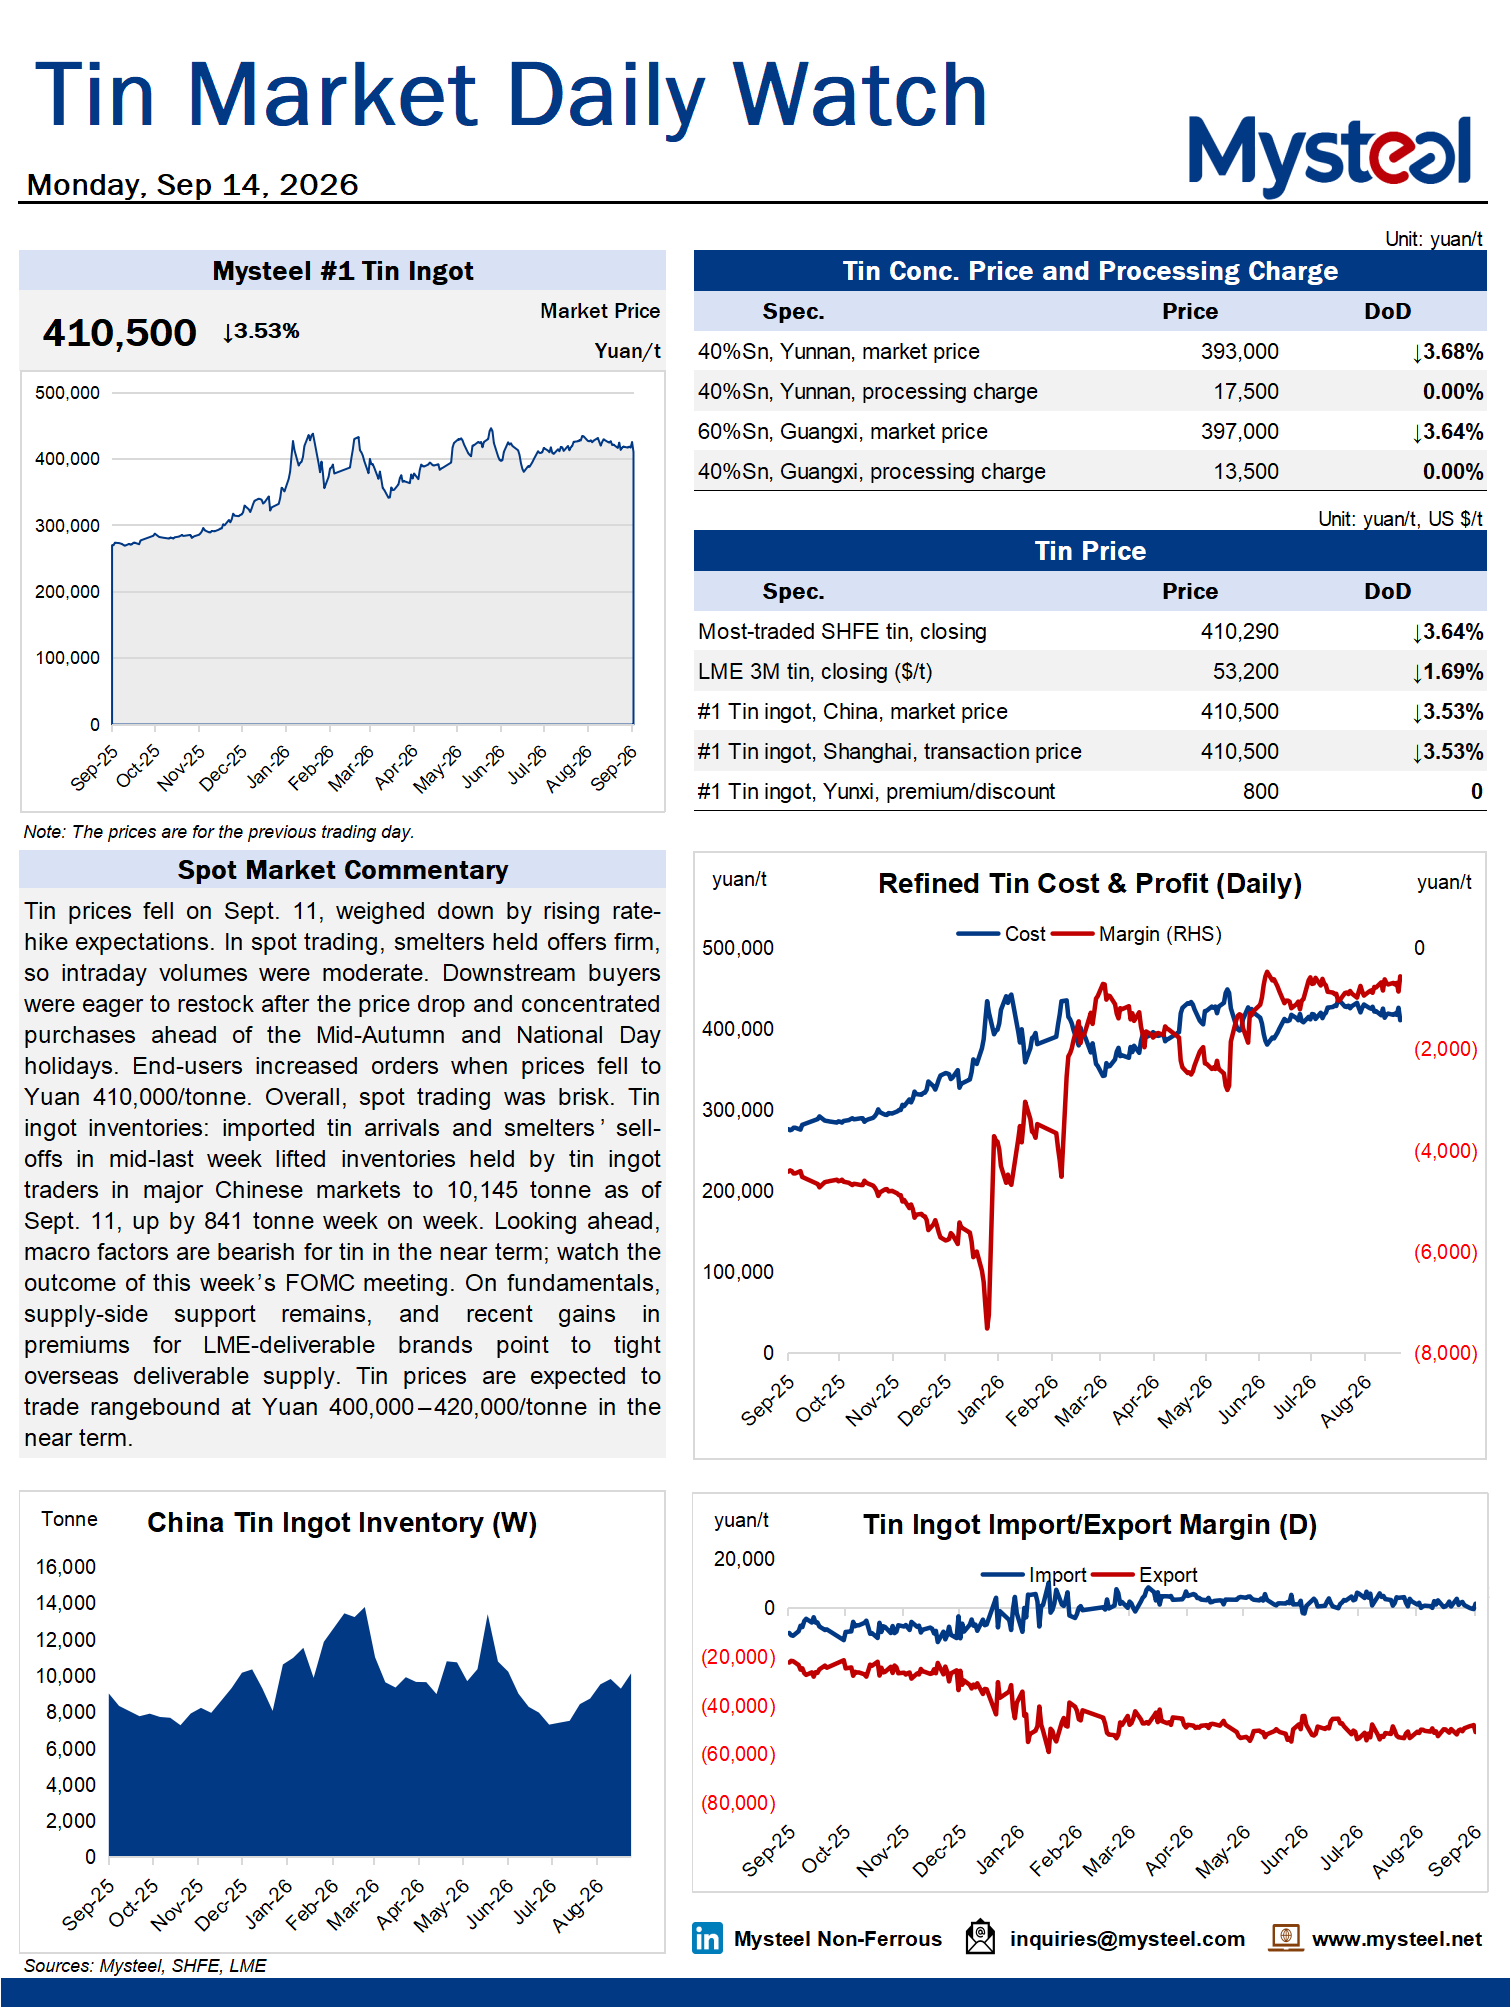
Tin prices fell on Sept. 11, weighed down by rising rate-hike expectations. In spot trading, smelters held offers firm, so intraday volumes were moderate. Downstream buyers were eager to restock after the price drop and concentrated purchases ahead of the Mid-Autumn and National Day holidays. End-users increased orders when prices fell to Yuan 410,000/tonne. Overall, spot trading was brisk. Tin ingot inventories: imported tin arrivals and smelters' sell-offs in mid-last week lifted inventories held by tin ingot traders in major Chinese markets to 10,145 tonne as of Sept. 11, up by 841 tonne week on week. Looking ahead, macro factors are bearish for tin in the near term; watch the outcome of this week's FOMC meeting. On fundamentals, supply-side support remains, and recent gains in premiums for LME-deliverable brands point to tight overseas deliverable supply. Tin prices are expected to trade rangebound at Yuan 400,000–420,000/tonne in the near term.