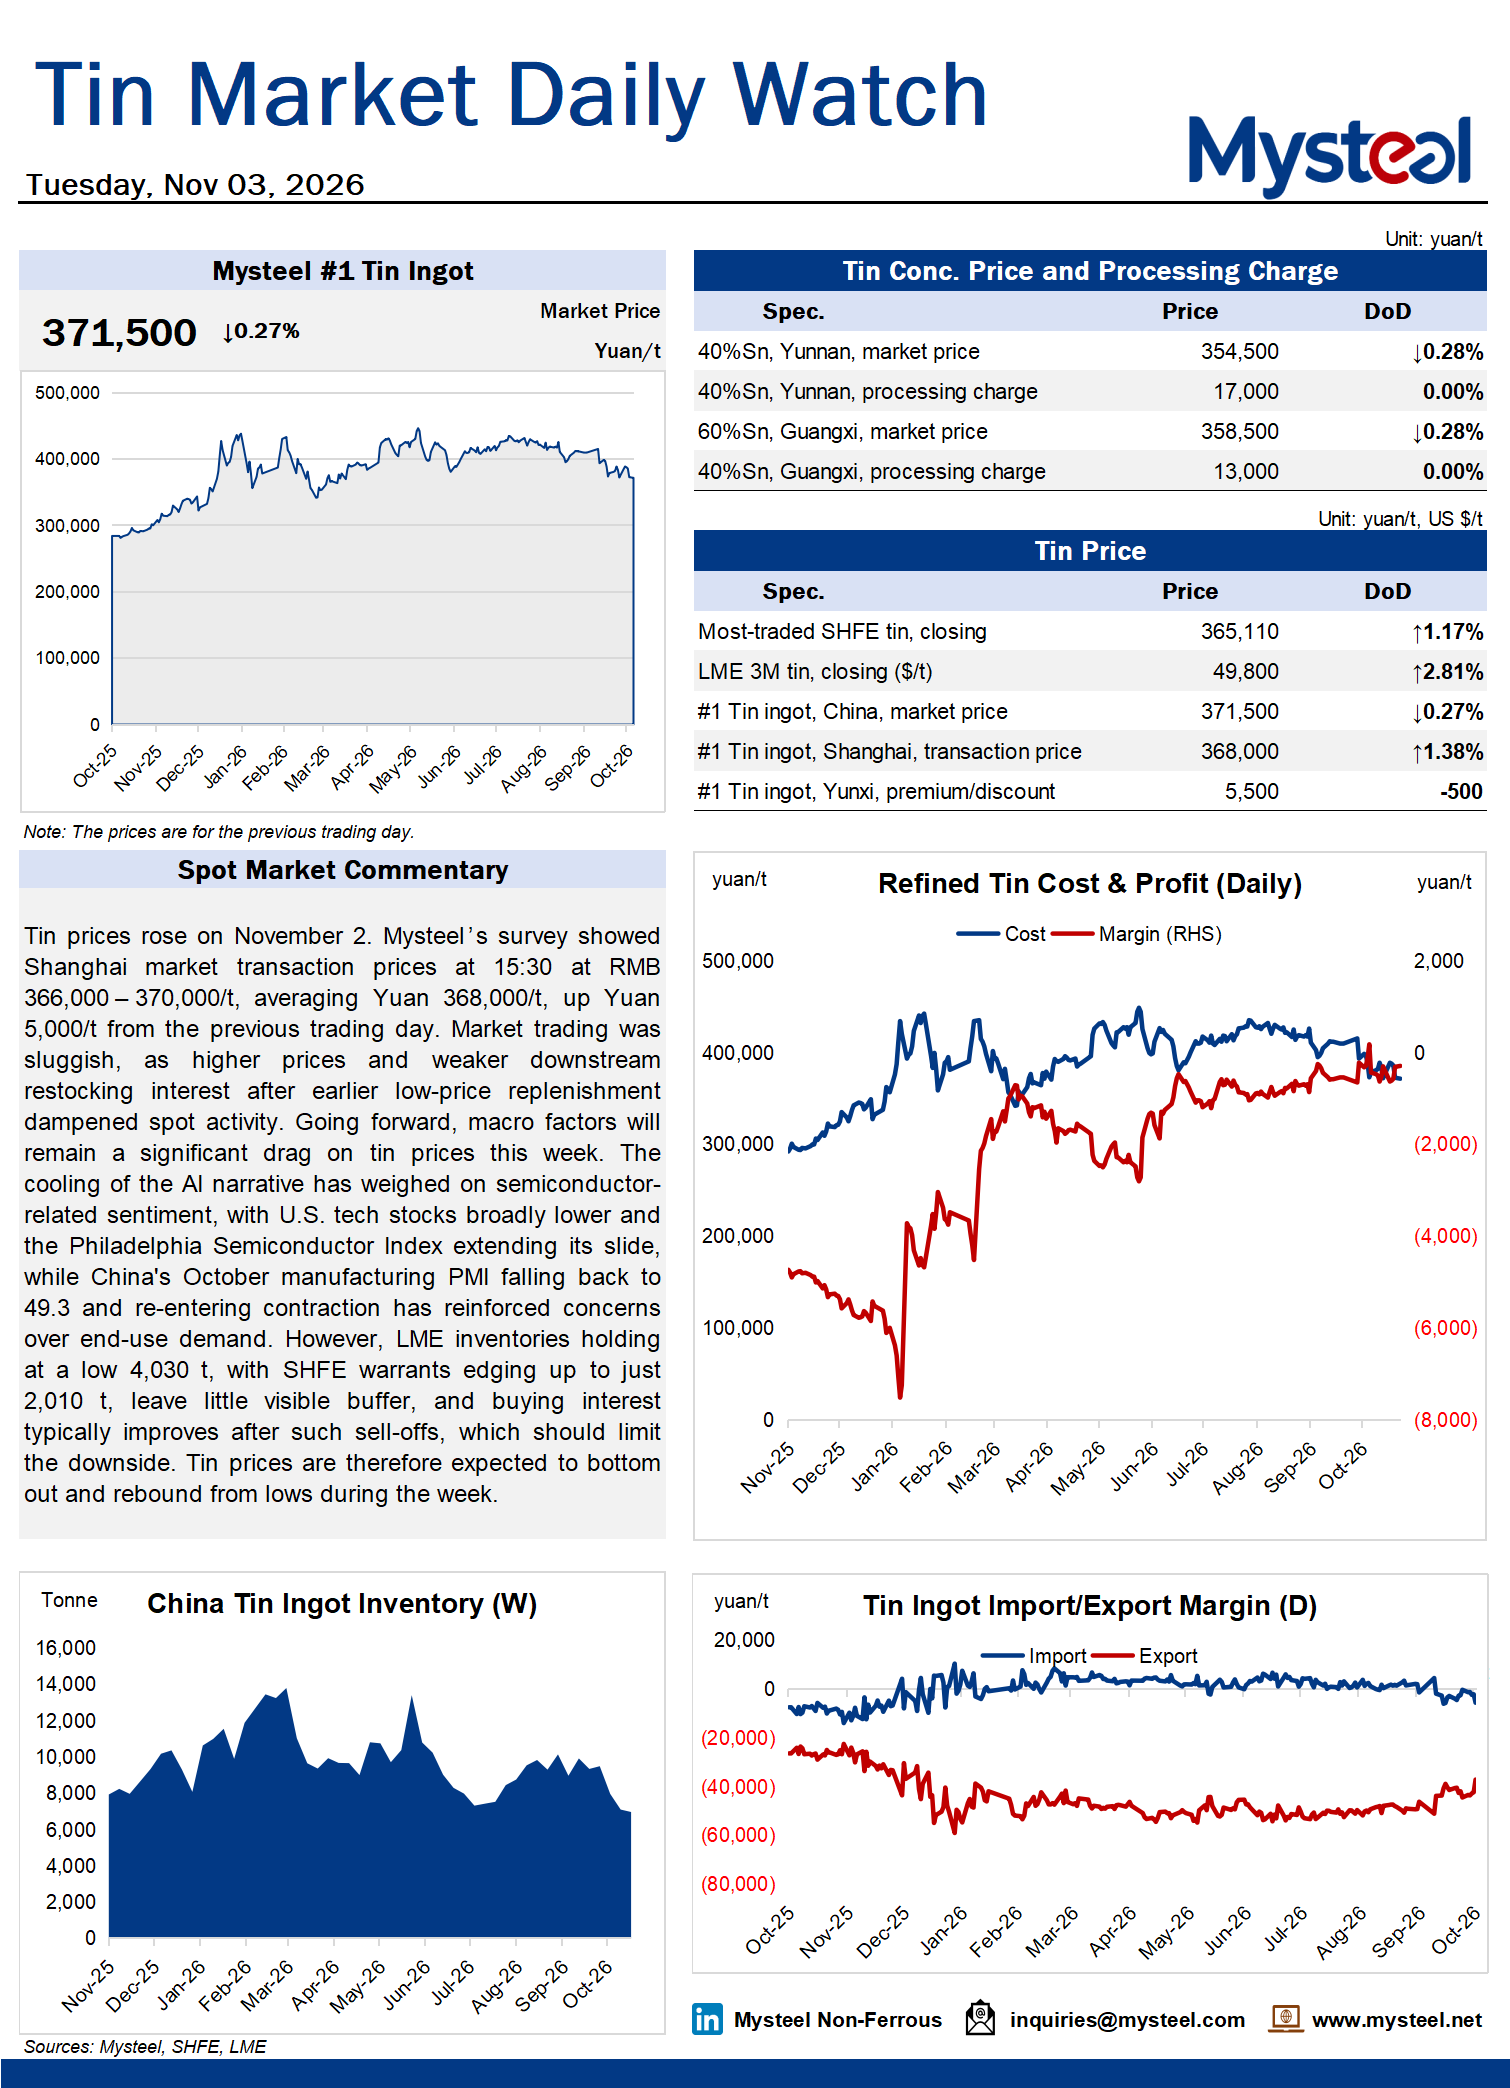
Tin prices rose on November 2. Mysteel's survey showed Shanghai market transaction prices at 15:30 at RMB 366,000–370,000/t, averaging Yuan 368,000/t, up Yuan 5,000/t from the previous trading day. Market trading was sluggish, as higher prices and weaker downstream restocking interest after earlier low-price replenishment dampened spot activity. Going forward, macro factors will remain a significant drag on tin prices this week. The cooling of the AI narrative has weighed on semiconductor-related sentiment, with U.S. tech stocks broadly lower and the Philadelphia Semiconductor Index extending its slide, while China's October manufacturing PMI falling back to 49.3 and re-entering contraction has reinforced concerns over end-use demand. However, LME inventories holding at a low 4,030 t, with SHFE warrants edging up to just 2,010 t, leave little visible buffer, and buying interest typically improves after such sell-offs, which should limit the downside. Tin prices are therefore expected to bottom out and rebound from lows during the week.