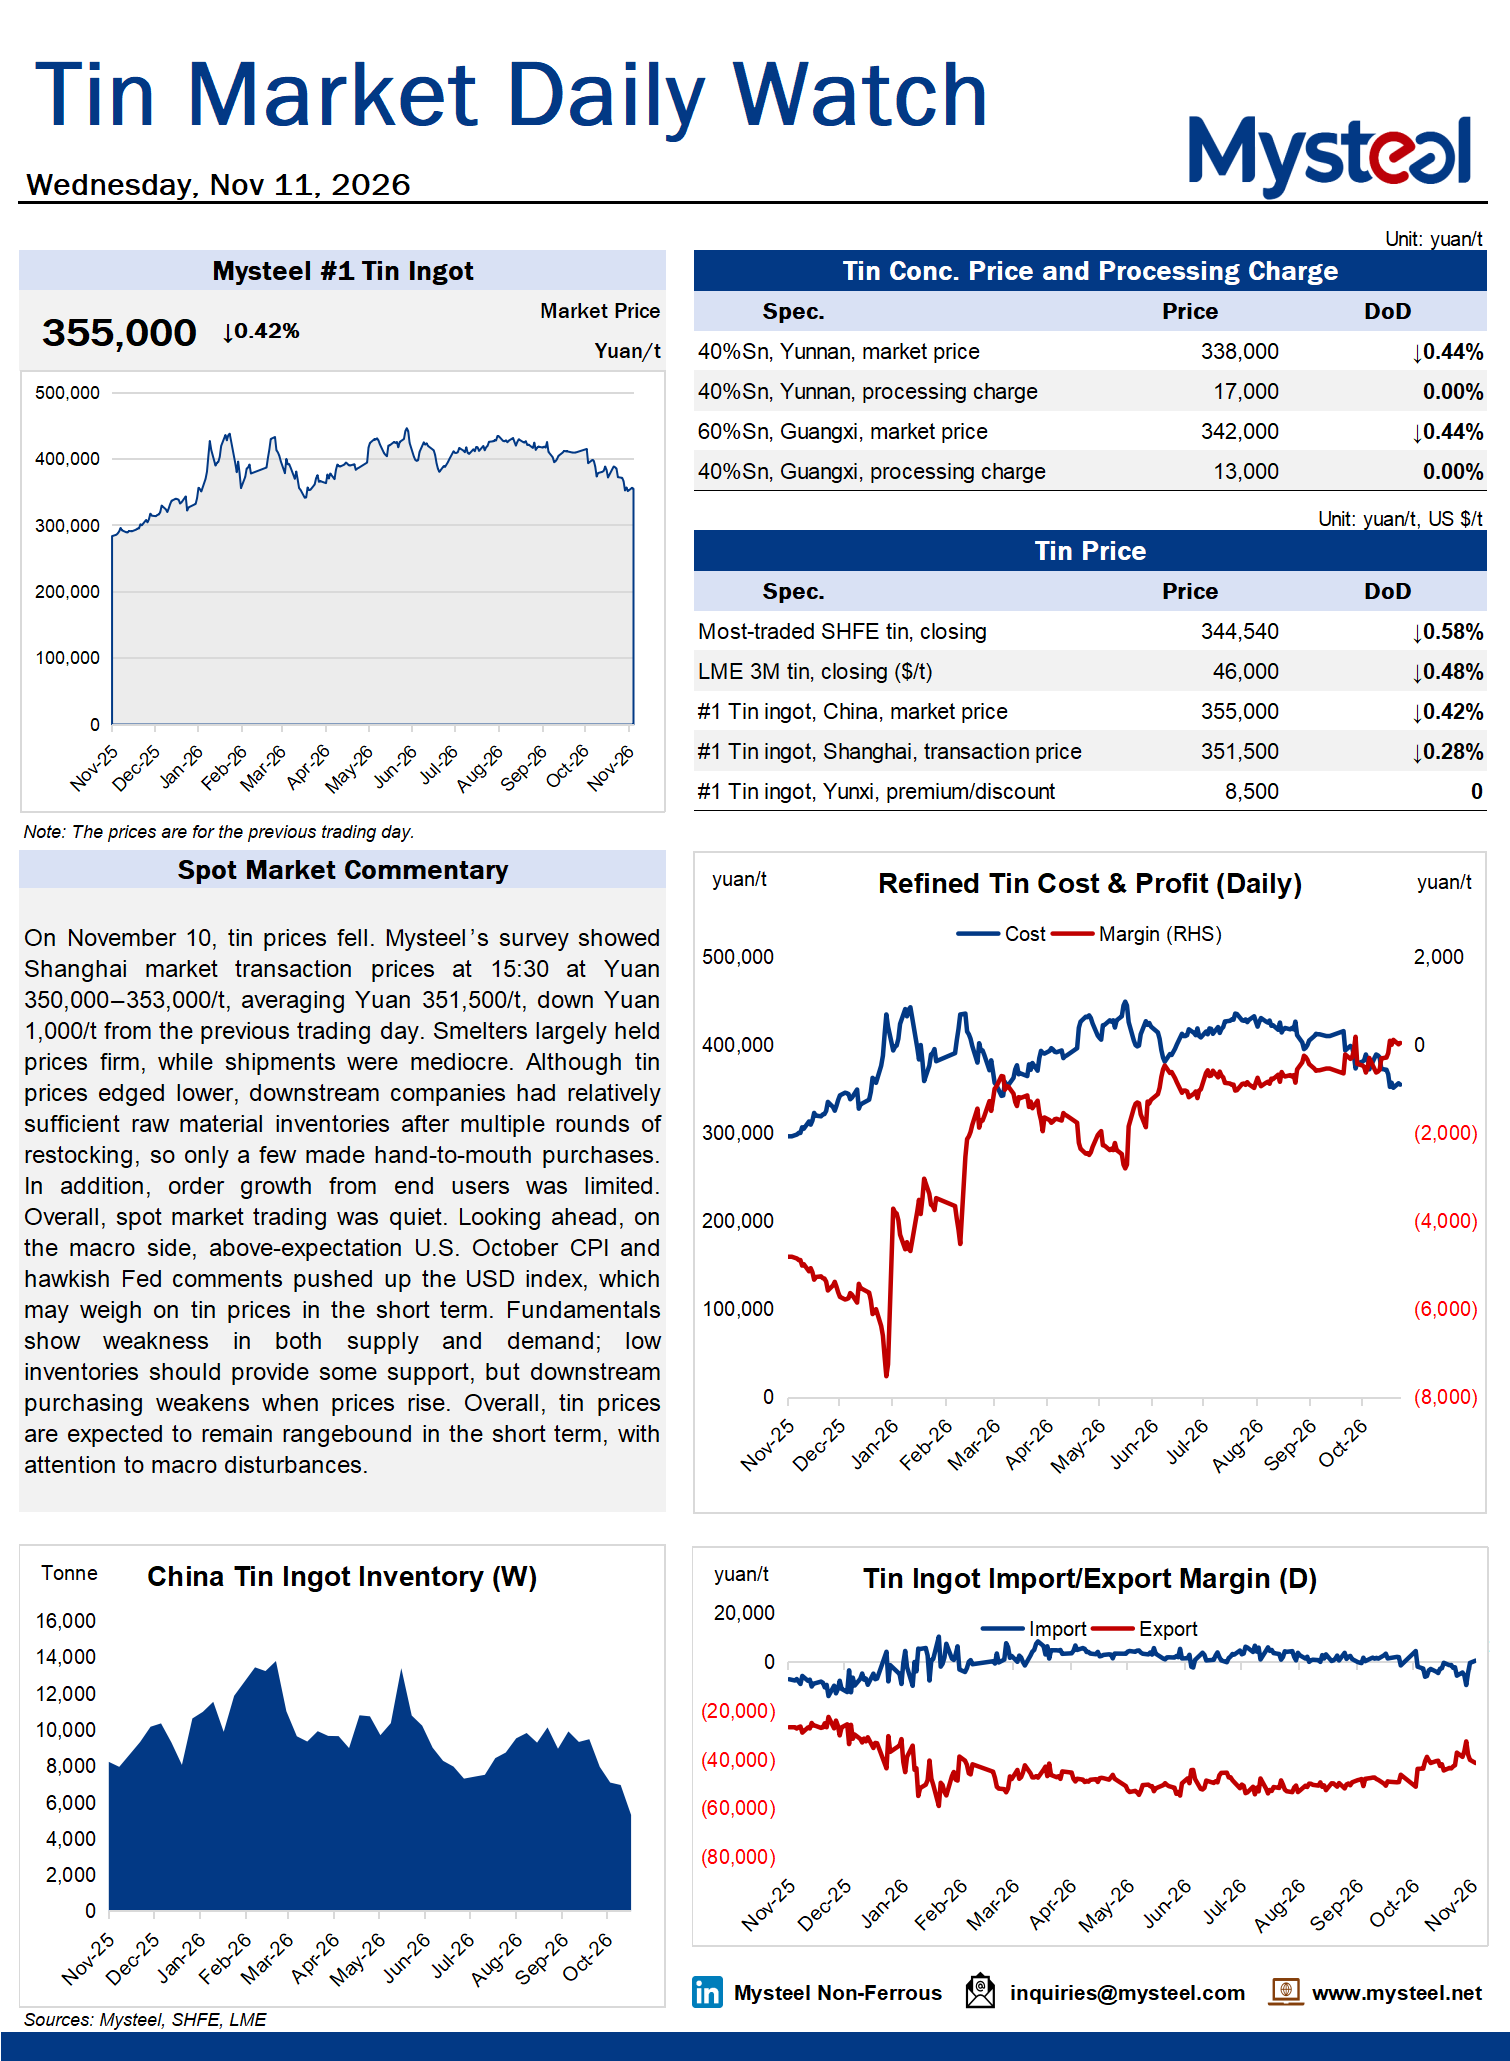
On November 10, tin prices fell. Mysteel's survey showed Shanghai market transaction prices at 15:30 at Yuan 350,000–353,000/t, averaging Yuan 351,500/t, down Yuan 1,000/t from the previous trading day. Smelters largely held prices firm, while shipments were mediocre. Although tin prices edged lower, downstream companies had relatively sufficient raw material inventories after multiple rounds of restocking, so only a few made hand-to-mouth purchases. In addition, order growth from end users was limited. Overall, spot market trading was quiet. Looking ahead, on the macro side, above-expectation U.S. October CPI and hawkish Fed comments pushed up the USD index, which may weigh on tin prices in the short term. Fundamentals show weakness in both supply and demand; low inventories should provide some support, but downstream purchasing weakens when prices rise. Overall, tin prices are expected to remain rangebound in the short term, with attention to macro disturbances.