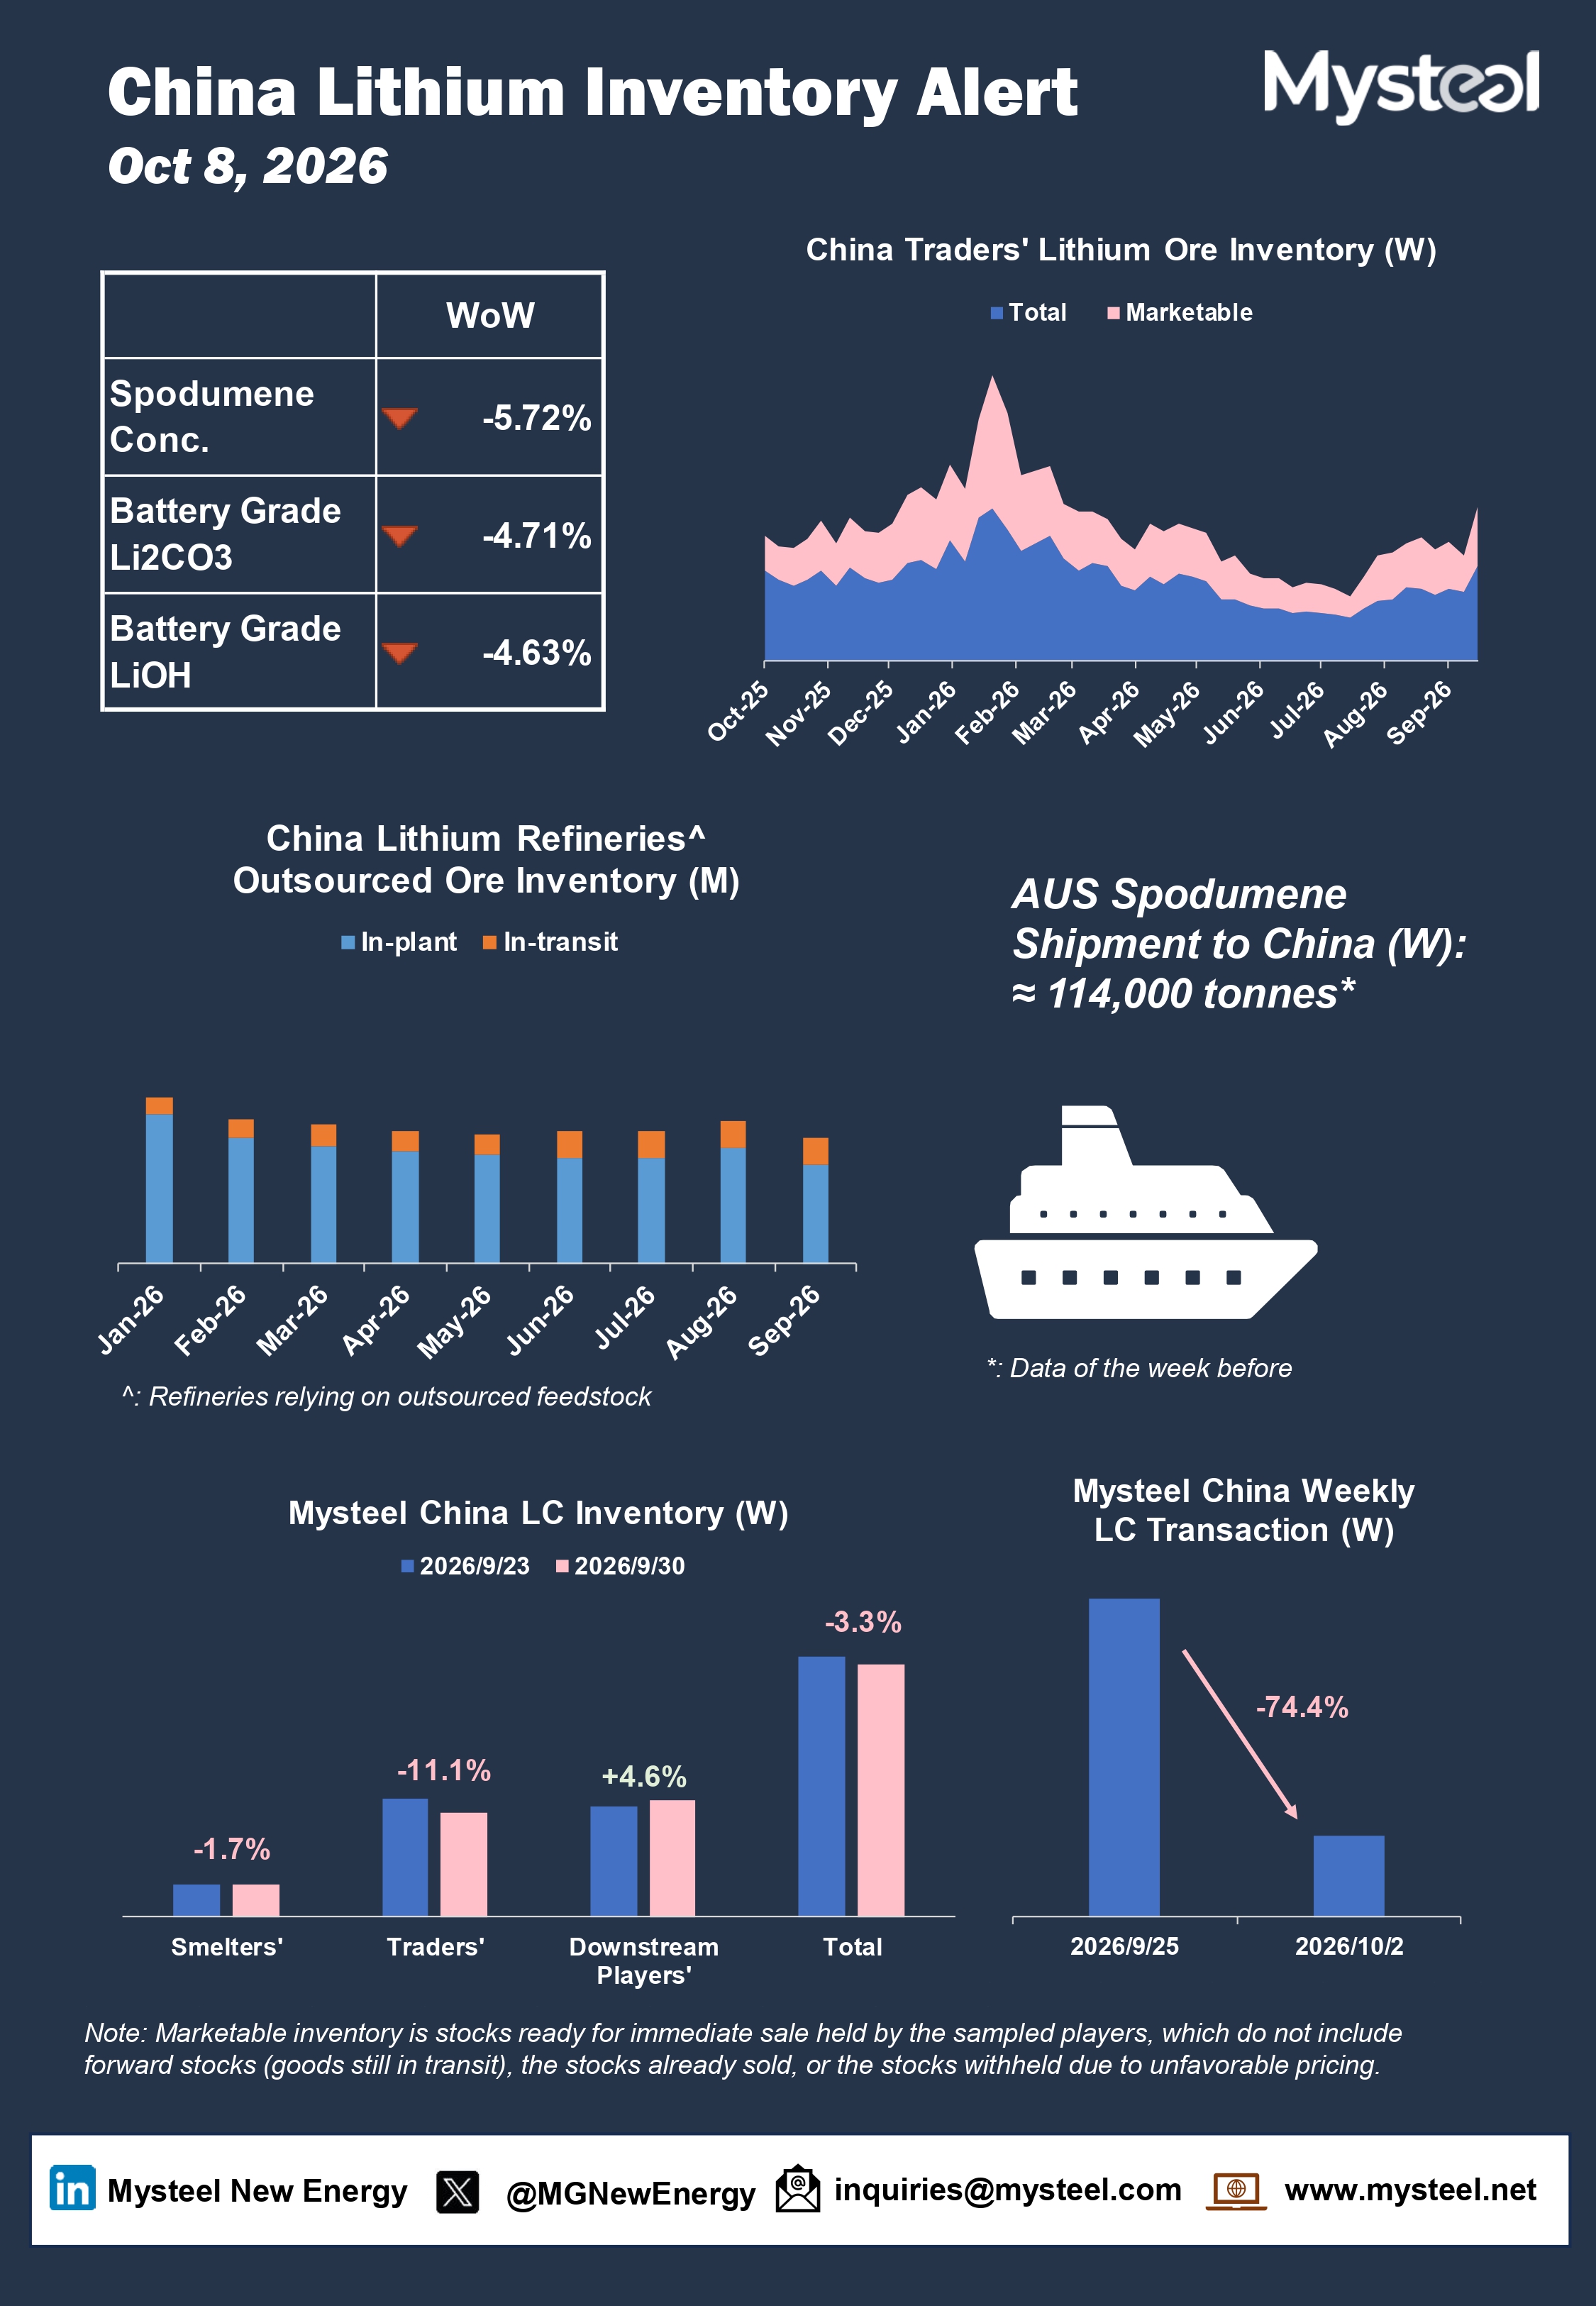
Lithium carbonate spot prices are near yearly lows. The lithium converters now favored long-term contracts, holding prices firm and shunning spot sales; traders, with low marketable stocks after pre-holiday destocking, remained on the sidelines.
In September, China's lithium carbonate production was 114,700 tonnes, up 7.7% MoM but below guidance, as feedstock tightness and weak prices curbed lepidolite-line ramping; spodumene output was flat. October schedules are 115,900 tonnes, up just 1.1%.
Demand has stayed strong. The September LFP output rose 4.78% MoM to 603,200 tonnes, with October seen at 625,000 tonnes (+3.61%) as capacity ramps in Sichuan, Inner Mongolia, and Hubei, though some firms slow on debugging, feedstock, and margin pressure. Ternary remains squeezed by LFP.
Ore tightness has eased somewhat from Q2, but the picture is little changed.
October remains peak season, with high LFP schedules and rush exports front-loading demand. With demand growth outpacing supply, the monthly supply-demand deficit may widen to about 29,000 tonnes, keeping visible inventories drawing down. Destocking support and supply growth expectations offset each other, pointing to range-bound prices near term.