Premium: Early-week copper rally prompts sellers to cut spot premiums to secure deals
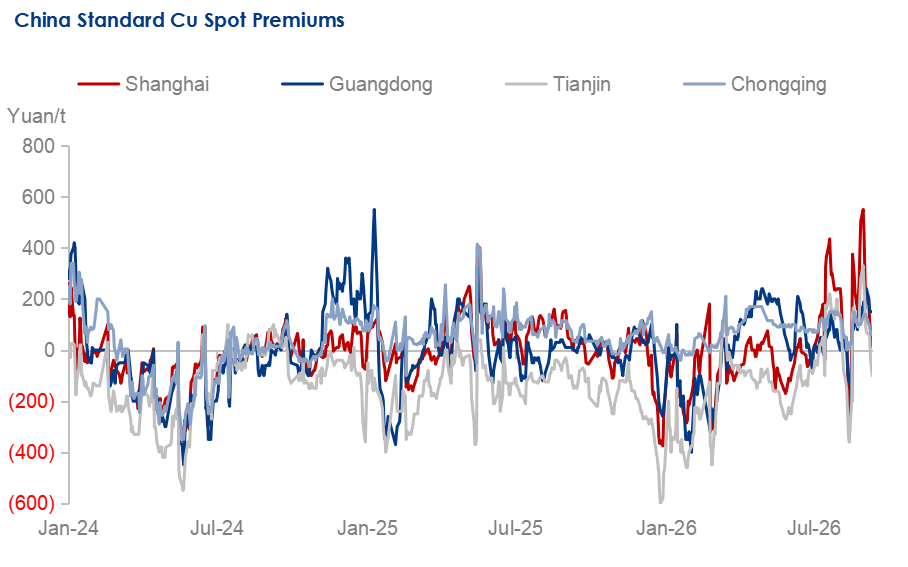
Early last week, China's refined copper prices rose and the SHFE near-month backwardation remained wide, making downstream buyers cautious and limiting raw material purchases to immediate needs. As a result, some holders lowered refined copper spot premiums to stimulate trades. However, low market arrivals and stronger downstream consumption after the price pullback kept refined copper retail inventory in China declining, supporting spot premiums in most major markets.
Looking ahead, macro factors are expected to weigh on copper prices in the short term, leaving room for downstream consumption to improve. With the 2609 contract due for delivery this week, refined copper spot premiums may rebound in China. According to Mysteel, refined copper spot premium ranges are forecast with Guangdong at Yuan 100/tonne to Yuan 400/tonne, Tianjin at -Yuan 200/tonne to Yuan 200/tonne, and Chongqing at -Yuan 150/tonne to Yuan 200/tonne this week.
Data Source: Mysteel
Supply: Spot supply diverges across markets while remains tight overall
China's refined copper spot supply diverged across markets last week but was generally tight. In Shanghai, as port operations largely returned to normal, some previously delayed imported copper cargoes cleared customs and entered the market. Several smelters also increased deliveries, easing regional spot supply somewhat. By contrast, Guangdong's supply remained tight, mainly because leading regional smelters continued to prioritize exports, limiting refined copper shipped to the domestic market. Meanwhile, supply in Tianjin was still affected by maintenance at a major smelter, and some refined copper was diverted to regions with higher spot premiums, keeping local supply tight. Smelter arrivals in Chongqing were also limited last week. Looking ahead, domestic smelter deliveries are expected to stay low, and with the export window open, refined copper exports will further divert supply from the domestic spot market. Tight market arrivals and supply are therefore likely to persist in the near term.
Demand: Refined copper spot trading rises WoW
China's refined copper spot trading was noticeably affected by copper price volatility last week. Early in the week, when prices rose, downstream buyers were cautious and purchased only for immediate needs. But a sharp price decline late in the week boosted spot market sentiment, driving up order volumes and raw material procurement demand. With some enterprises also stockpiling ahead of the Mid-Autumn Festival and National Day, weekly refined copper spot trading volume rose week on week. According to Mysteel's survey of 56 Chinese refined copper trading enterprises (including smelters, traders, and downstream processors), the weekly transaction volume between September 7 and September 11 increased by 7.61% or 7,586 tonnes compared with the previous week, reaching 107,262 tonnes. Looking ahead, macro disturbances are expected to weigh on copper prices in the near term, likely pushing the price center lower and encouraging downstream purchasing. Meanwhile, before the Mid-Autumn and National Day holidays, stockpiling demand is also expected to emerge if prices are at suitable levels. In summary, China's refined copper spot trading volume is expected to have further room to rise in the near term.
Import: Import arbitrage improves but foreign trade activity remains limited
Early last week, China's refined copper import ratio remained weak, and import trade stayed at a loss. Although last Friday's copper price decline improved import ratio and turned trade profitable, imported copper availability in the foreign trade market was relatively limited. Holders therefore kept firm offers, while Shanghai Yangshan refined copper warrant and bill-of-lading premiums also rose, limiting the improvement in market activity. Looking ahead, macro factors are expected to remain notably bearish in the near term, while overseas copper premiums may narrow. China's refined copper import profit and foreign trade market activity could therefore improve.
Inventory: China's refined copper retail and bonded inventory both decline WoW
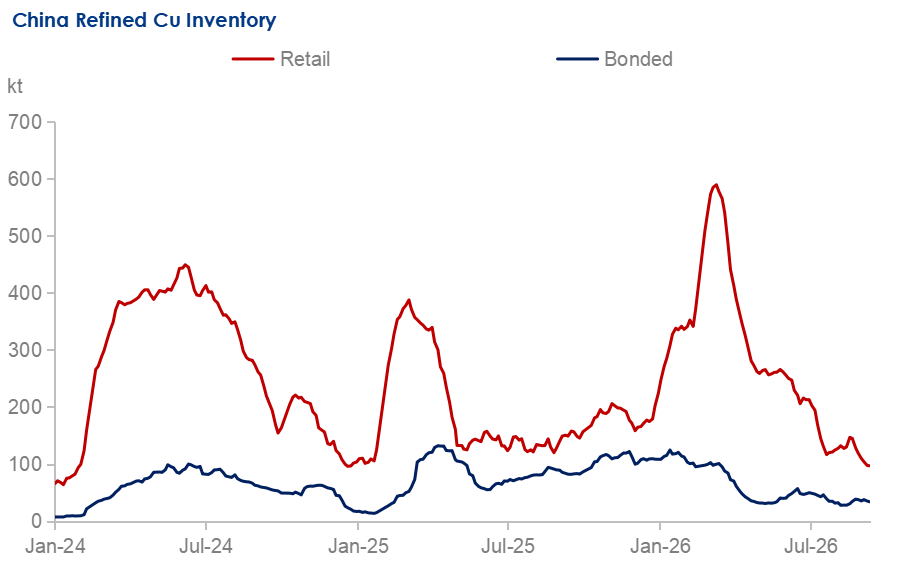
China's refined copper retail inventory fell week on week last week. Imported copper inflows increased in some markets as port congestion eased, and downstream purchasing early last week was constrained by high prices. Still, with domestic cargo arrivals remaining low, China's refined copper retail inventory continued to trend downward. Looking ahead, macro disturbances are expected to push the copper price center lower in the near term, while some enterprises may stockpile ahead of the Mid-Autumn Festival and National Day. Meanwhile, refined copper arrivals are expected to remain limited in the near term, so China's refined copper retail inventory may continue to decline.
China's refined copper bonded inventory declined week on week last week. As cargoes from some bonded warehouses continued to be exported overseas, bonded zone inventory still fell week on week even as planned export cargoes from domestic smelters arrived gradually. Looking ahead, with domestic smelter deliveries and warehouse cargo exports offsetting each other, China's refined copper bonded inventory is expected to change only slightly in the near term.
Data Source: Mysteel
The weekly average spread between the main COMEX and LME copper contracts was down by $67.59/tonne week on week to $289.84/tonne last week. The average LME cash-3M copper contract settlement spread was $37.7/tonne last week, down by $61.93/tonne week on week. As the COMEX-LME refined copper spread narrowed, COMEX refined copper inventory growth slowed and some refined copper even flowed out, while LME refined copper inventory gains last week were mainly driven by inflows into Kaohsiung and Hong Kong warehouses. Looking ahead, as expectations of additional U.S. tariffs on refined copper ease, the COMEX copper premium may narrow, so the flow of cargoes into North America is expected to slow and may even reverse, with material likely starting flowing back from North America to other markets.
More regular analysis and comprehensive data on China's copper industry are available in Mysteel Copper Weekly, Mysteel Copper Monthly, and Mysteel Copper Database. Reach out to us via Mysteel's official website: Latest & Reliable Copper Market Price in China | Mysteel, and follow Mysteel Non-Ferrous for more insights!
Written by Zhaorui Cui, cuizhaorui@mysteel.com
Edited by Mingyuan Wang, wangmingyuan@mysteel.com