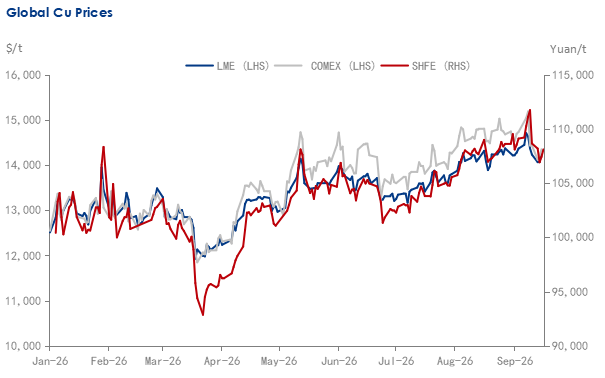
Copper prices saw a sharp decline after surging to record highs last week as expectations surrounding potential U.S. tariffs on refined copper cooled, and the decrease extended into the beginning of this week. Nevertheless, the latest pullback appeared to be more of a short-lived correction following the previous rally caused by macro disruptions than a fundamental reversal, and copper prices regained the uptrend later this week, despite the Federal Reserve's decision to raise interest rates and hawkish stance going forward.
According to Reuters on September 10, 2026, the White House had not yet made a final decision on tariffs on refined copper, with officials weighing the short-term negative impact of higher tariffs on manufacturing costs. In addition, with the government facing pressure to contain domestic inflation ahead of the midterm elections, expectations for the immediate implementation of copper tariffs cooled rapidly. Meanwhile, the accumulation of copper inventories in the U.S. has also started to weigh on prices. These developments prompted a rapid unwinding of the tariff-related risk premium accumulated during the previous rally, leading to a sharp correction in copper prices on September 11. However, the fading of this risk premium does not necessarily signal a deterioration in the underlying copper market.
In China, tight copper concentrate supply increasingly constrained refined copper production, while limited import flows and elevated exports further restricted domestic availability. At the same time, lower copper prices stimulated downstream buying, with the upcoming demand peak season and pre-holiday restocking providing additional support. Consequently, the strong fundamentals and the market having already priced in the Federal Reserve's rate hike together supporting price rebounds.
Source: COMEX, LME, SHFE
Intensifying raw material shortage constrains refined copper production
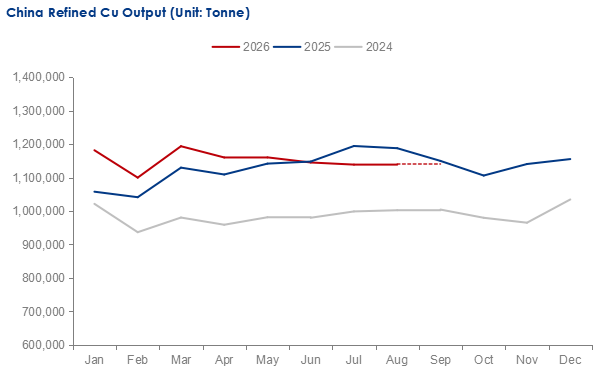
According to Mysteel's survey, China's refined copper output has been declining year on year since the third quarter began. The main reasons are tightening copper concentrate supplies and a widening supply gap for compliant copper scrap carrying valid input invoices. Based on survey data, Chinese smelters' refined copper output affected by raw material shortages and declining feed grades amounted to around 33,000 tonnes in August and is expected to reach approximately 35,000 tonnes in September. The impact of raw material constraints on output has even exceeded that of maintenance-related disruptions.
Source: Mysteel
Looking ahead, copper concentrate supply is unlikely to see any significant improvement in the short term, meaning the impact of raw material shortages on refined copper production is likely to intensify. Meanwhile, sulfuric acid prices have recently continued to decline amid weak demand and insufficient cost support, reducing the contribution of sulfuric acid sales to smelter profitability and potentially further weakening production incentives. The copper scrap market is also facing persistent supply constraints. The policy framework surrounding reverse invoicing remains under adjustment, while the limited availability and high prices of compliant scrap with valid invoices are restricting smelters' ability to replenish secondary copper feedstock. This is further exacerbating the overall shortage of raw materials.
As a result, China's refined copper production is likely to remain subject to rigid raw material constraints in the near term, leaving limited room for a meaningful recovery in smelter output. In addition, smelters are expected to enter another peak maintenance period in October, providing an additional drag on production. Although the fourth quarter has traditionally been a period when Chinese copper smelters increase production to meet annual targets, the relatively high copper prices this year have reduced incentives among many smelters to aggressively raise output. Refined copper production is therefore likely to remain on a declining trend in September and October, tightening China's domestic supply and providing fundamental support for copper prices.
Limited imports unlikely to notably supplement China's copper supply
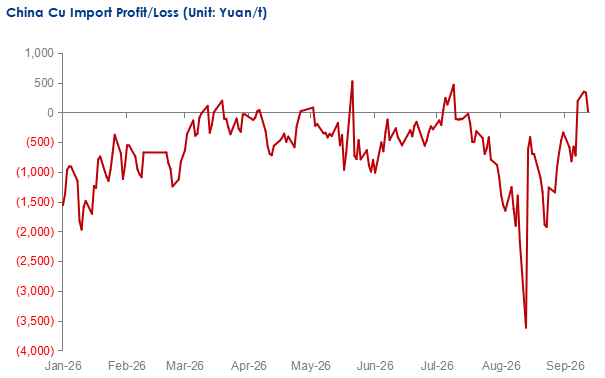
China's refined copper imports are unlikely to provide significant additional supply in the short term. Although expectations for U.S. copper tariffs have cooled and the COMEX-LME arbitrage spread has narrowed to around $200/tonne, the Yangshan copper premium has remained elevated at above $100/tonne recently. Import arbitrage margins have also remained negative for most of the time, limiting the incentive to bring additional refined copper into China. In addition, geopolitical and weather-related factors have increased uncertainty over vessel arrivals, while some cargoes have also been redirected to overseas markets. Meanwhile, refined copper inventory in China's bonded warehouses remain at relatively low levels. Overall, refined copper inflows into China are unlikely to increase significantly in the short term and are therefore unlikely to provide an effective supplement to domestic supply.
Source: Mysteel
On the export side, Mysteel's survey indicates that China's refined copper exports are expected to reach around 60,000 tonnes in September. This is mainly because the export window has been open previously, prompting some domestic smelters to lock in favorable arbitrage margins and arrange export shipments. More importantly, before the September 15 futures contract rollover, the spread between the back-month contracts widened to Yuan 500-800/tonne, encouraging some smelters to deliver refined copper into domestic warehouses to capture the arbitrage. As a result, a substantial portion of the planned September exports is expected to be concentrated in the second half of the month, further reducing refined copper availability in the domestic spot market.
Resilient rigid demand to support consumption
Demand has also shown greater resilience than the recent price correction might suggest. Following the sharp decline in copper prices, market trading activity strengthened noticeably, with both refined copper consumers and end-uses increasing purchases at lower prices. The response has been particularly evident in the copper rod market. On September 11, when copper prices fell sharply, daily copper rod transactions reached their highest level since February this year. This suggests that the prolonged rise in copper prices had left some end-users with relatively low raw material inventories, while underlying rigid demand for copper remained resilient. In addition, the shortage of valid input invoices among scrap processors continue to affect the market. To make up for input-invoice shortages, some processors may continue purchasing refined copper occasionally, providing additional support to spot consumption.
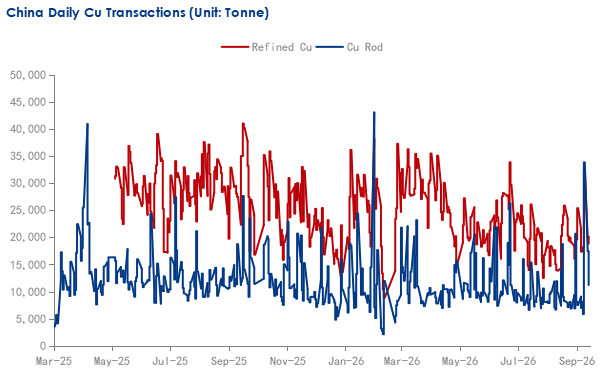
Source: Mysteel
Looking ahead, downstream manufacturers typically build raw material inventory ahead of the Mid-Autumn Festival and National Day holidays to ensure normal production during the holiday period. September and October are also traditionally part of China's peak copper consumption season. Therefore, lower copper prices could further stimulate downstream purchasing and encourage end-users to replenish inventory ahead of the holidays. With supply remaining tight, an improvement in physical demand accelerates the transition from the current price correction back toward an upward trend. That said, copper prices remain highly volatile, and the sustainability of the recovery will ultimately depend on whether the expected seasonal demand materializes. Actual downstream consumption therefore remains an important indicator to monitor in the coming weeks.
Copper prices resume upward trend
The recent sharp decline in copper prices was primarily driven by the rapid unwinding of the tariff-related risk premium rather than a fundamental deterioration in the physical market. As expectations for U.S. tariffs on refined copper cooled, the speculative premium accumulated during the previous rally was quickly removed, triggering a significant price correction. With this adjustment now underway, market attention is expected to gradually shift back toward fundamentals.
Written by Mingyuan Wang, wangmingyuan@mysteel.com