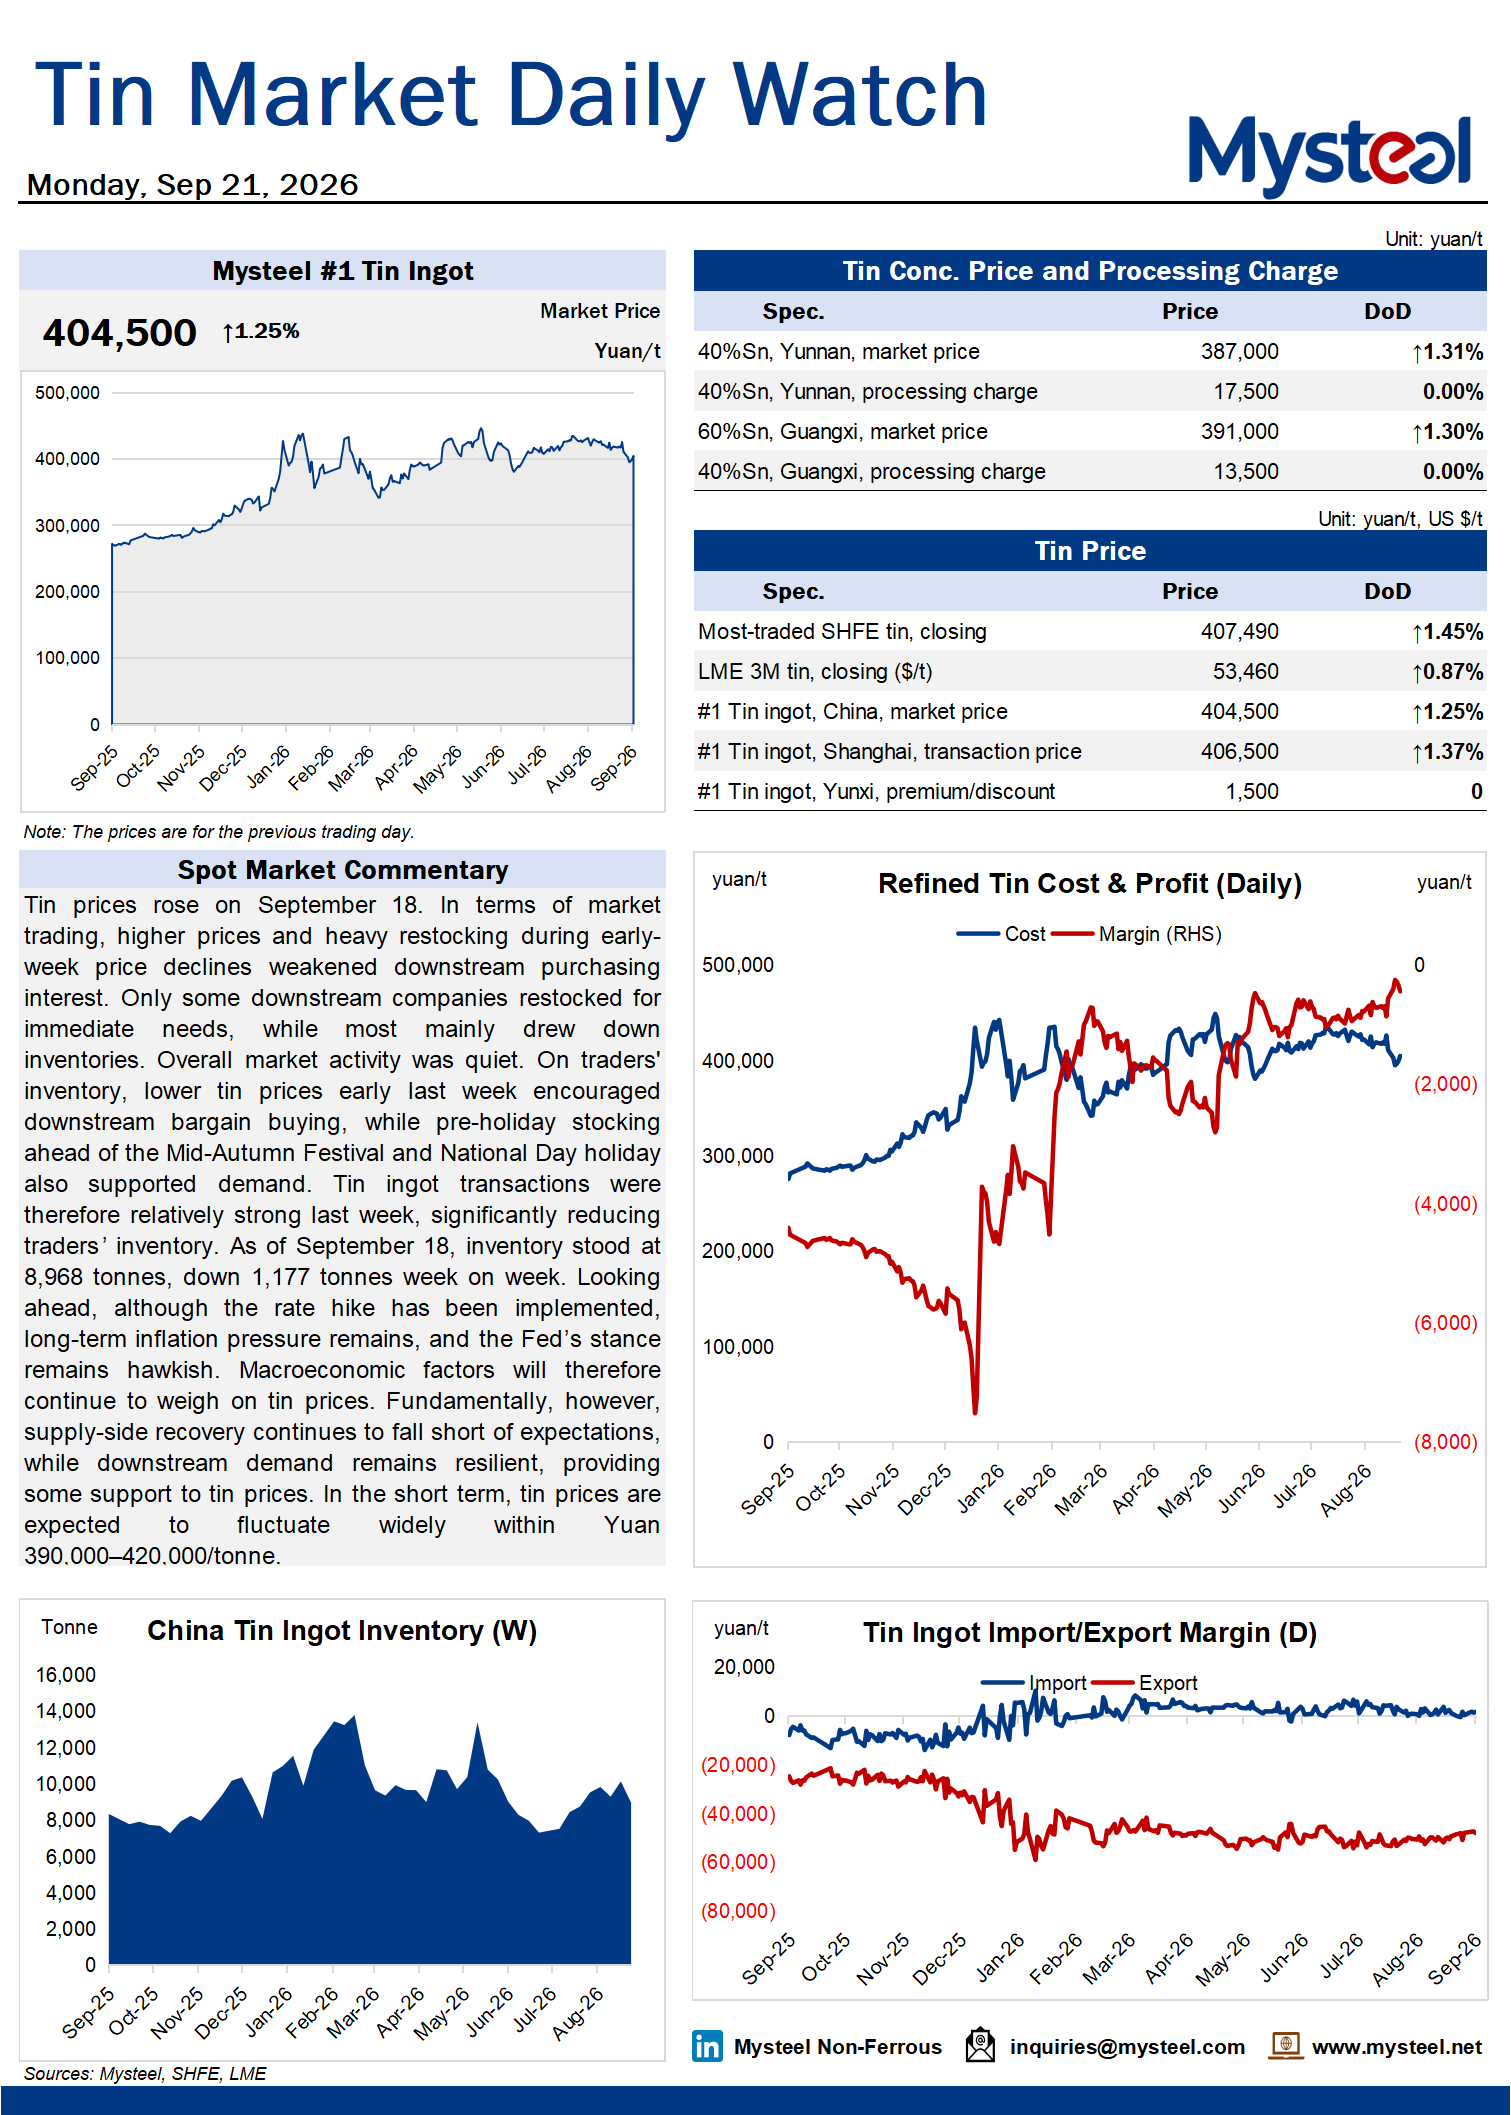
Tin prices rose on September 18. In terms of market trading, higher prices and heavy restocking during early-week price declines weakened downstream purchasing interest. Only some downstream companies restocked for immediate needs, while most mainly drew down inventories. Overall market activity was quiet. On traders' inventory, lower tin prices early last week encouraged downstream bargain buying, while pre-holiday stocking ahead of the Mid-Autumn Festival and National Day holiday also supported demand. Tin ingot transactions were therefore relatively strong last week, significantly reducing traders' inventory. As of September 18, inventory stood at 8,968 tonnes, down 1,177 tonnes week on week. Looking ahead, although the rate hike has been implemented, long-term inflation pressure remains, and the Fed's stance remains hawkish. Macroeconomic factors will therefore continue to weigh on tin prices. Fundamentally, however, supply-side recovery continues to fall short of expectations, while downstream demand remains resilient, providing some support to tin prices. In the short term, tin prices are expected to fluctuate widely within Yuan 390,000–420,000/tonne.