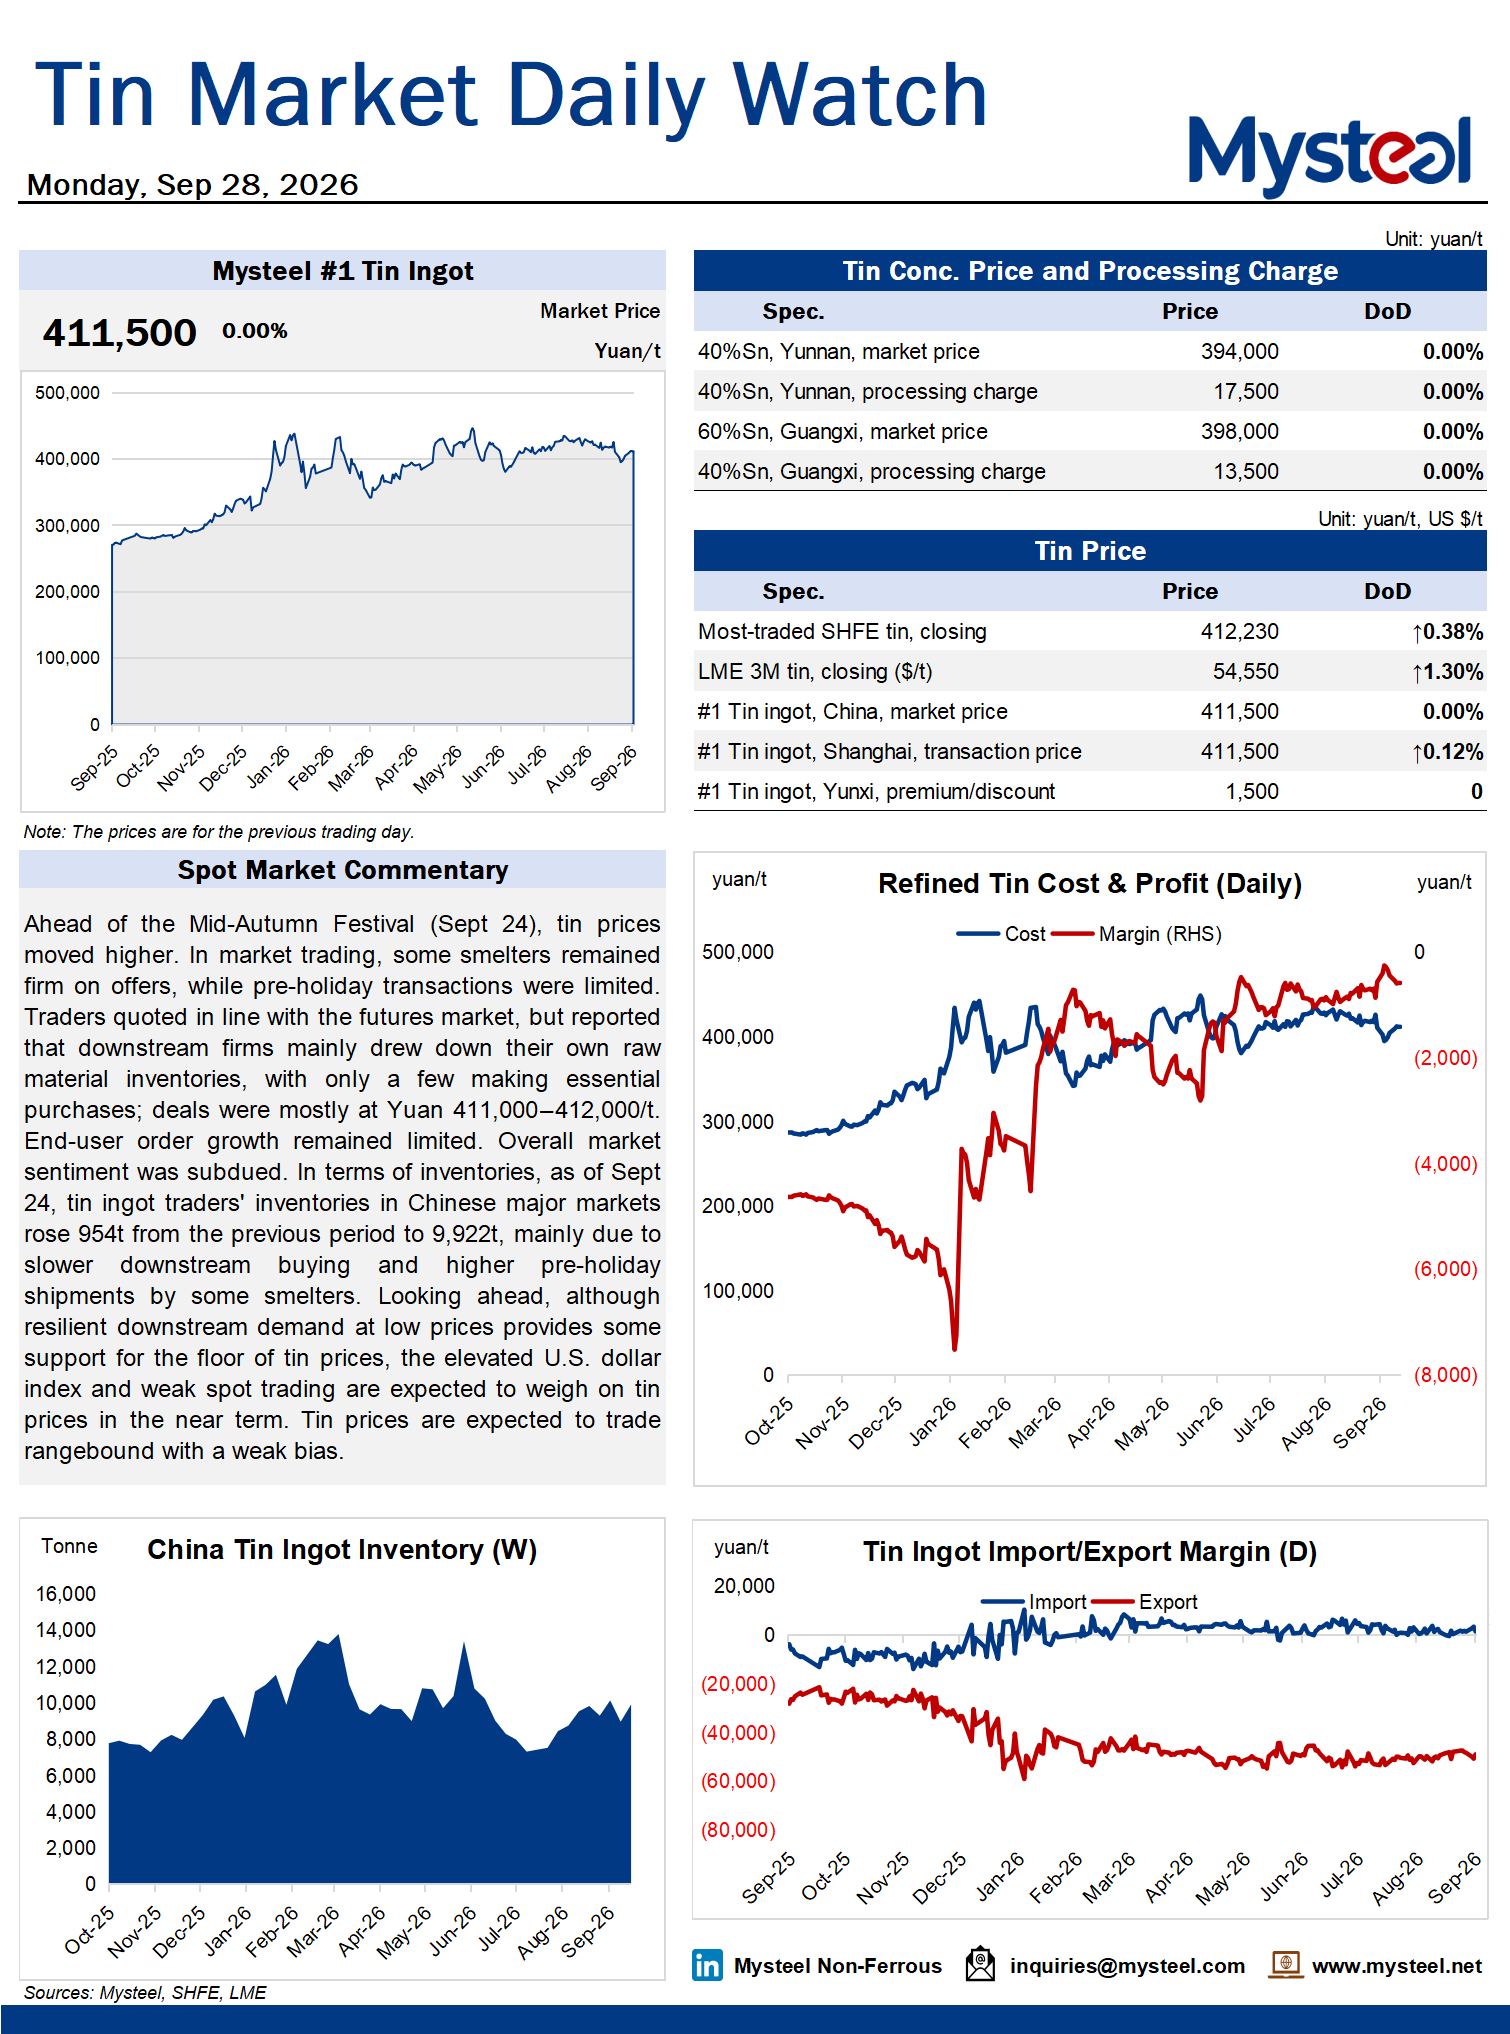
Ahead of the Mid-Autumn Festival (Sept 24), tin prices moved higher. In market trading, some smelters remained firm on offers, while pre-holiday transactions were limited. Traders quoted in line with the futures market, but reported that downstream firms mainly drew down their own raw material inventories, with only a few making essential purchases; deals were mostly at Yuan 411,000–412,000/t. End-user order growth remained limited. Overall market sentiment was subdued. In terms of inventories, as of Sept 24, tin ingot traders' inventories in Chinese major markets rose 954t from the previous period to 9,922t, mainly due to slower downstream buying and higher pre-holiday shipments by some smelters. Looking ahead, although resilient downstream demand at low prices provides some support for the floor of tin prices, the elevated U.S. dollar index and weak spot trading are expected to weigh on tin prices in the near term. Tin prices are expected to trade rangebound with a weak bias.