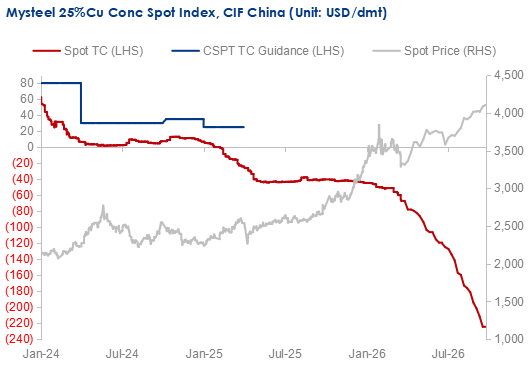
Mysteel's imported copper concentrate spot treatment charge (TC) index stood at -$224.63/dmt as of September 24, with spot trading remaining subdued. On the demand side, some smelters have already cut production or were planning to reduce output, while others were seeking to lower costs by reducing feed rates, adjusting concentrate grades, and increasing the use of non-standard ores and pyrite in their feedstock. Some traders reported that their spot cargoes had largely been sold out, while offers for forward spot cargoes had yet to start. TCs are expected to remain weak in the short term, although further downside may be limited.
Source: Mysteel
In terms of mine tenders, market sources indicated that a Cuajone Mine cargo was sold at -$310/dmt, and transactions at -$228/dmt, -$234/dmt, and -$238/dmt were also reported. Some traders estimated that fixed-price transactions were mostly concluded at around -$230 to -$235/dmt, while transactions based on spot index were generally settled around deductions of $24 to $25/dmt.
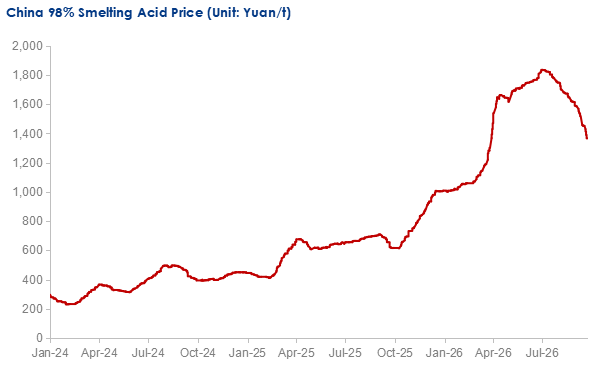
China's average 98% smelting sulfuric acid price stood at Yuan 1,369/tonne on September 24, falling from Yuan 1,452/tonne on September 18, with the supplement to copper smelters' profits gradually weakening.
China's sulfuric acid prices are expected to trend downwards this week. On the supply side, sulfuric acid producers are expected to maintain relatively stable operating rates, keeping market supply ample. However, major acid producers in Guangxi, Shandong and Anhui are scheduled to gradually enter routine maintenance in mid-October, which may temporarily tighten supply. Meanwhile, widening losses among smelting acid producers are expected to accelerate production cuts. On the demand side, this is the final week before the National Day holiday (October 1-7), and most sulfuric acid producers are expected to focus on fulfilling existing orders. During the holiday, transportation restrictions in many parts of China will limit cross-regional cargo flows, resulting in relatively thin market activity. Downstream, phosphate fertilizer producers are expected to make only limited purchases for essential restocking before the holiday, providing little support for sulfuric acid demand. Demand from the chemical sector remains mixed but is generally showing a slight upward trend. Cost-side support is also weakening. Sulfur prices have fluctuated downward, while pyrite prices have followed the falling sulfuric acid prices. Although copper, lead and zinc ore prices remain elevated and relatively stable, their overall ability to provide a firm floor for sulfuric acid costs remains limited. Overall, sulfuric acid producers are expected to continue actively selling ahead of the holiday, while cost-side support remains weak. Sulfuric acid prices therefore still have some room for a modest decline in the near term.
Source: Mysteel
Recently, sulfuric acid prices have continued to decline amid weak demand and ample supply, gradually reducing the contribution to copper smelters' profits. Moving forward, attention should be paid to the risk of a sharper decline in sulfuric acid prices, which could further weigh on copper smelters' profitability.
Written by Mingyuan Wang, wangmingyuan@mysteel.com