Mysteel's imported copper concentrate spot treatment charge (TC) index stood at -$240.83/dmt as of October 16, continuing falling week on week, while index-based deductions narrowed slightly. Some smelters indicated that their acceptable fixed TC level was around -$230/dmt. Market feedback suggested that some smelters had begun arranging production cuts and maintenance, while several had largely completed their copper concentrate procurement for the year. Consequently, spot purchases may weaken further toward year-end. Traders maintained firm offers and showed little willingness to sell at fixed TCs, favoring index-based pricing with deductions. Most market participants adopted a cautious approach, and spot TCs are expected to face further downward pressure.
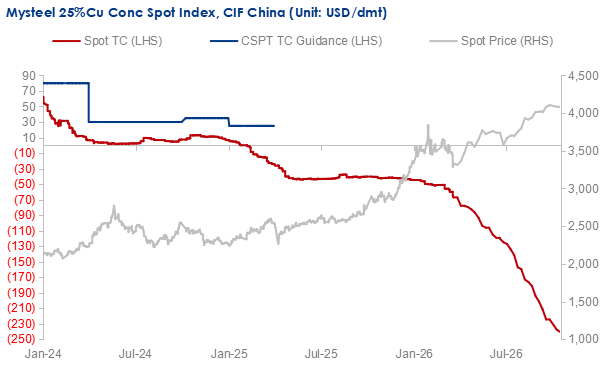
Source: Mysteel
According to Mysteel's survey, one trader sold 30,000-40,000 tonnes of copper concentrate scheduled for shipment in Q4 to a smelter at an index deduction of $4-5/dmt, while another sold 10,000 tonnes of blended copper concentrate to a smelter at -$248/dmt. Meanwhile, Constancia's tender for 10,000 tonnes of copper concentrate was settled at -$314/dmt.
The strike at Antofagasta's Centinela mine ended on October 18 local time after lasting more than a week. However, the company said the strike would have no negative impact on its overall output. Meanwhile, recent strike risks at BHP's Escondida mine have also heightened global concerns over the increasingly inelastic supply of copper concentrate.
China's average 98% smelting sulfuric acid price stood at Yuan 1,346/tonne on October 16, slightly rising from Yuan 1,300/tonne on October 9, mainly supported by shrinking supply amid concentrated maintenance, while demand recovery stayed limited.
China's sulfuric acid prices are expected to continue showing regional divergence this week, with market participants largely adopting a wait-and-see approach. On the supply side, domestic sulfuric acid production is expected to decline further, tightening overall supply. Some producers in Anhui, Shandong, Henan, and Hunan will remain under maintenance, while additional maintenance is scheduled in some producers in Sichuan and Guangxi this week. On the cost side, sulfur and pyrite prices are trending downward amid weak demand from the fertilizer sector, while prices of metal ores, including copper, lead, and zinc, will stay elevated. As a result, cost disparities among sulfuric acid producers using different feedstocks may widen. On the demand side, phosphate fertilizer demand remains weak, while demand from the chemical sector is also softening. End-user purchases will continue to focus primarily on essential needs. Overall, although recent supply tightening has provided some support, weakening cost support and a lack of positive demand-side drivers are limiting upward momentum for prices. Prices are expected to remain relatively firm in regions where maintenance reduces supply, while those in other regions will remain under pressure from weak demand and declining costs. Going forward, attention should focus on maintenance schedules, downstream restocking, and interregional sulfuric acid flows. Despite the regional divergence, sulfuric acid prices are expected to edge higher overall this week.
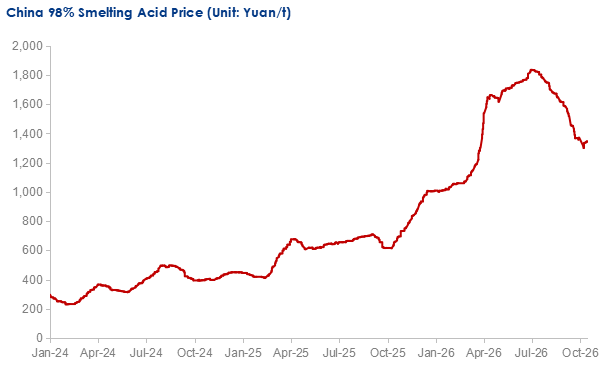
Source: Mysteel
Moving forward, close attention is needed on the sustainability of the rebound in sulfuric acid prices. Cost support may continue weakening, and demand improvement is likely to stay limited. Consequently, sulfuric acid's supplement to copper smelting profits is unlikely to increase notably, and Chinese smelters' operations will likely stay under pressure.
Join Mysteel's Q3 Review & Q4 Outlook Copper FREE Webinar to dig deep into the volatile market! Check the link below to learn more, and register NOW to secure your spots: https://www.mysteel.net/event-listings/100084-chinas-copper-market-q3-review-and-q4-outlook-will-the-price-rally-hold
Written by Mingyuan Wang, wangmingyuan@mysteel.com