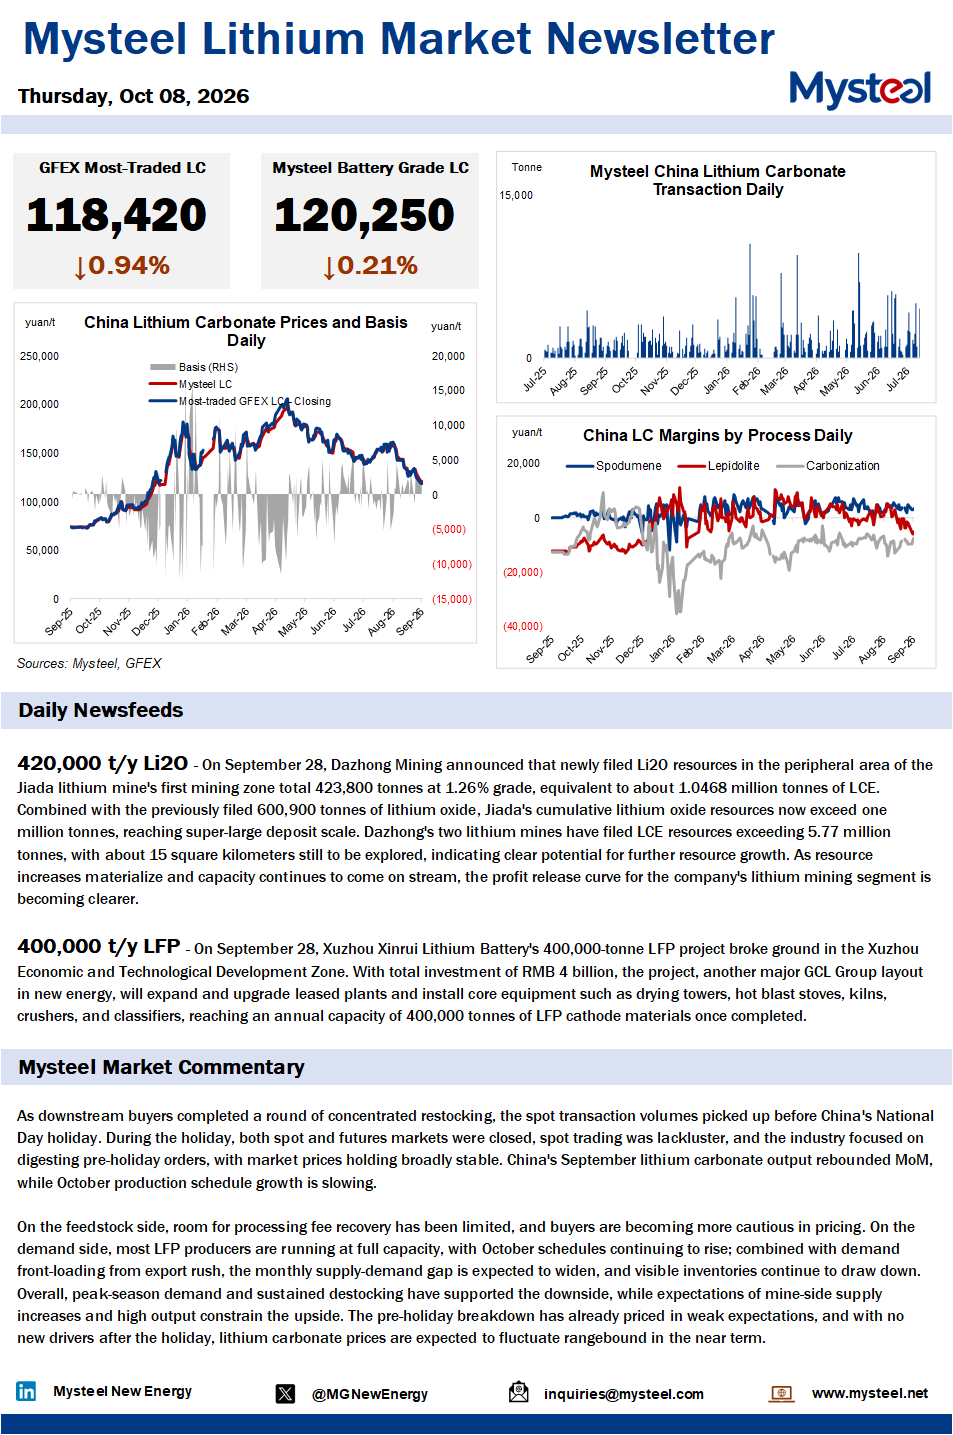
As downstream buyers completed a round of concentrated restocking, the spot transaction volumes picked up before China's National Day holiday. During the holiday, both spot and futures markets were closed, spot trading was lackluster, and the industry focused on digesting pre-holiday orders, with market prices holding broadly stable. China's September lithium carbonate output rebounded MoM, while October production schedule growth is slowing.
On the feedstock side, room for processing fee recovery has been limited, and buyers are becoming more cautious in pricing. On the demand side, most LFP producers are running at full capacity, with October schedules continuing to rise; combined with demand front-loading from export rush, the monthly supply-demand gap is expected to widen, and visible inventories continue to draw down. Overall, peak-season demand and sustained destocking have supported the downside, while expectations of mine-side supply increases and high output constrain the upside. The pre-holiday breakdown has already priced in weak expectations, and with no new drivers after the holiday, lithium carbonate prices are expected to fluctuate rangebound in the near term.