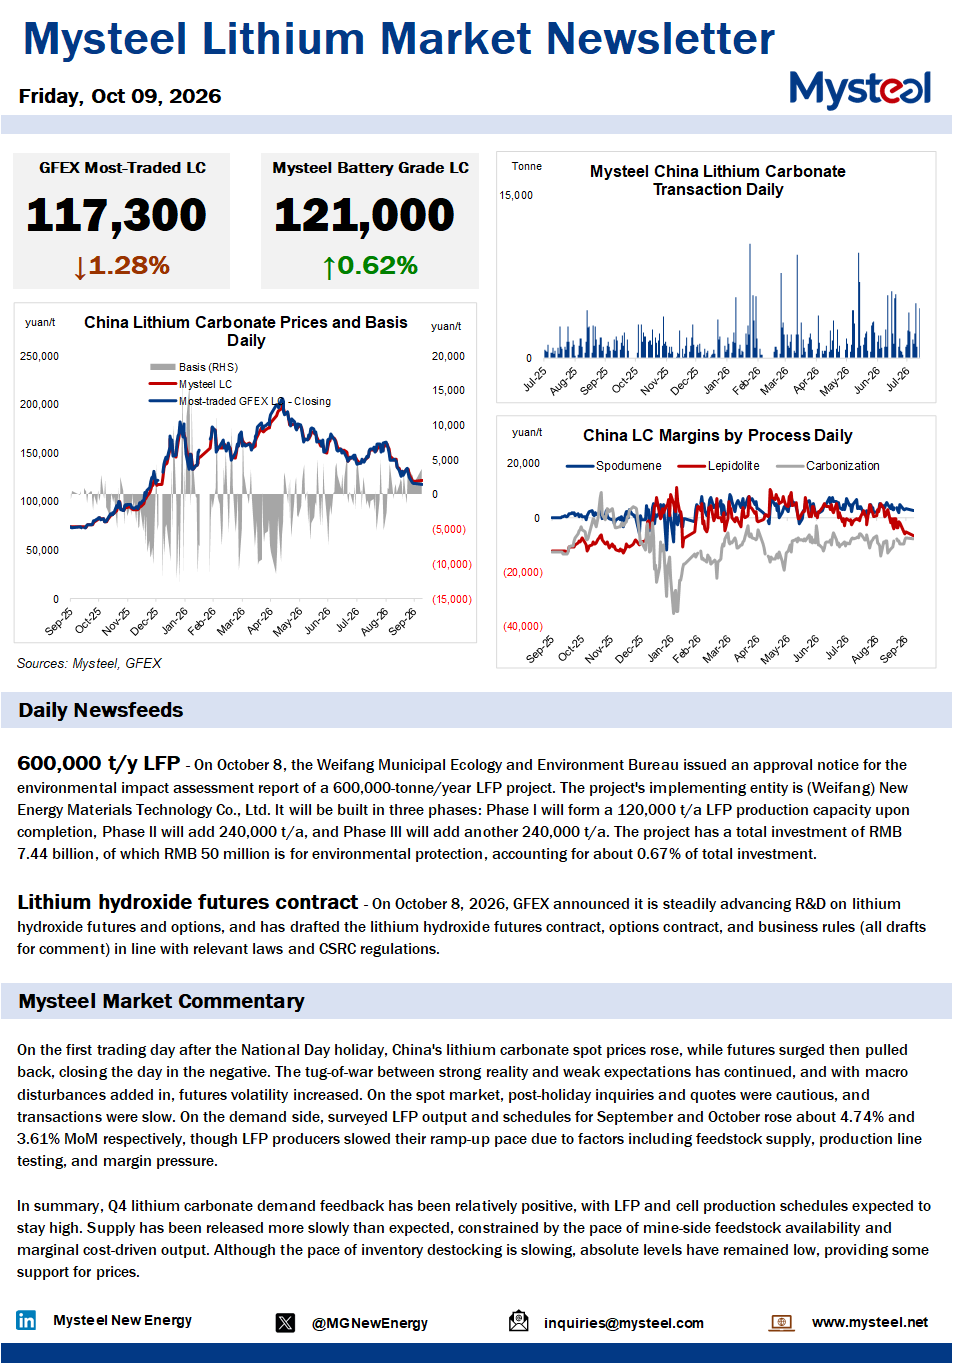
On the first trading day after the National Day holiday, China's lithium carbonate spot prices rose, while futures surged then pulled back, closing the day in the negative. The tug-of-war between strong reality and weak expectations has continued, and with macro disturbances added in, futures volatility increased. On the spot market, post-holiday inquiries and quotes were cautious, and transactions were slow. On the demand side, surveyed LFP output and schedules for September and October rose about 4.74% and 3.61% MoM respectively, though LFP producers slowed their ramp-up pace due to factors including feedstock supply, production line testing, and margin pressure.
In summary, Q4 lithium carbonate demand feedback has been relatively positive, with LFP and cell production schedules expected to stay high. Supply has been released more slowly than expected, constrained by the pace of mine-side feedstock availability and marginal cost-driven output. Although the pace of inventory destocking is slowing, absolute levels have remained low, providing some support for prices.