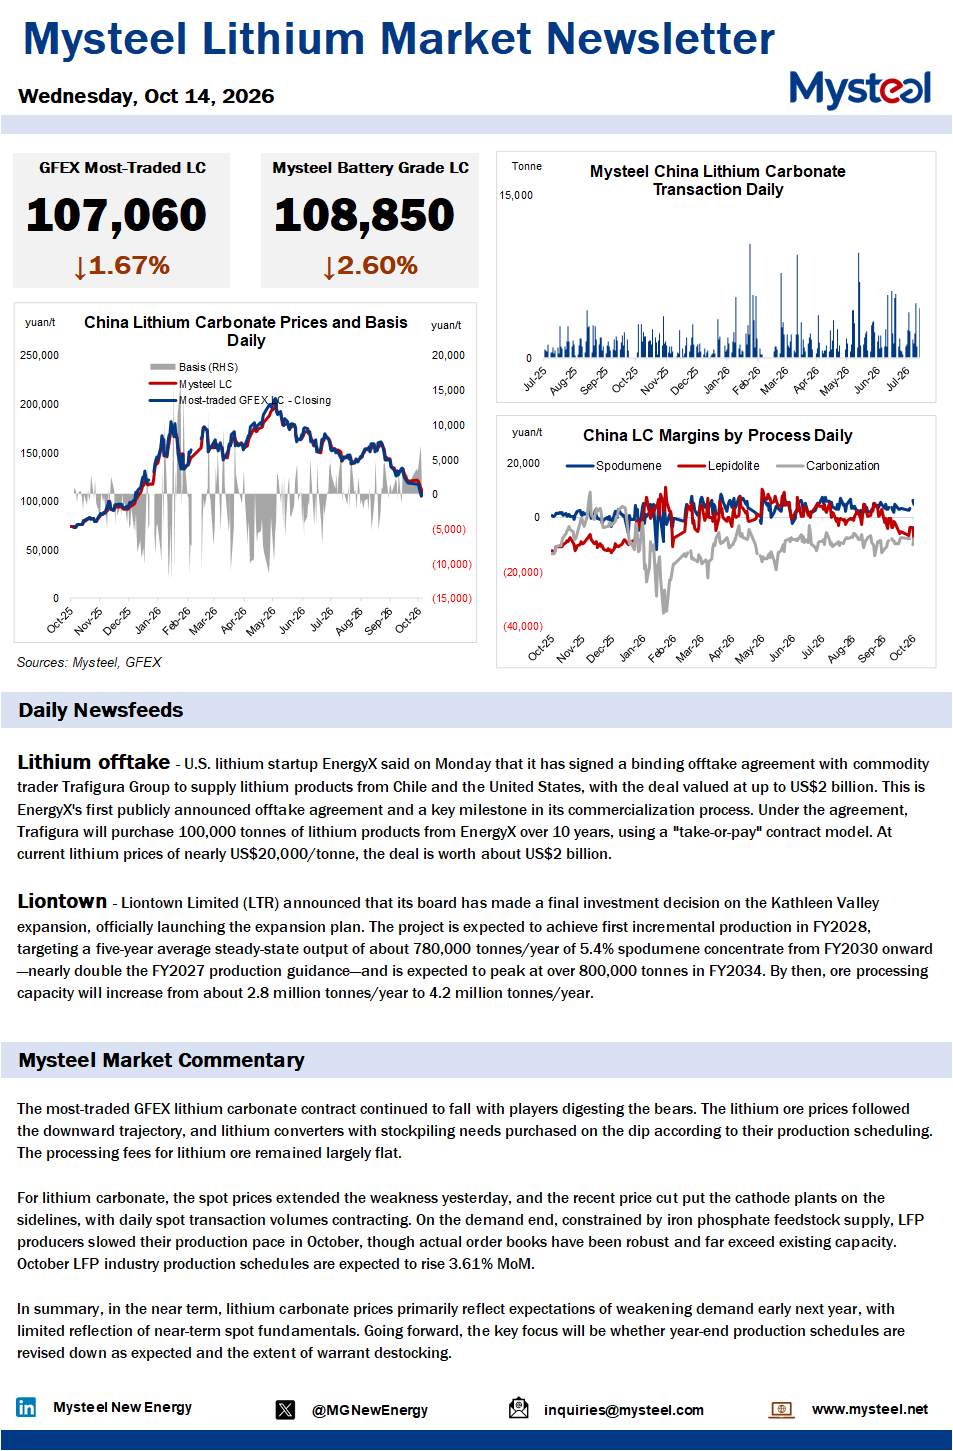
The most-traded GFEX lithium carbonate contract continued to fall with players digesting the bears. The lithium ore prices followed the downward trajectory, and lithium converters with stockpiling needs purchased on the dip according to their production scheduling. The processing fees for lithium ore remained largely flat.
For lithium carbonate, the spot prices extended the weakness yesterday, and the recent price cut put the cathode plants on the sidelines, with daily spot transaction volumes contracting. On the demand end, constrained by iron phosphate feedstock supply, LFP producers slowed their production pace in October, though actual order books have been robust and far exceed existing capacity. October LFP industry production schedules are expected to rise 3.61% MoM.
In summary, in the near term, lithium carbonate prices primarily reflect expectations of weakening demand early next year, with limited reflection of near-term spot fundamentals. Going forward, the key focus will be whether year-end production schedules are revised down as expected and the extent of warrant destocking.