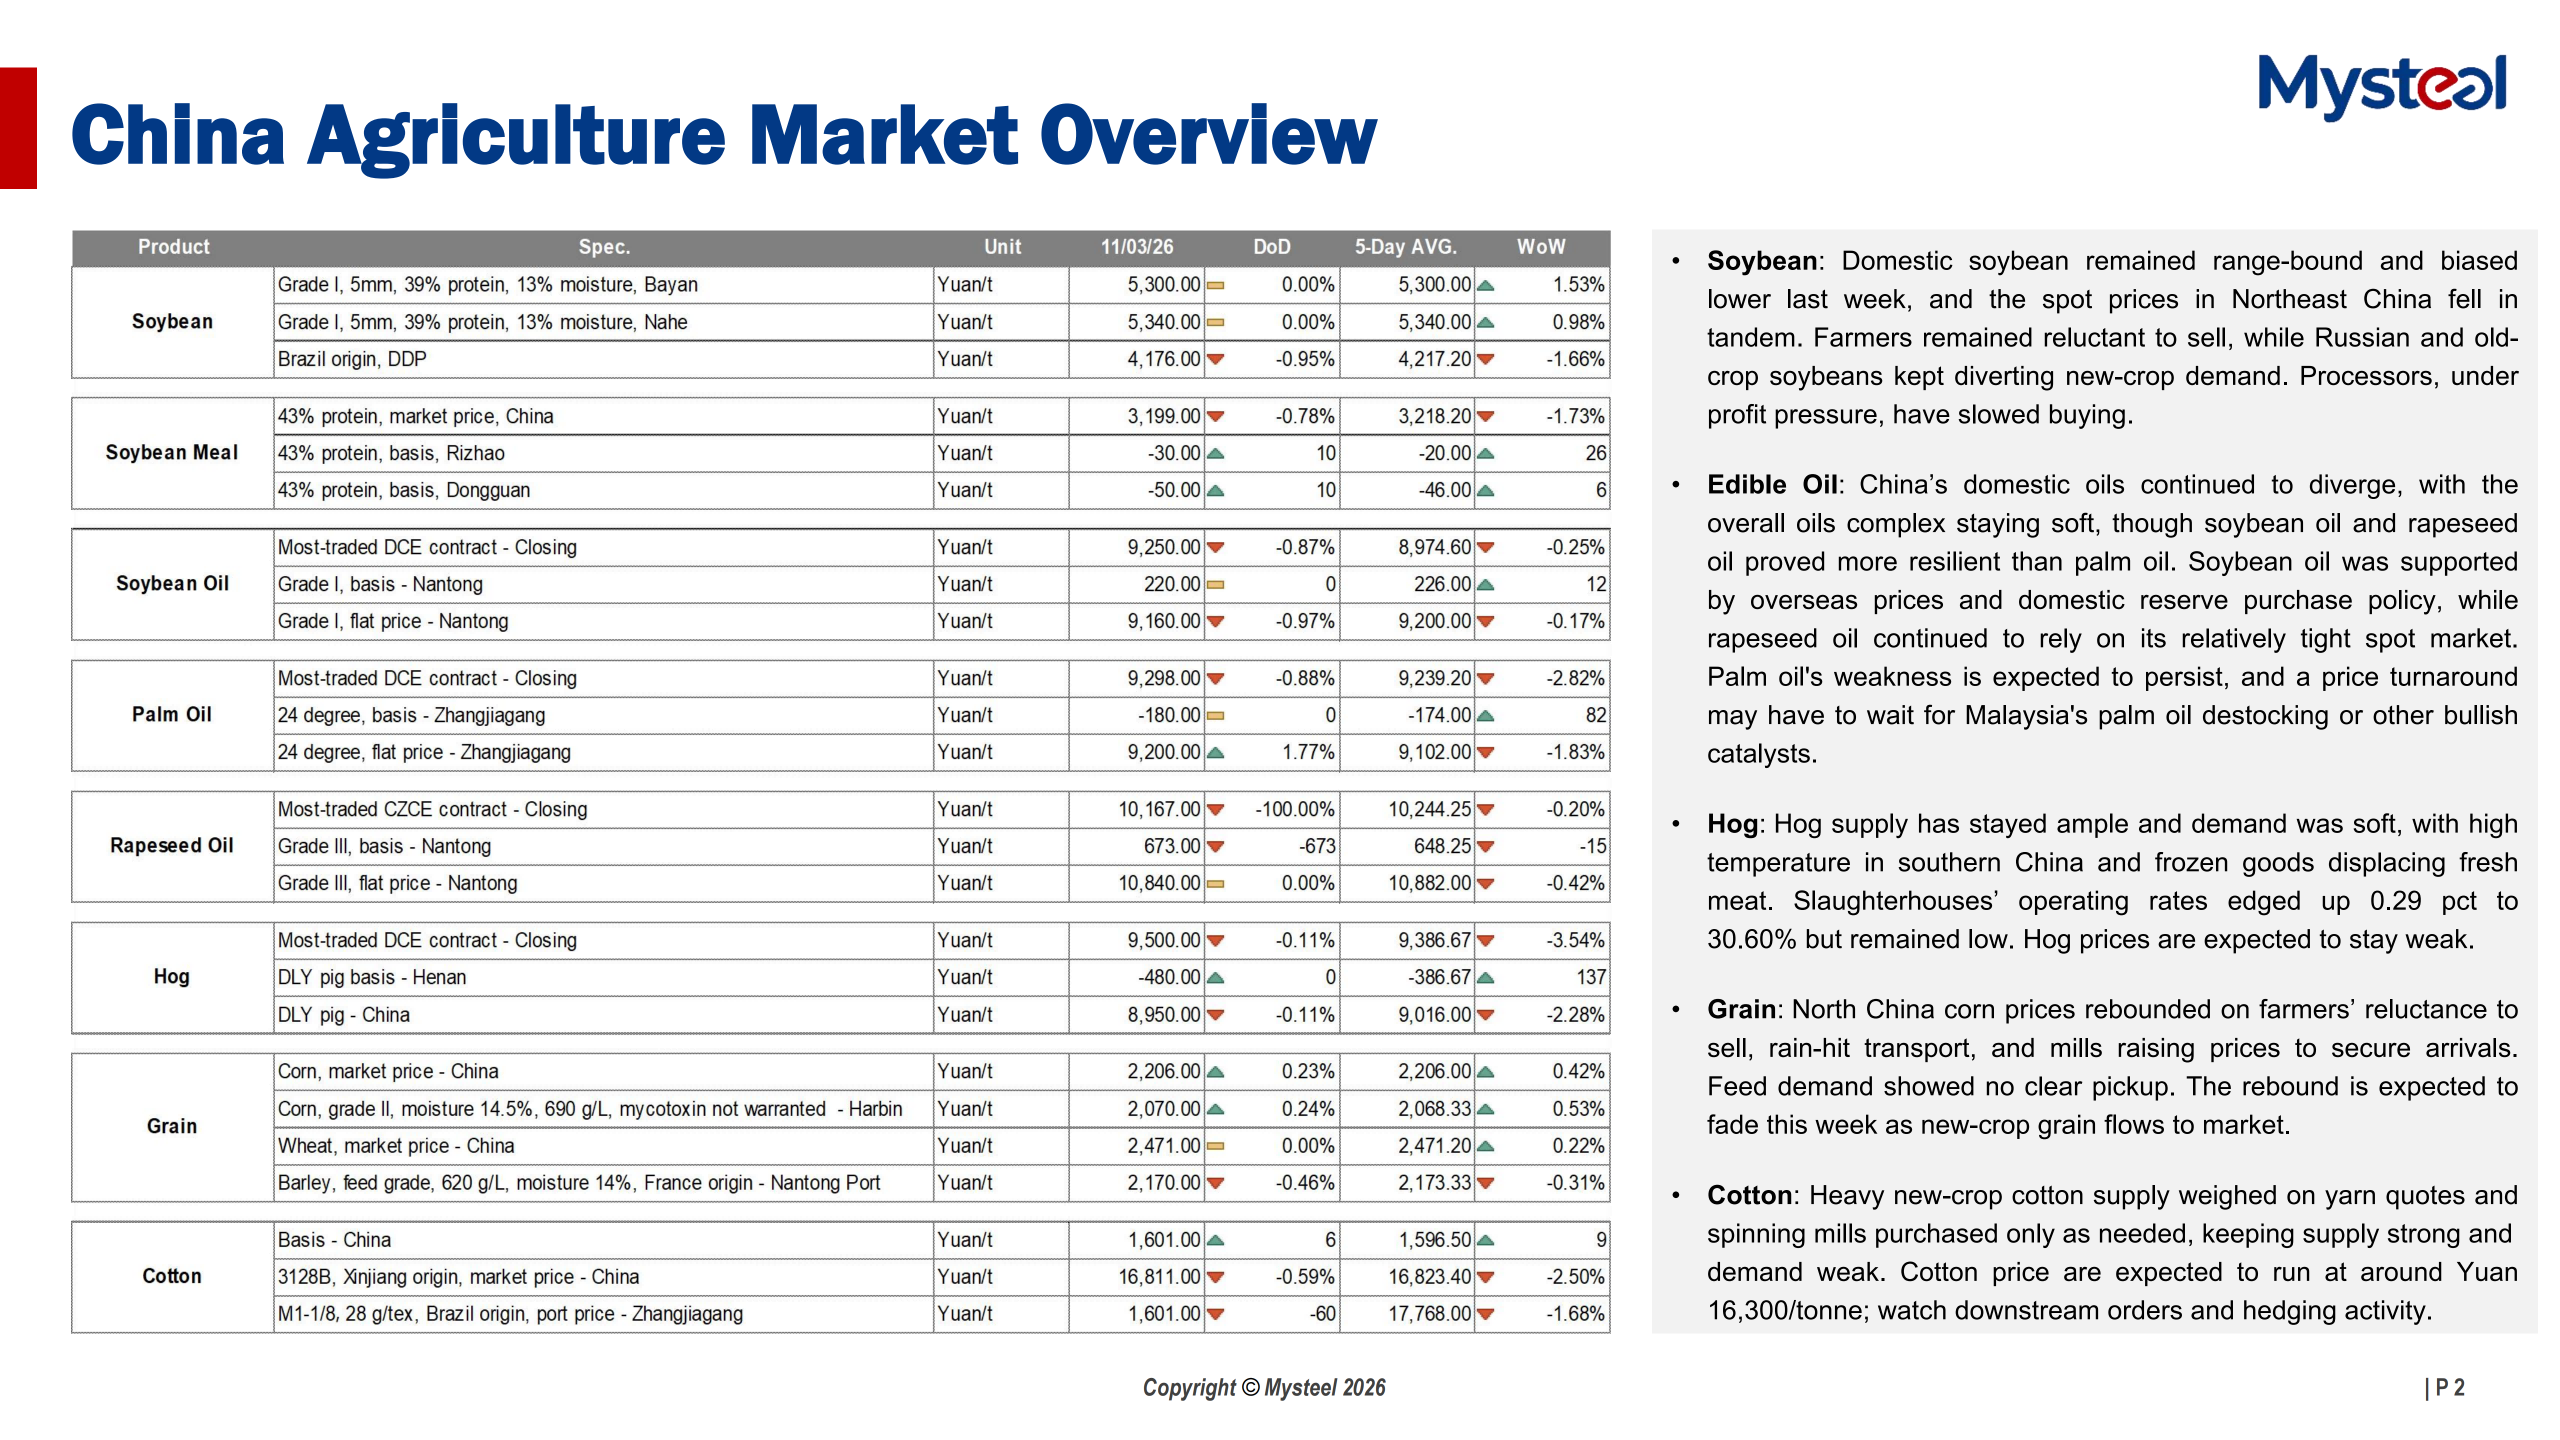
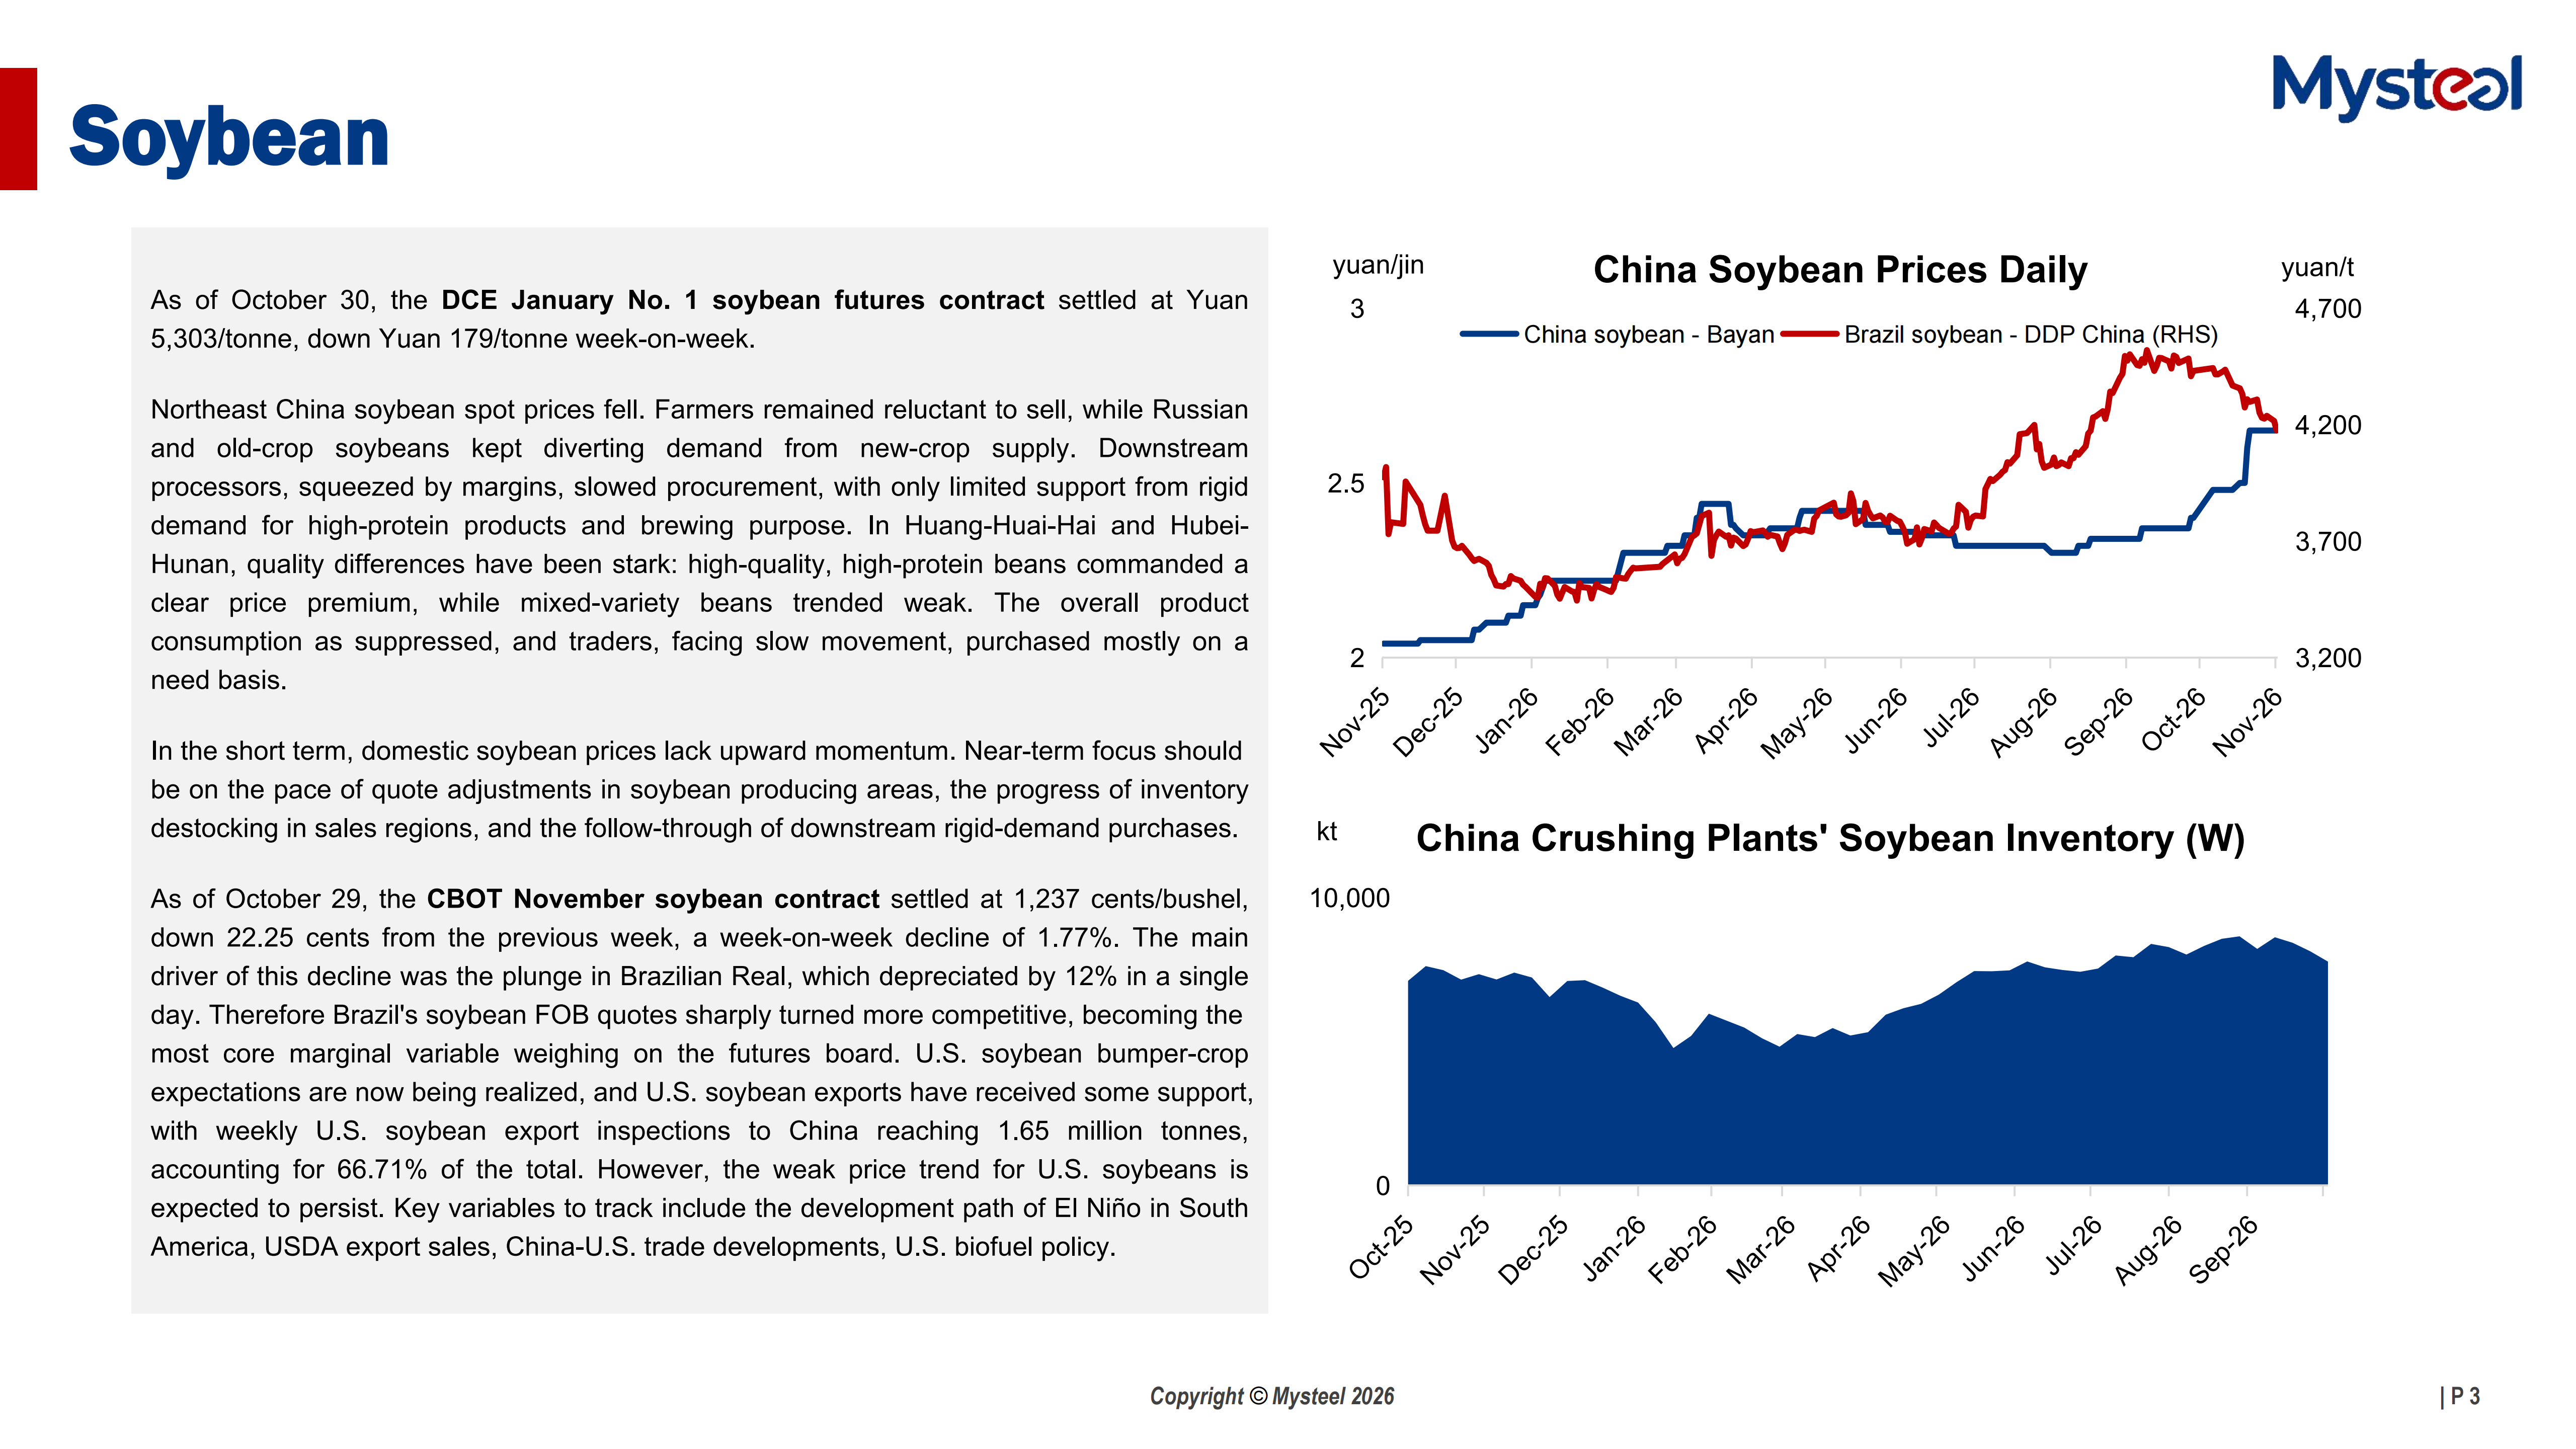
Soybean: Domestic soybean remained range-bound and biased lower last week, and the spot prices in Northeast China fell in tandem. Farmers remained reluctant to sell, while Russian and old-crop soybeans kept diverting new-crop demand. Processors, under profit pressure, have slowed buying.
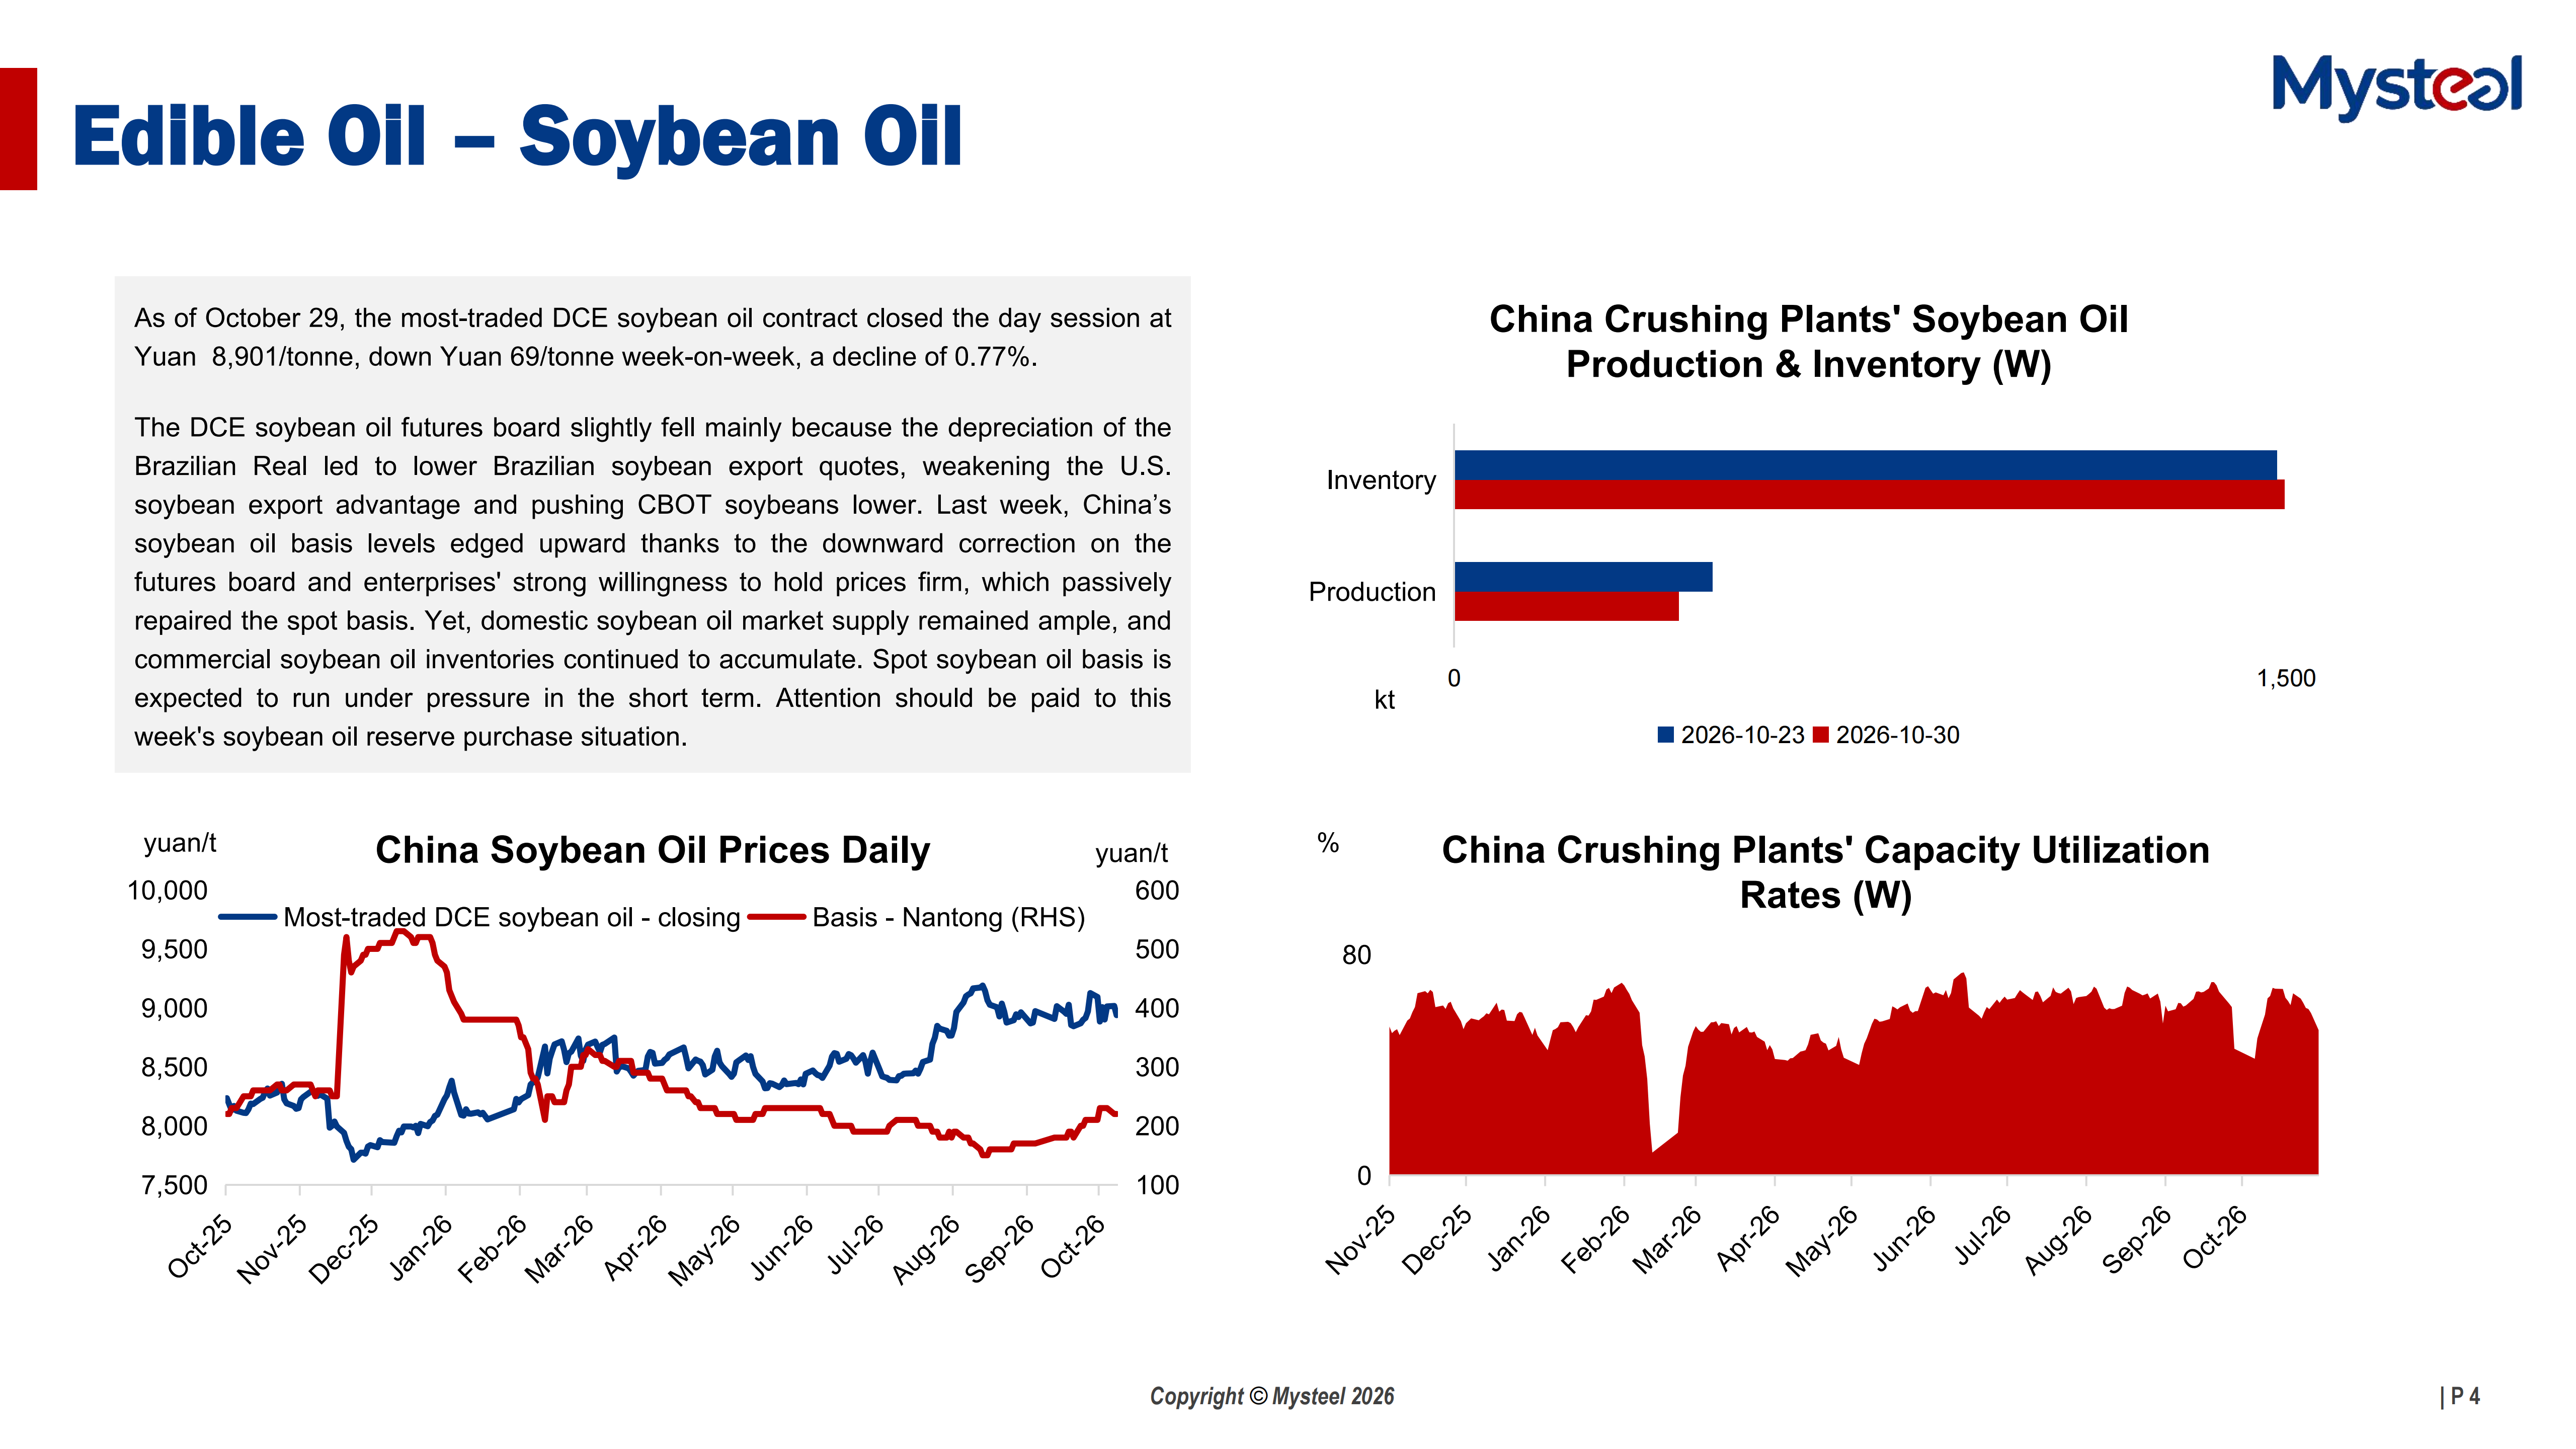
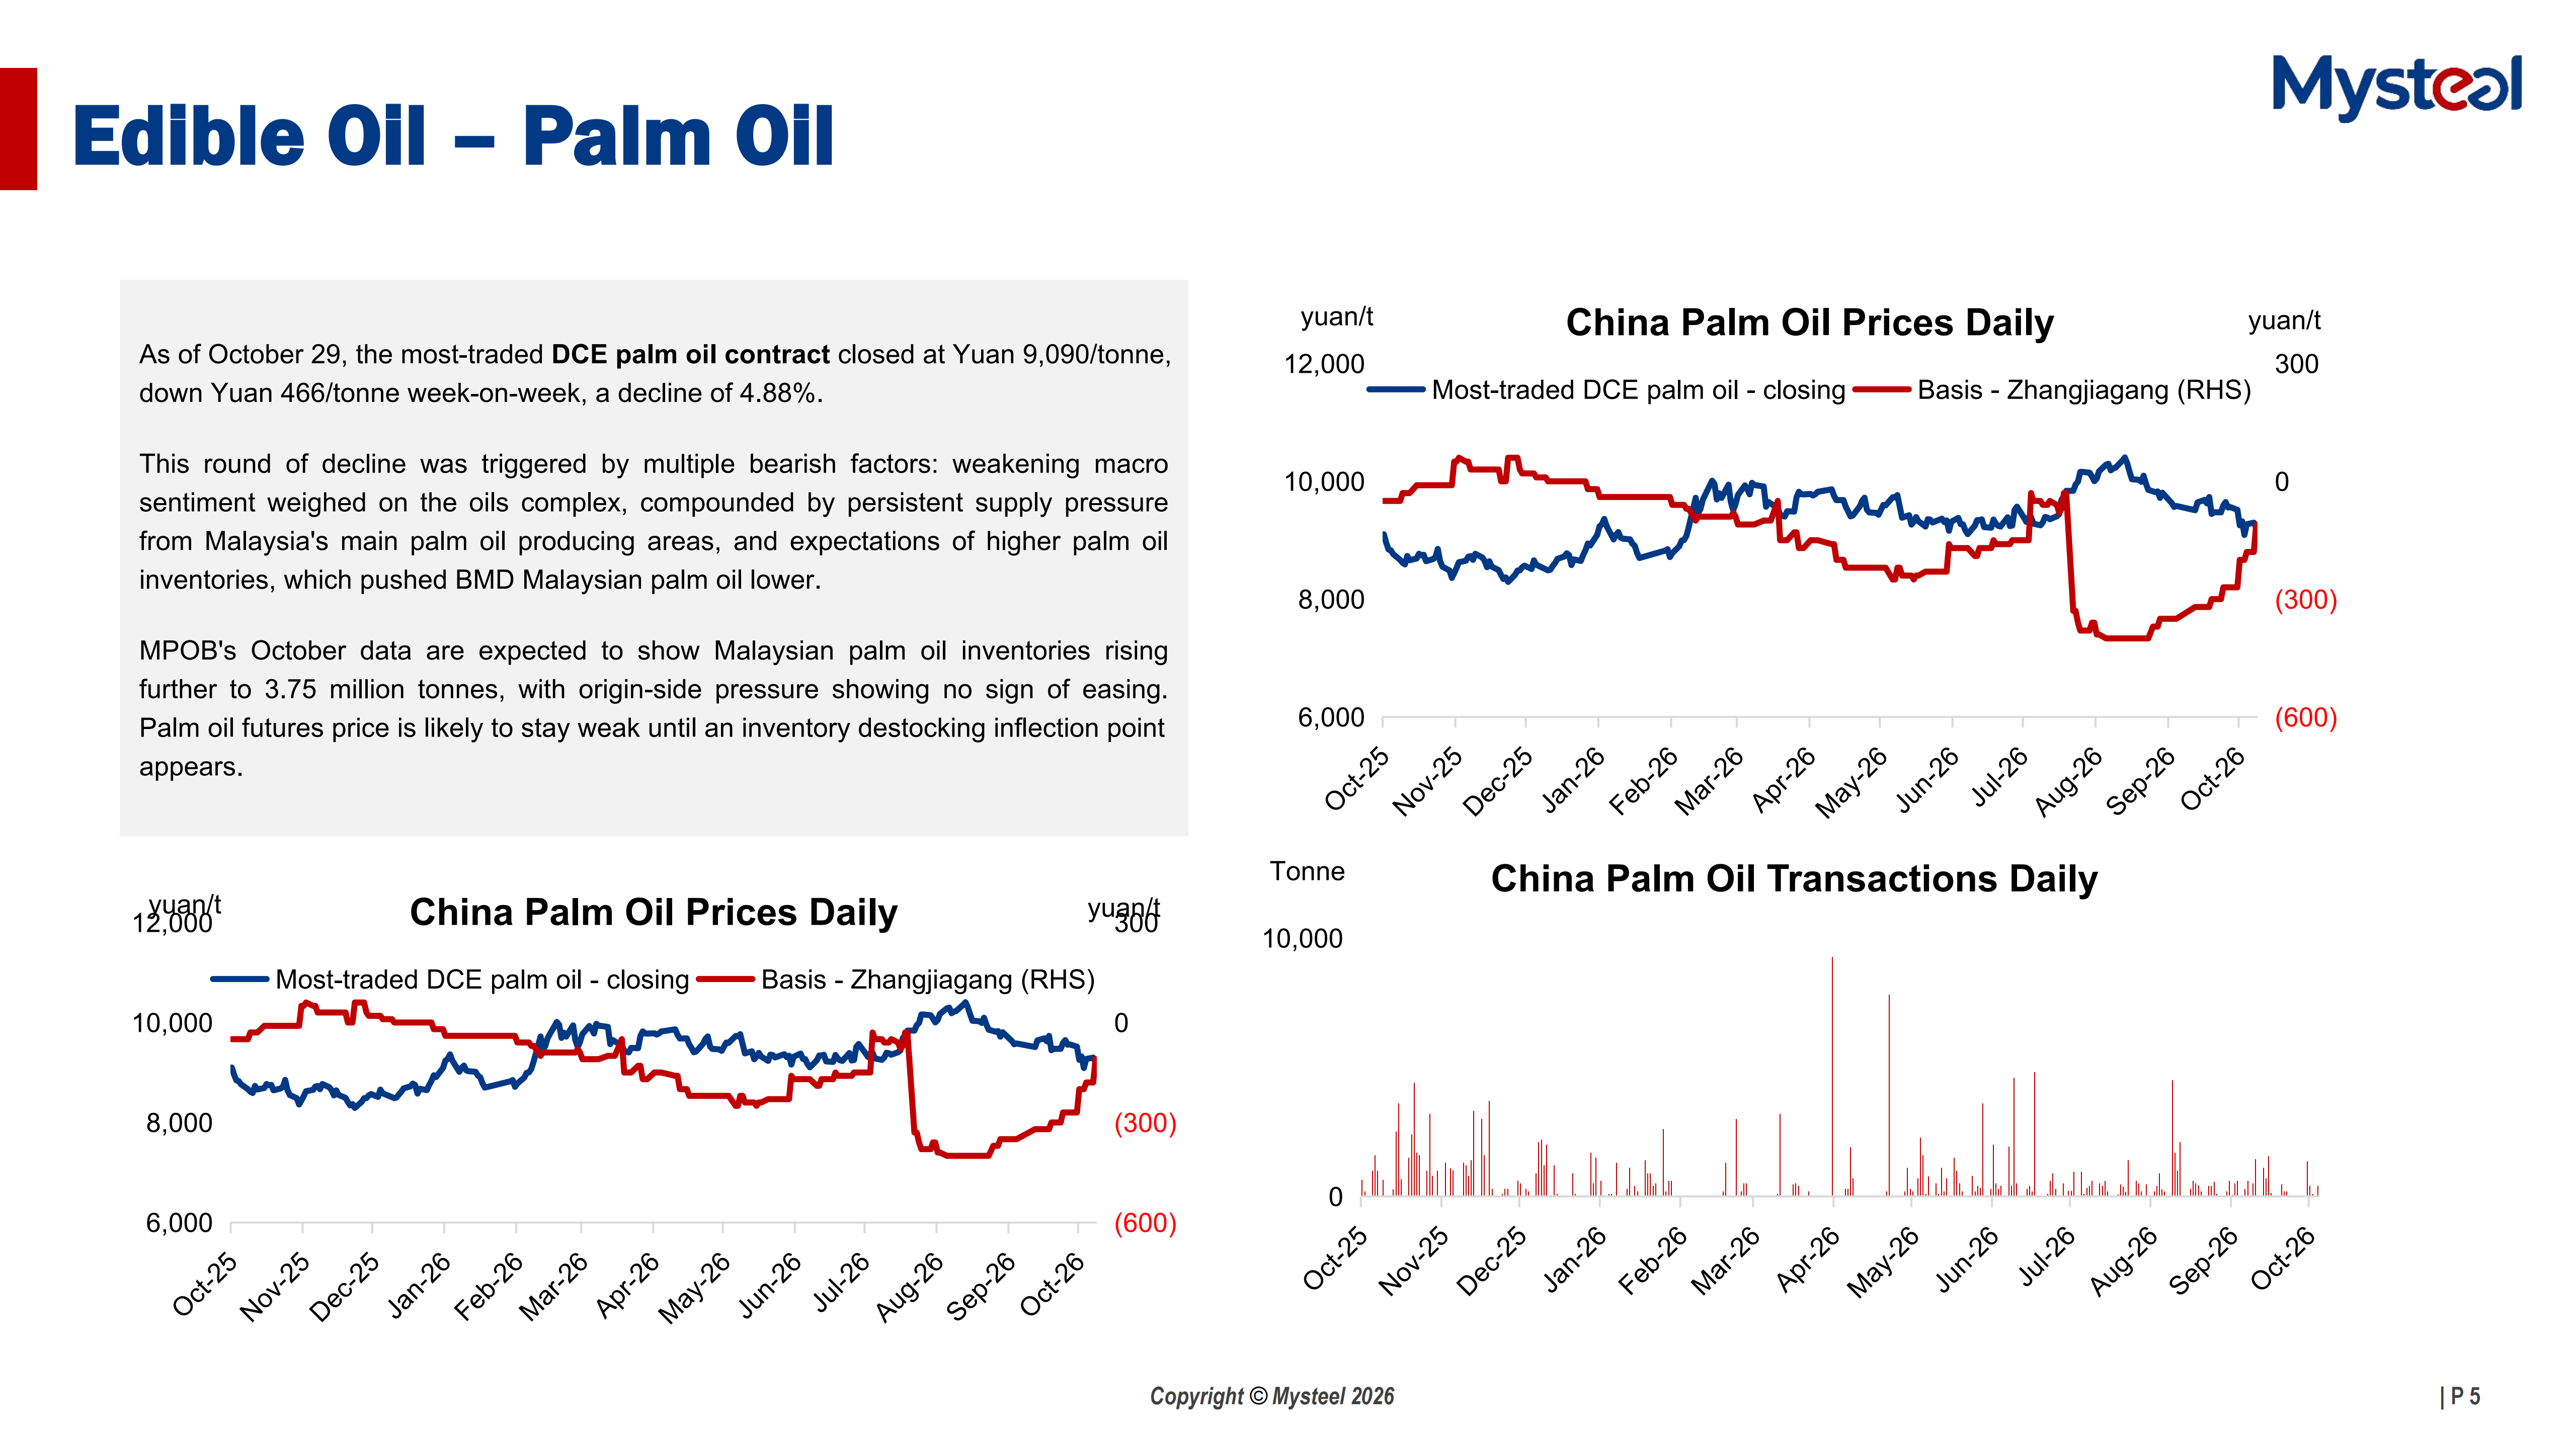
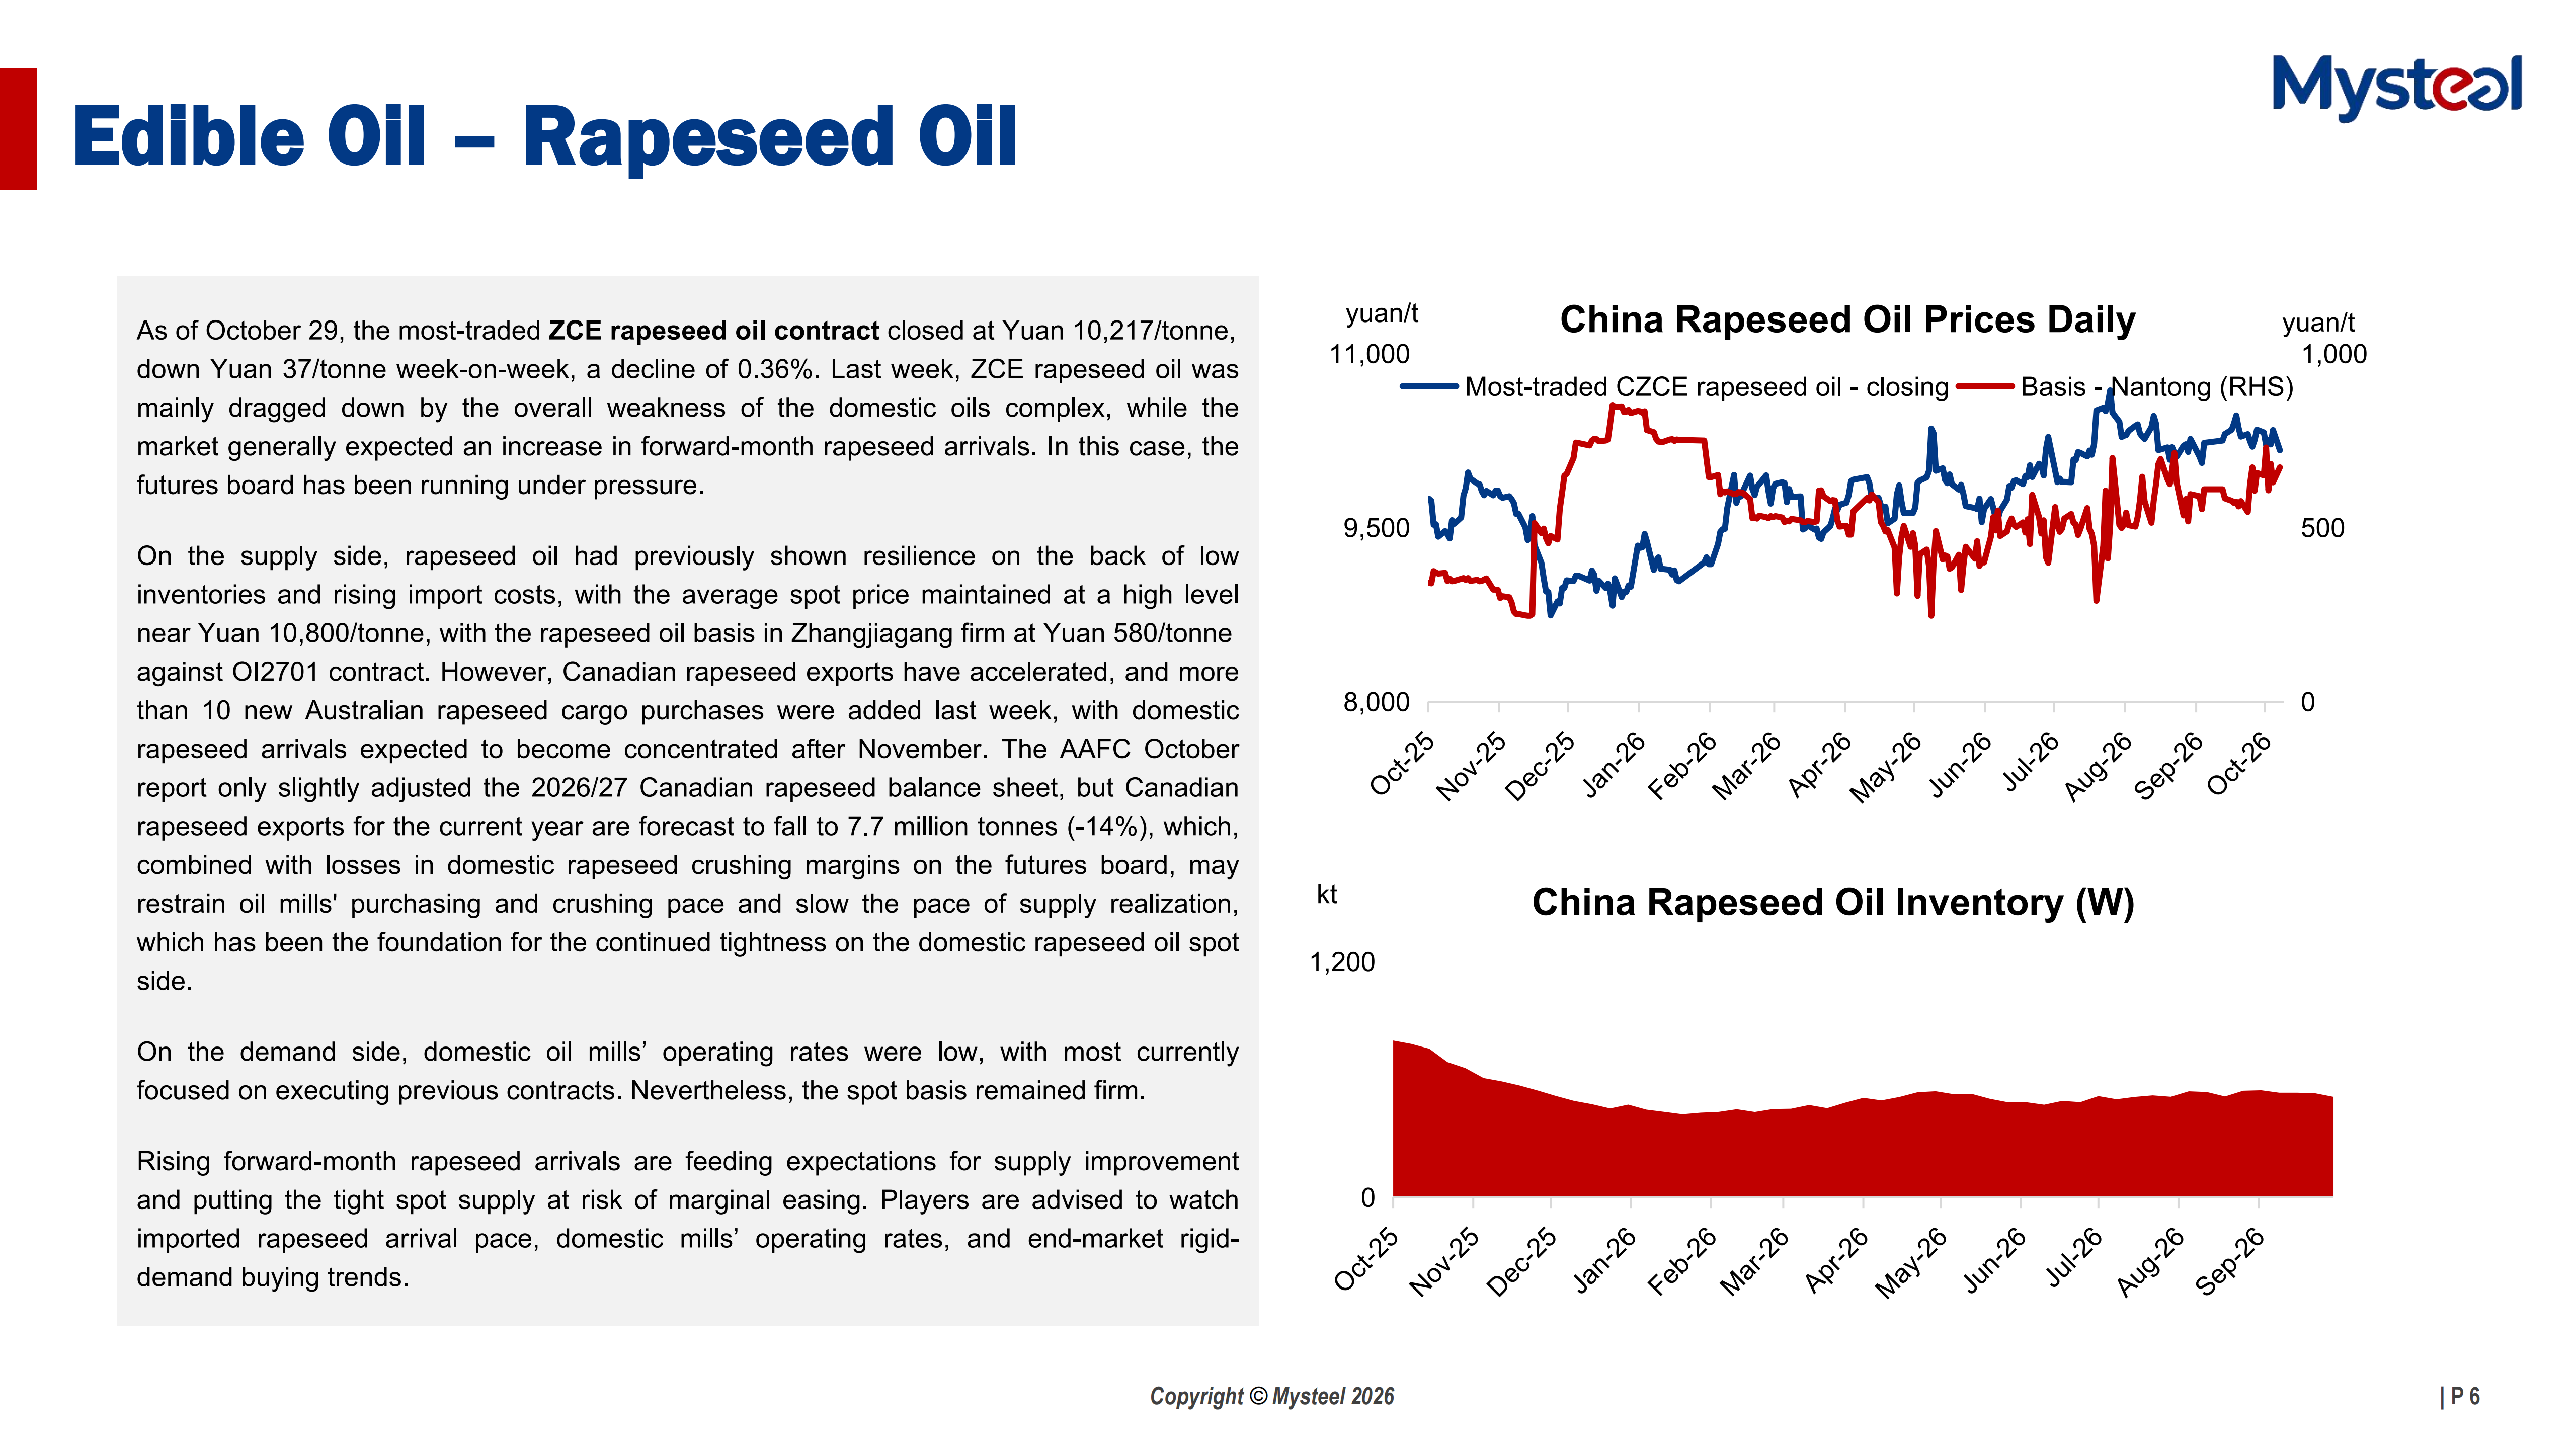
Edible Oil: China's domestic oils continued to diverge, with the overall oils complex staying soft, though soybean oil and rapeseed oil proved more resilient than palm oil. Soybean oil was supported by overseas prices and domestic reserve purchase policy, while rapeseed oil continued to rely on its relatively tight spot market. Palm oil's weakness is expected to persist, and a price turnaround may have to wait for Malaysia's palm oil destocking or other bullish catalysts.
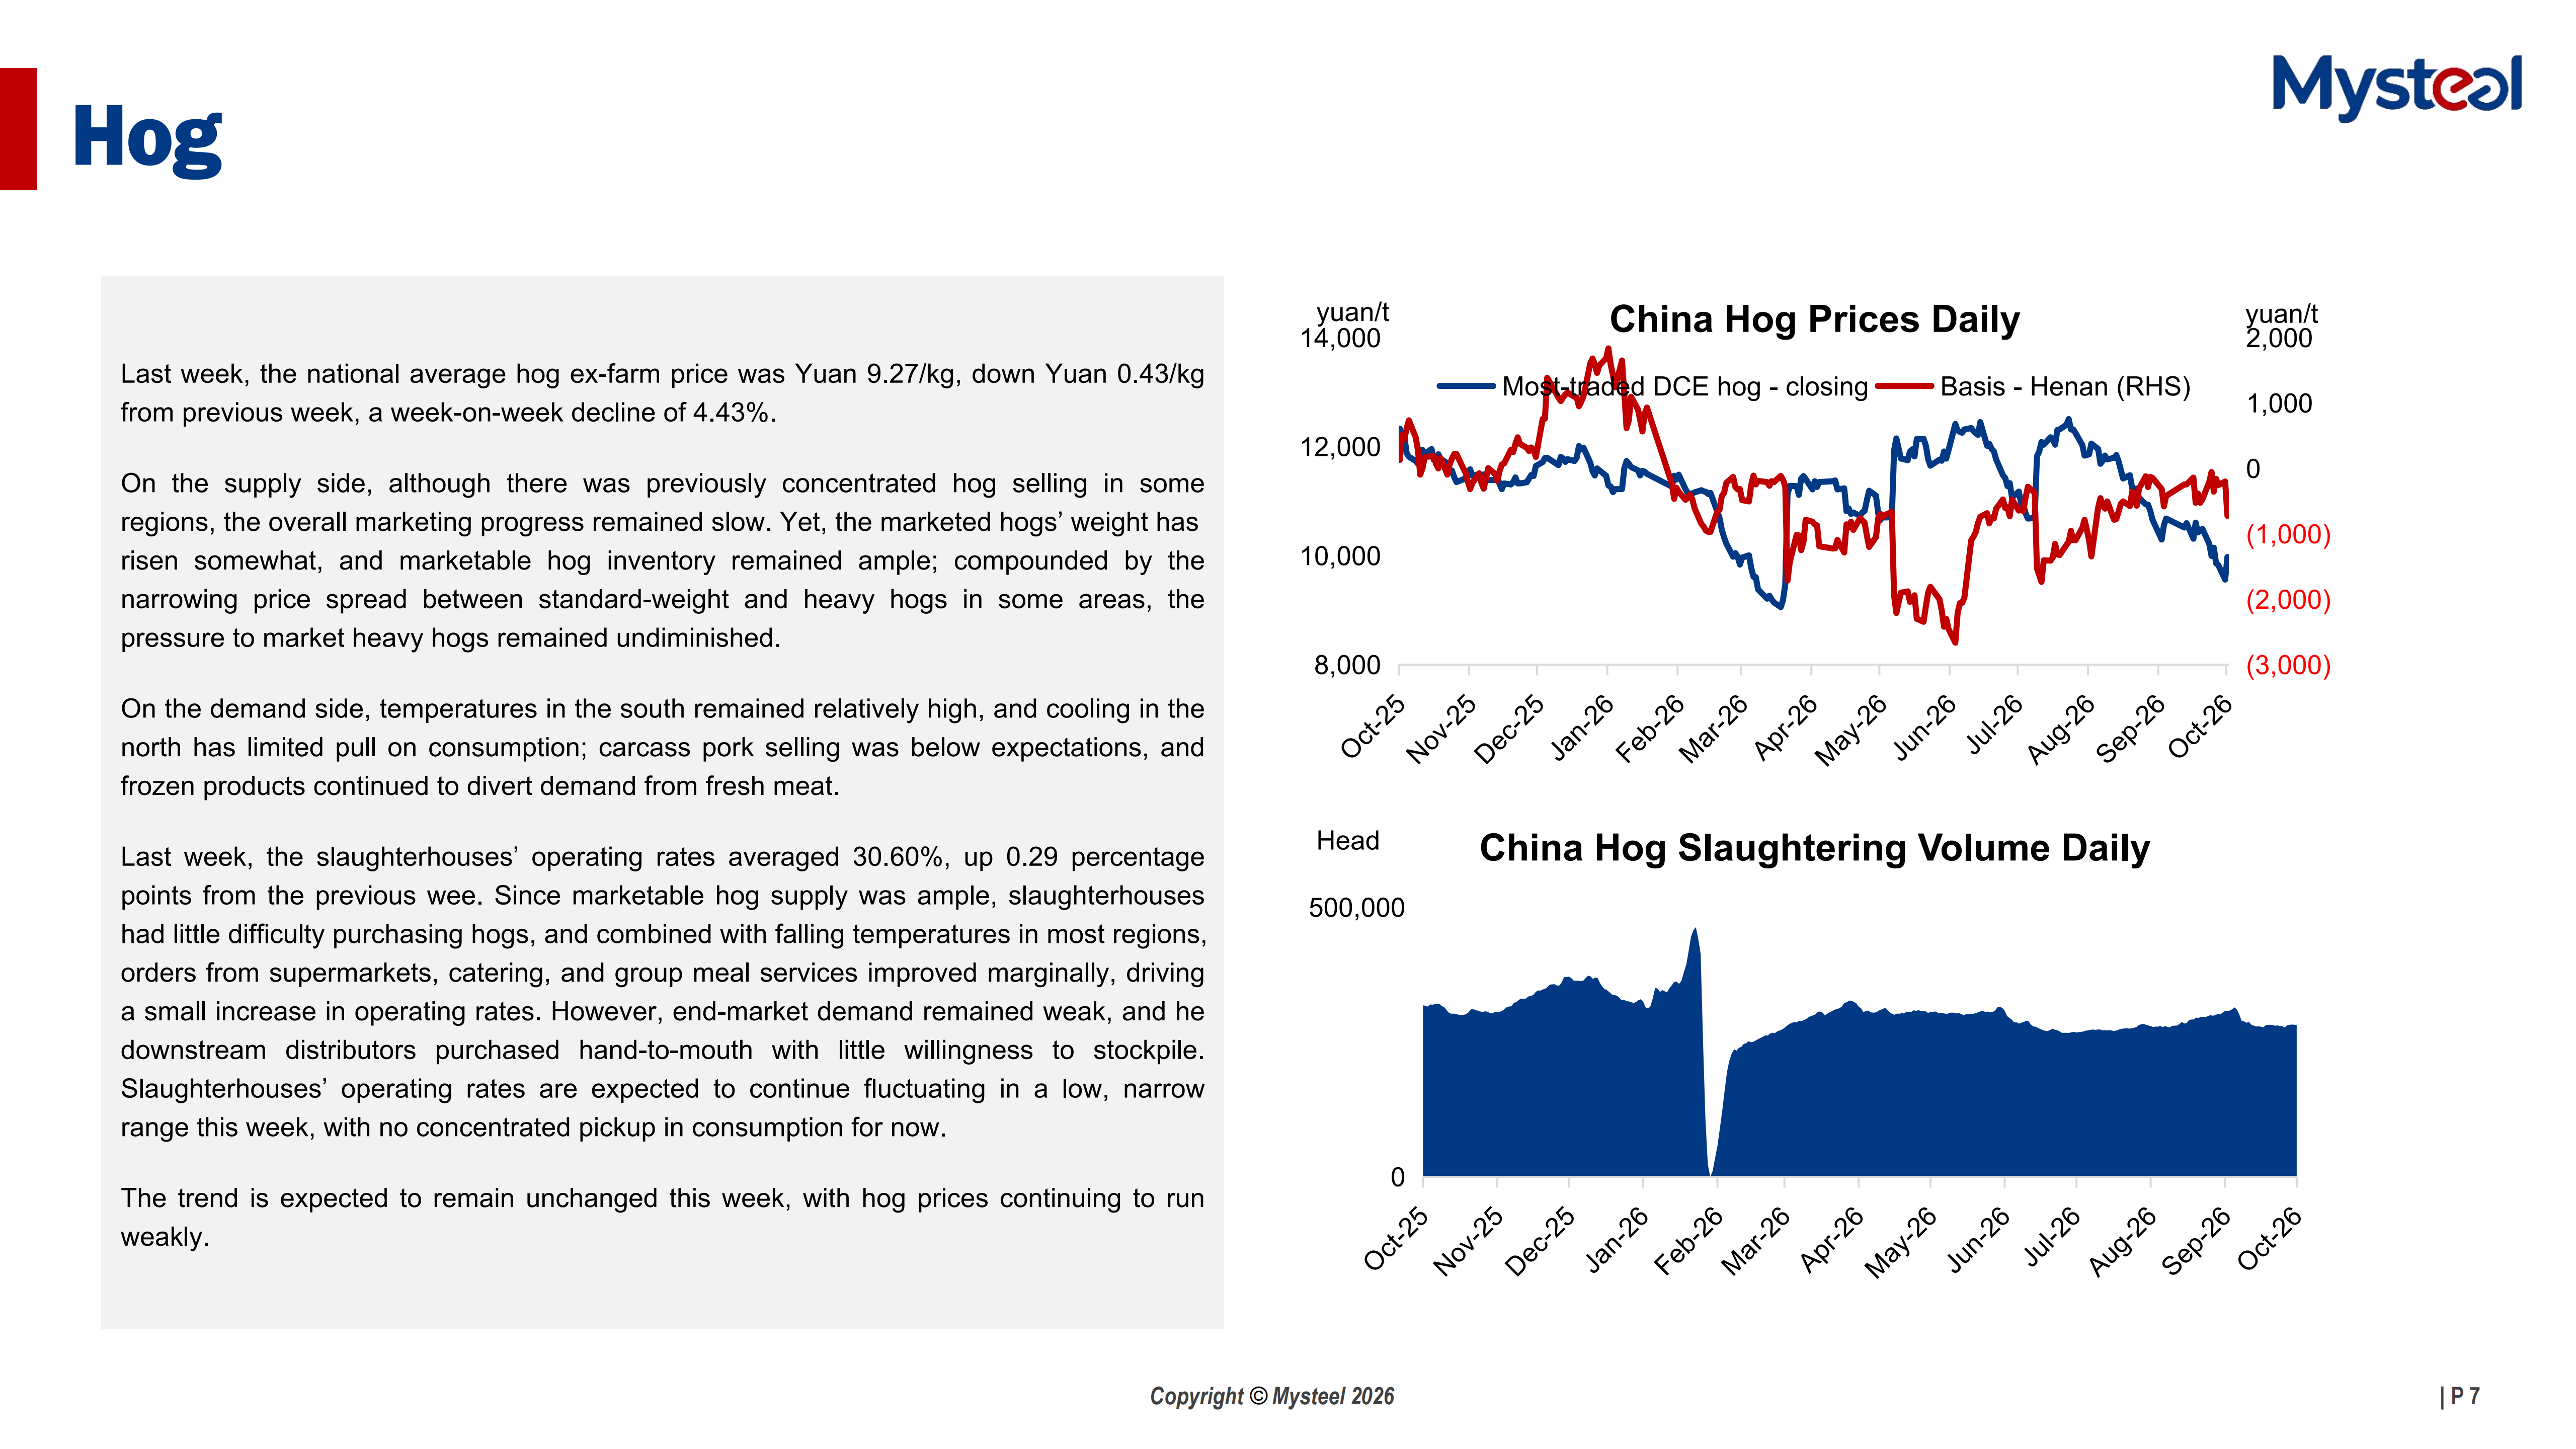
Hog: Hog supply has stayed ample and demand was soft, with high temperature in southern China and frozen goods displacing fresh meat. Slaughterhouses' operating rates edged up 0.29 pct to 30.60% but remained low. Hog prices are expected to stay weak.
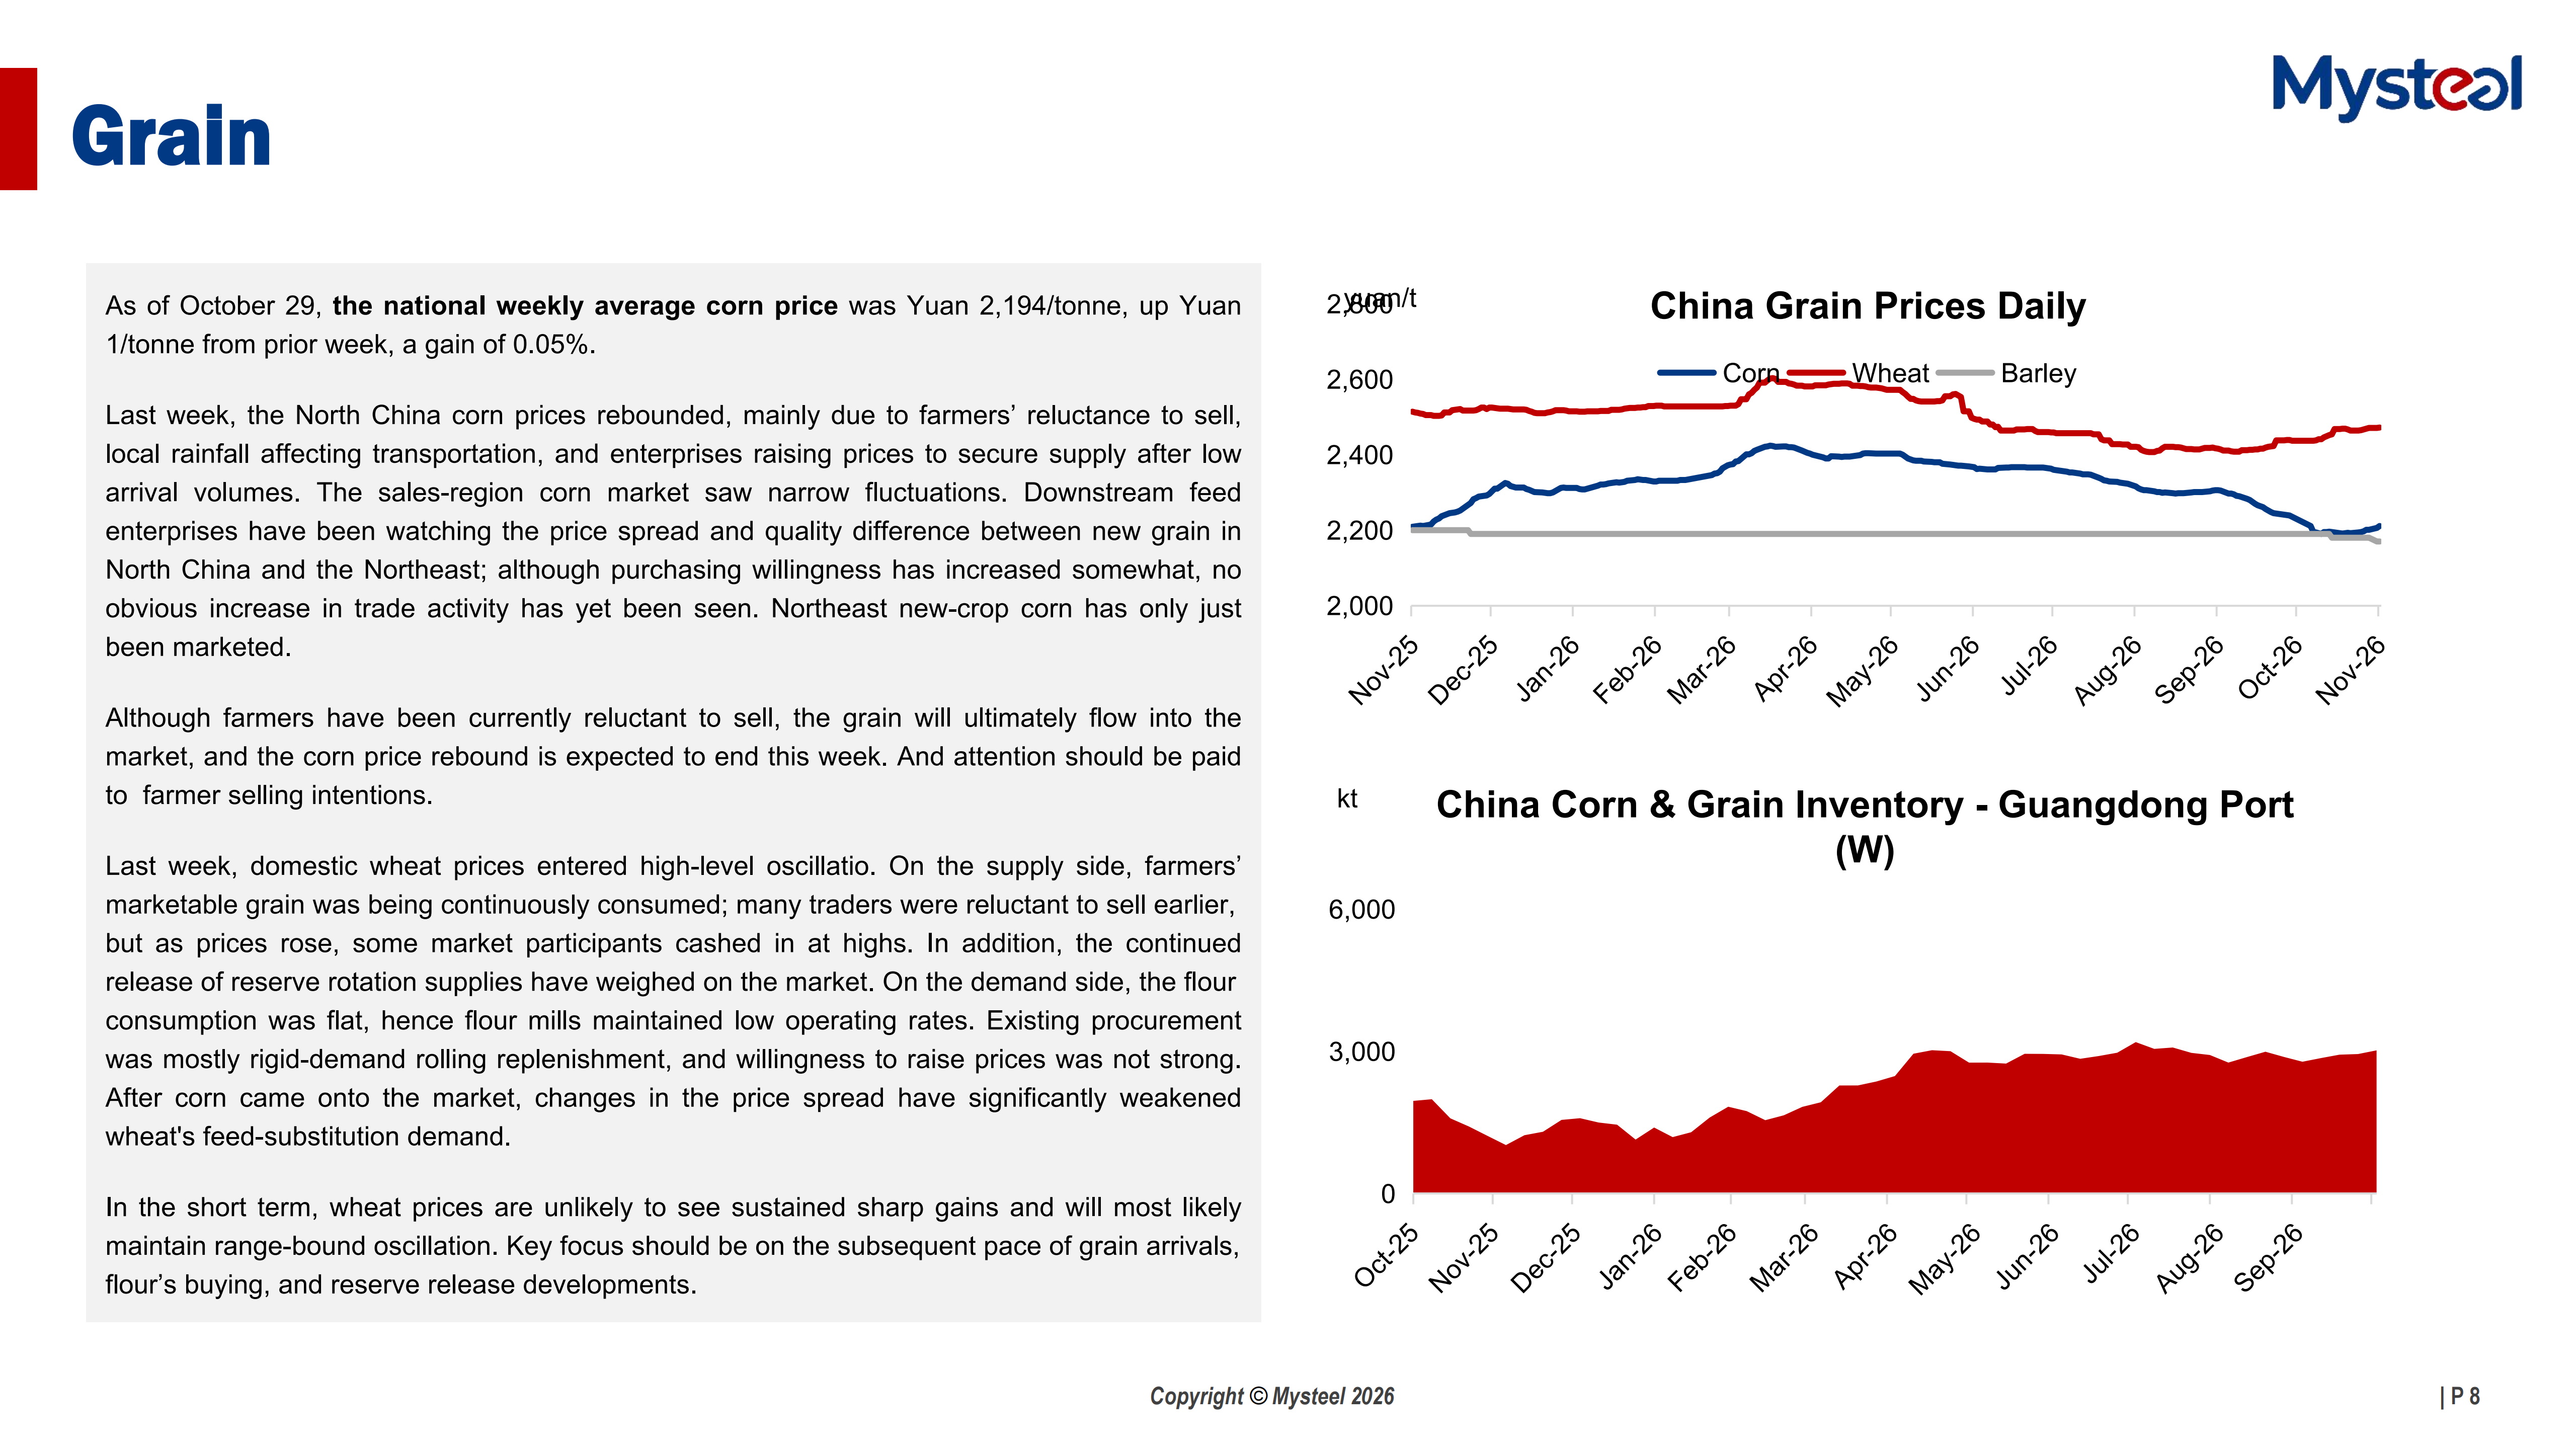
Grain: North China corn prices rebounded on farmers' reluctance to sell, rain-hit transport, and mills raising prices to secure arrivals. Feed demand showed no clear pickup. The rebound is expected to fade this week as new-crop grain flows to market.
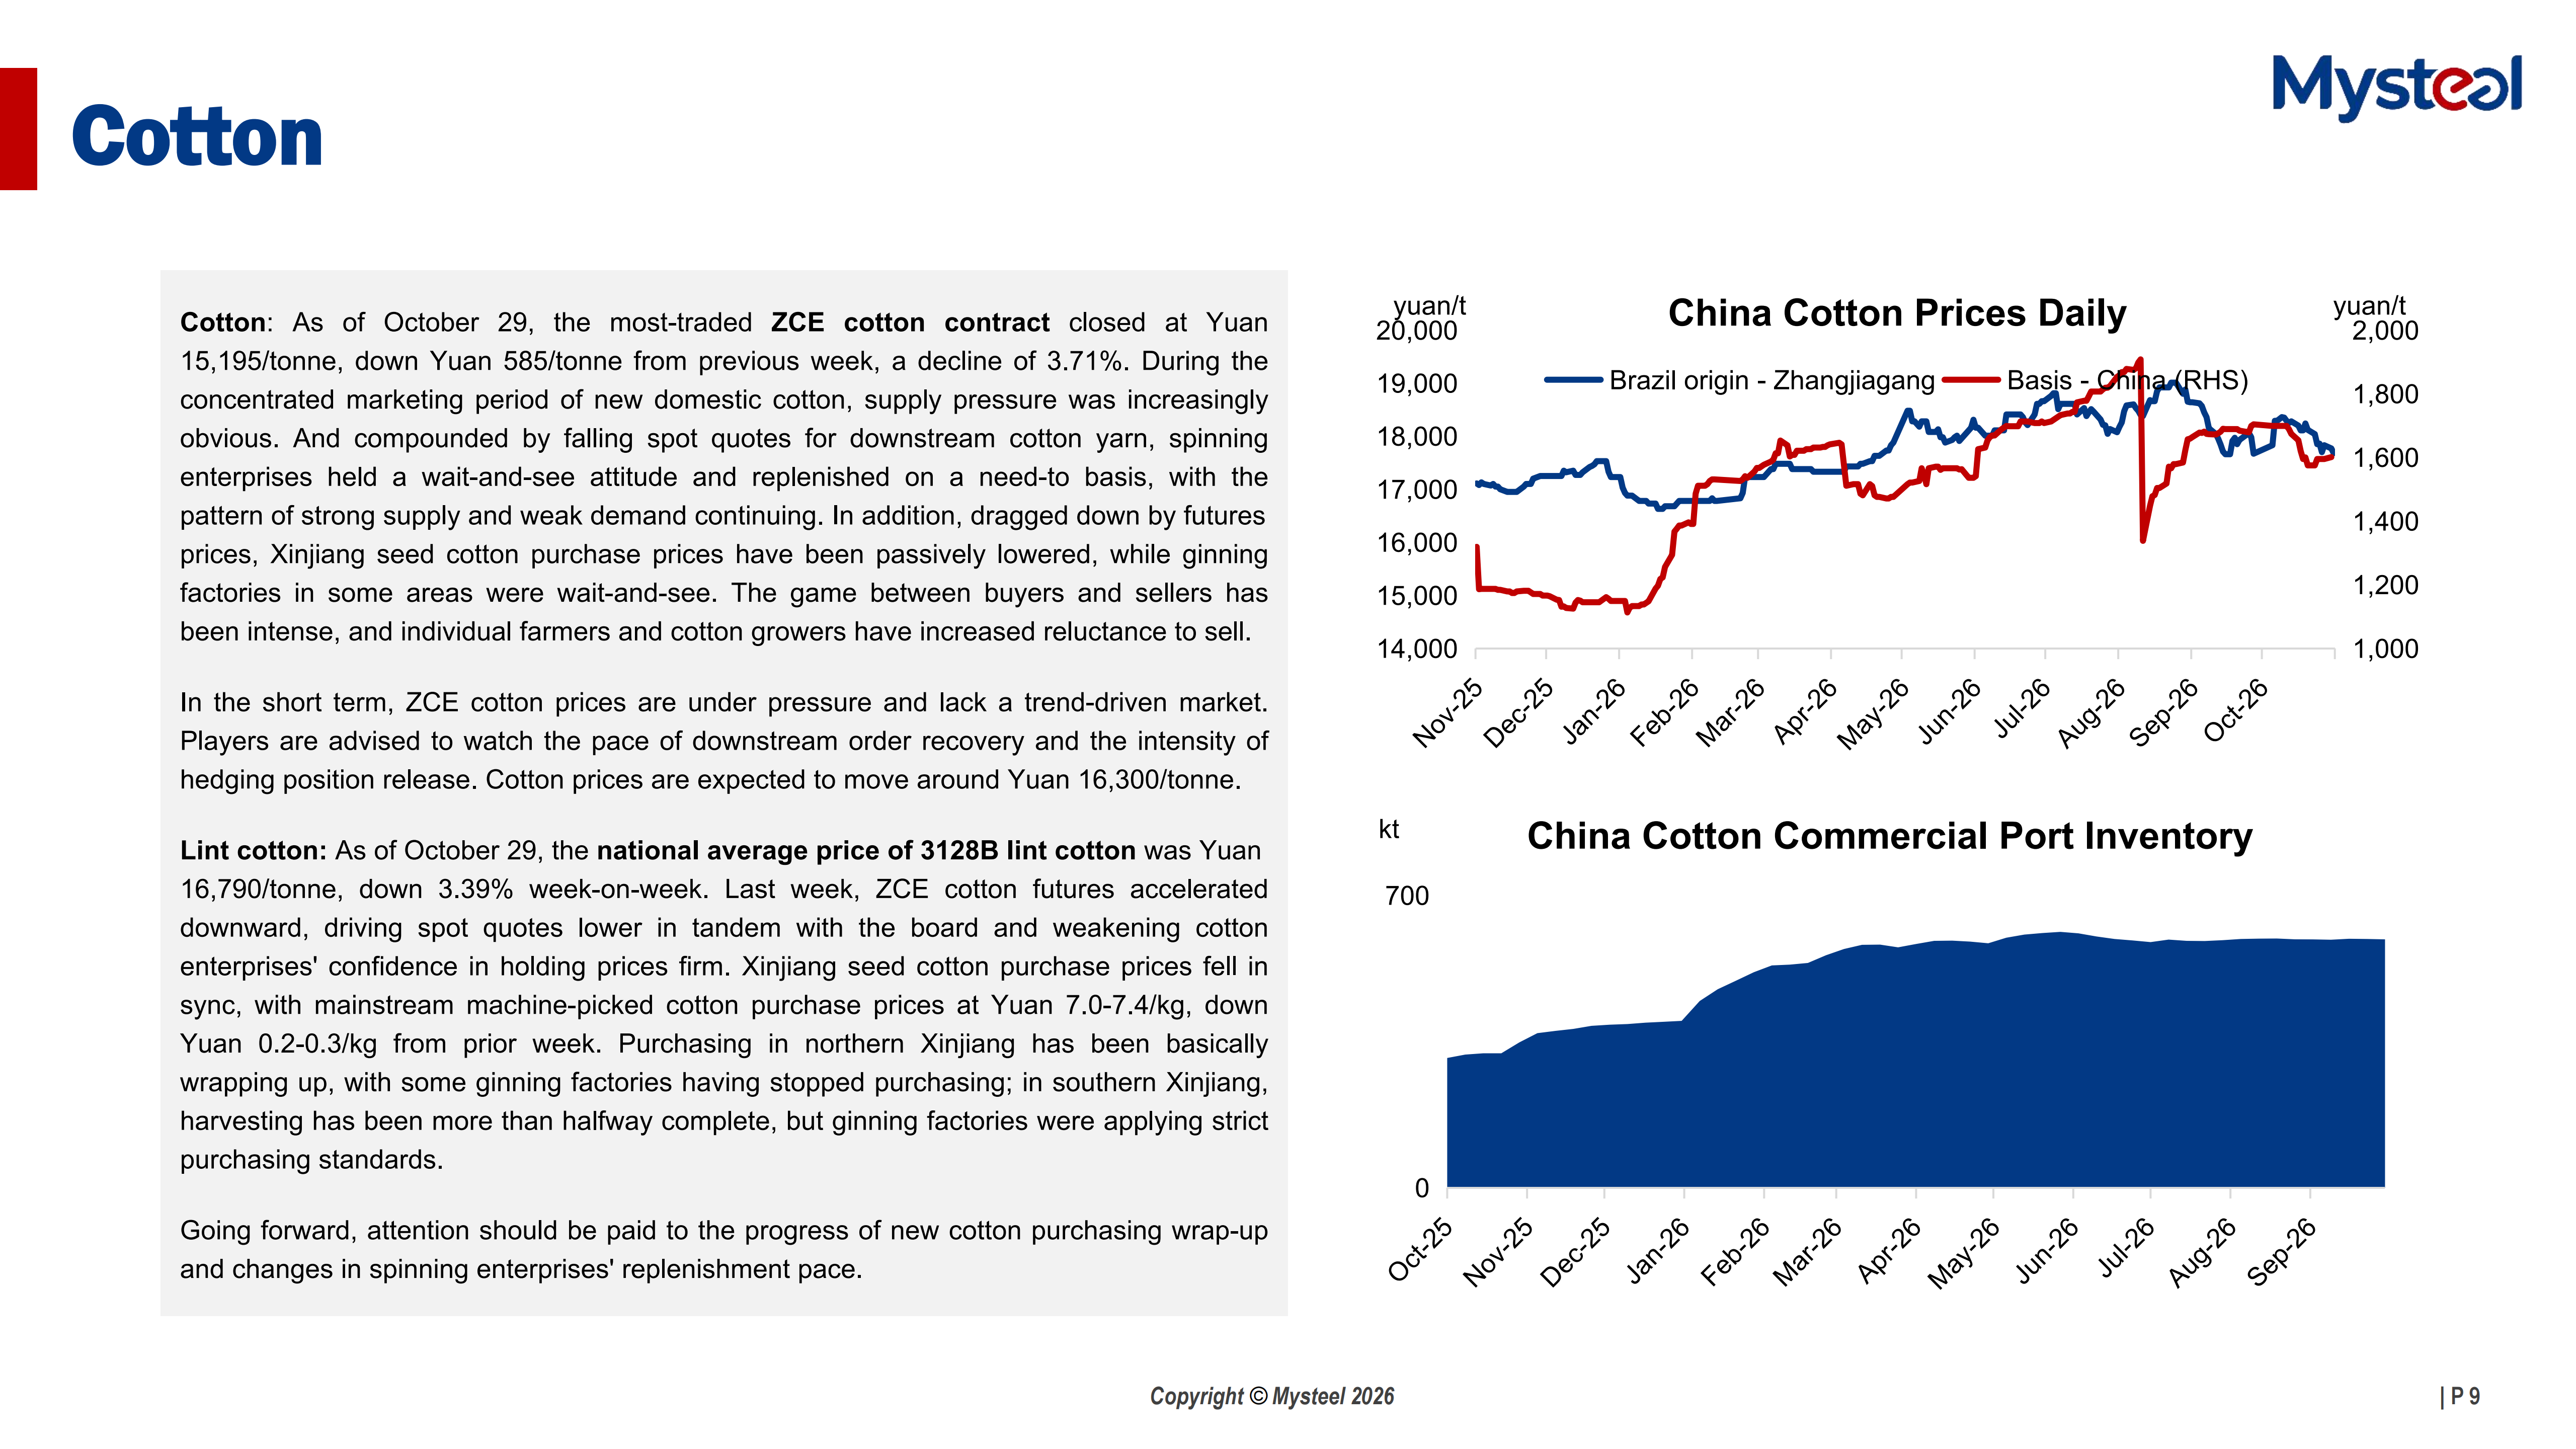
Cotton: Heavy new-crop cotton supply weighed on yarn quotes and spinning mills purchased only as needed, keeping supply strong and demand weak. Cotton price are expected to run at around Yuan 16,300/tonne; watch downstream orders and hedging activity.