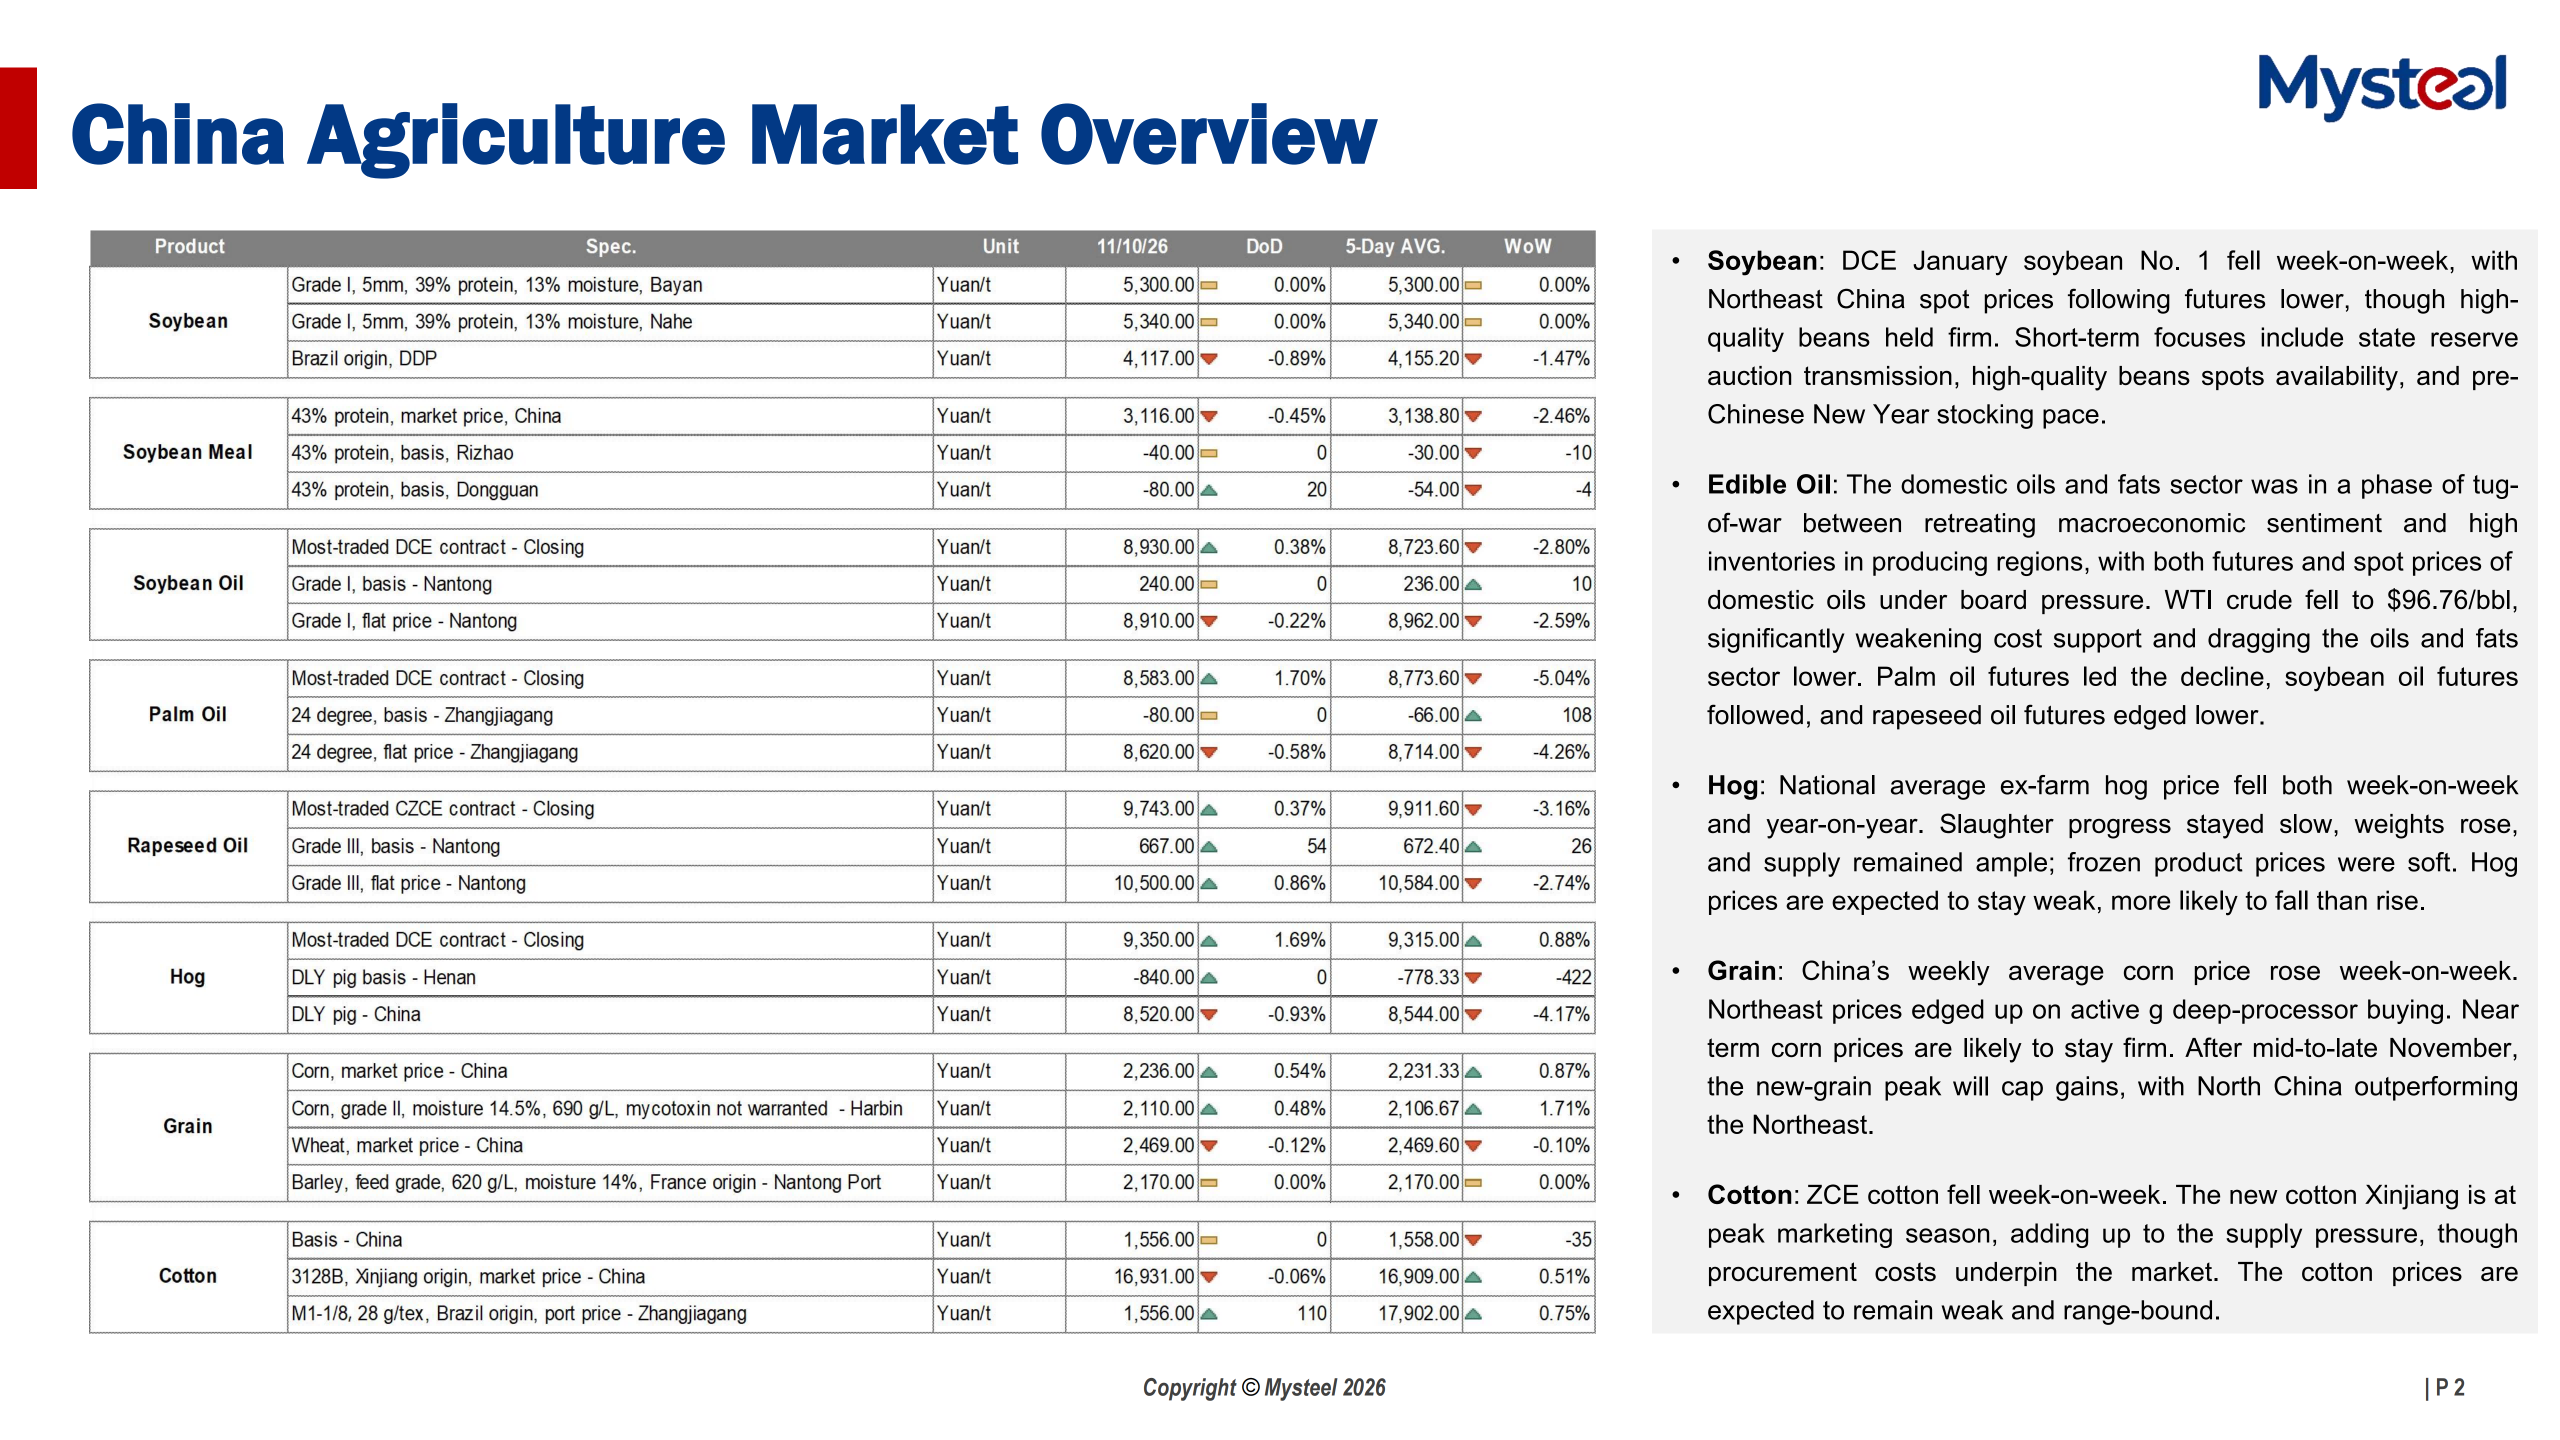
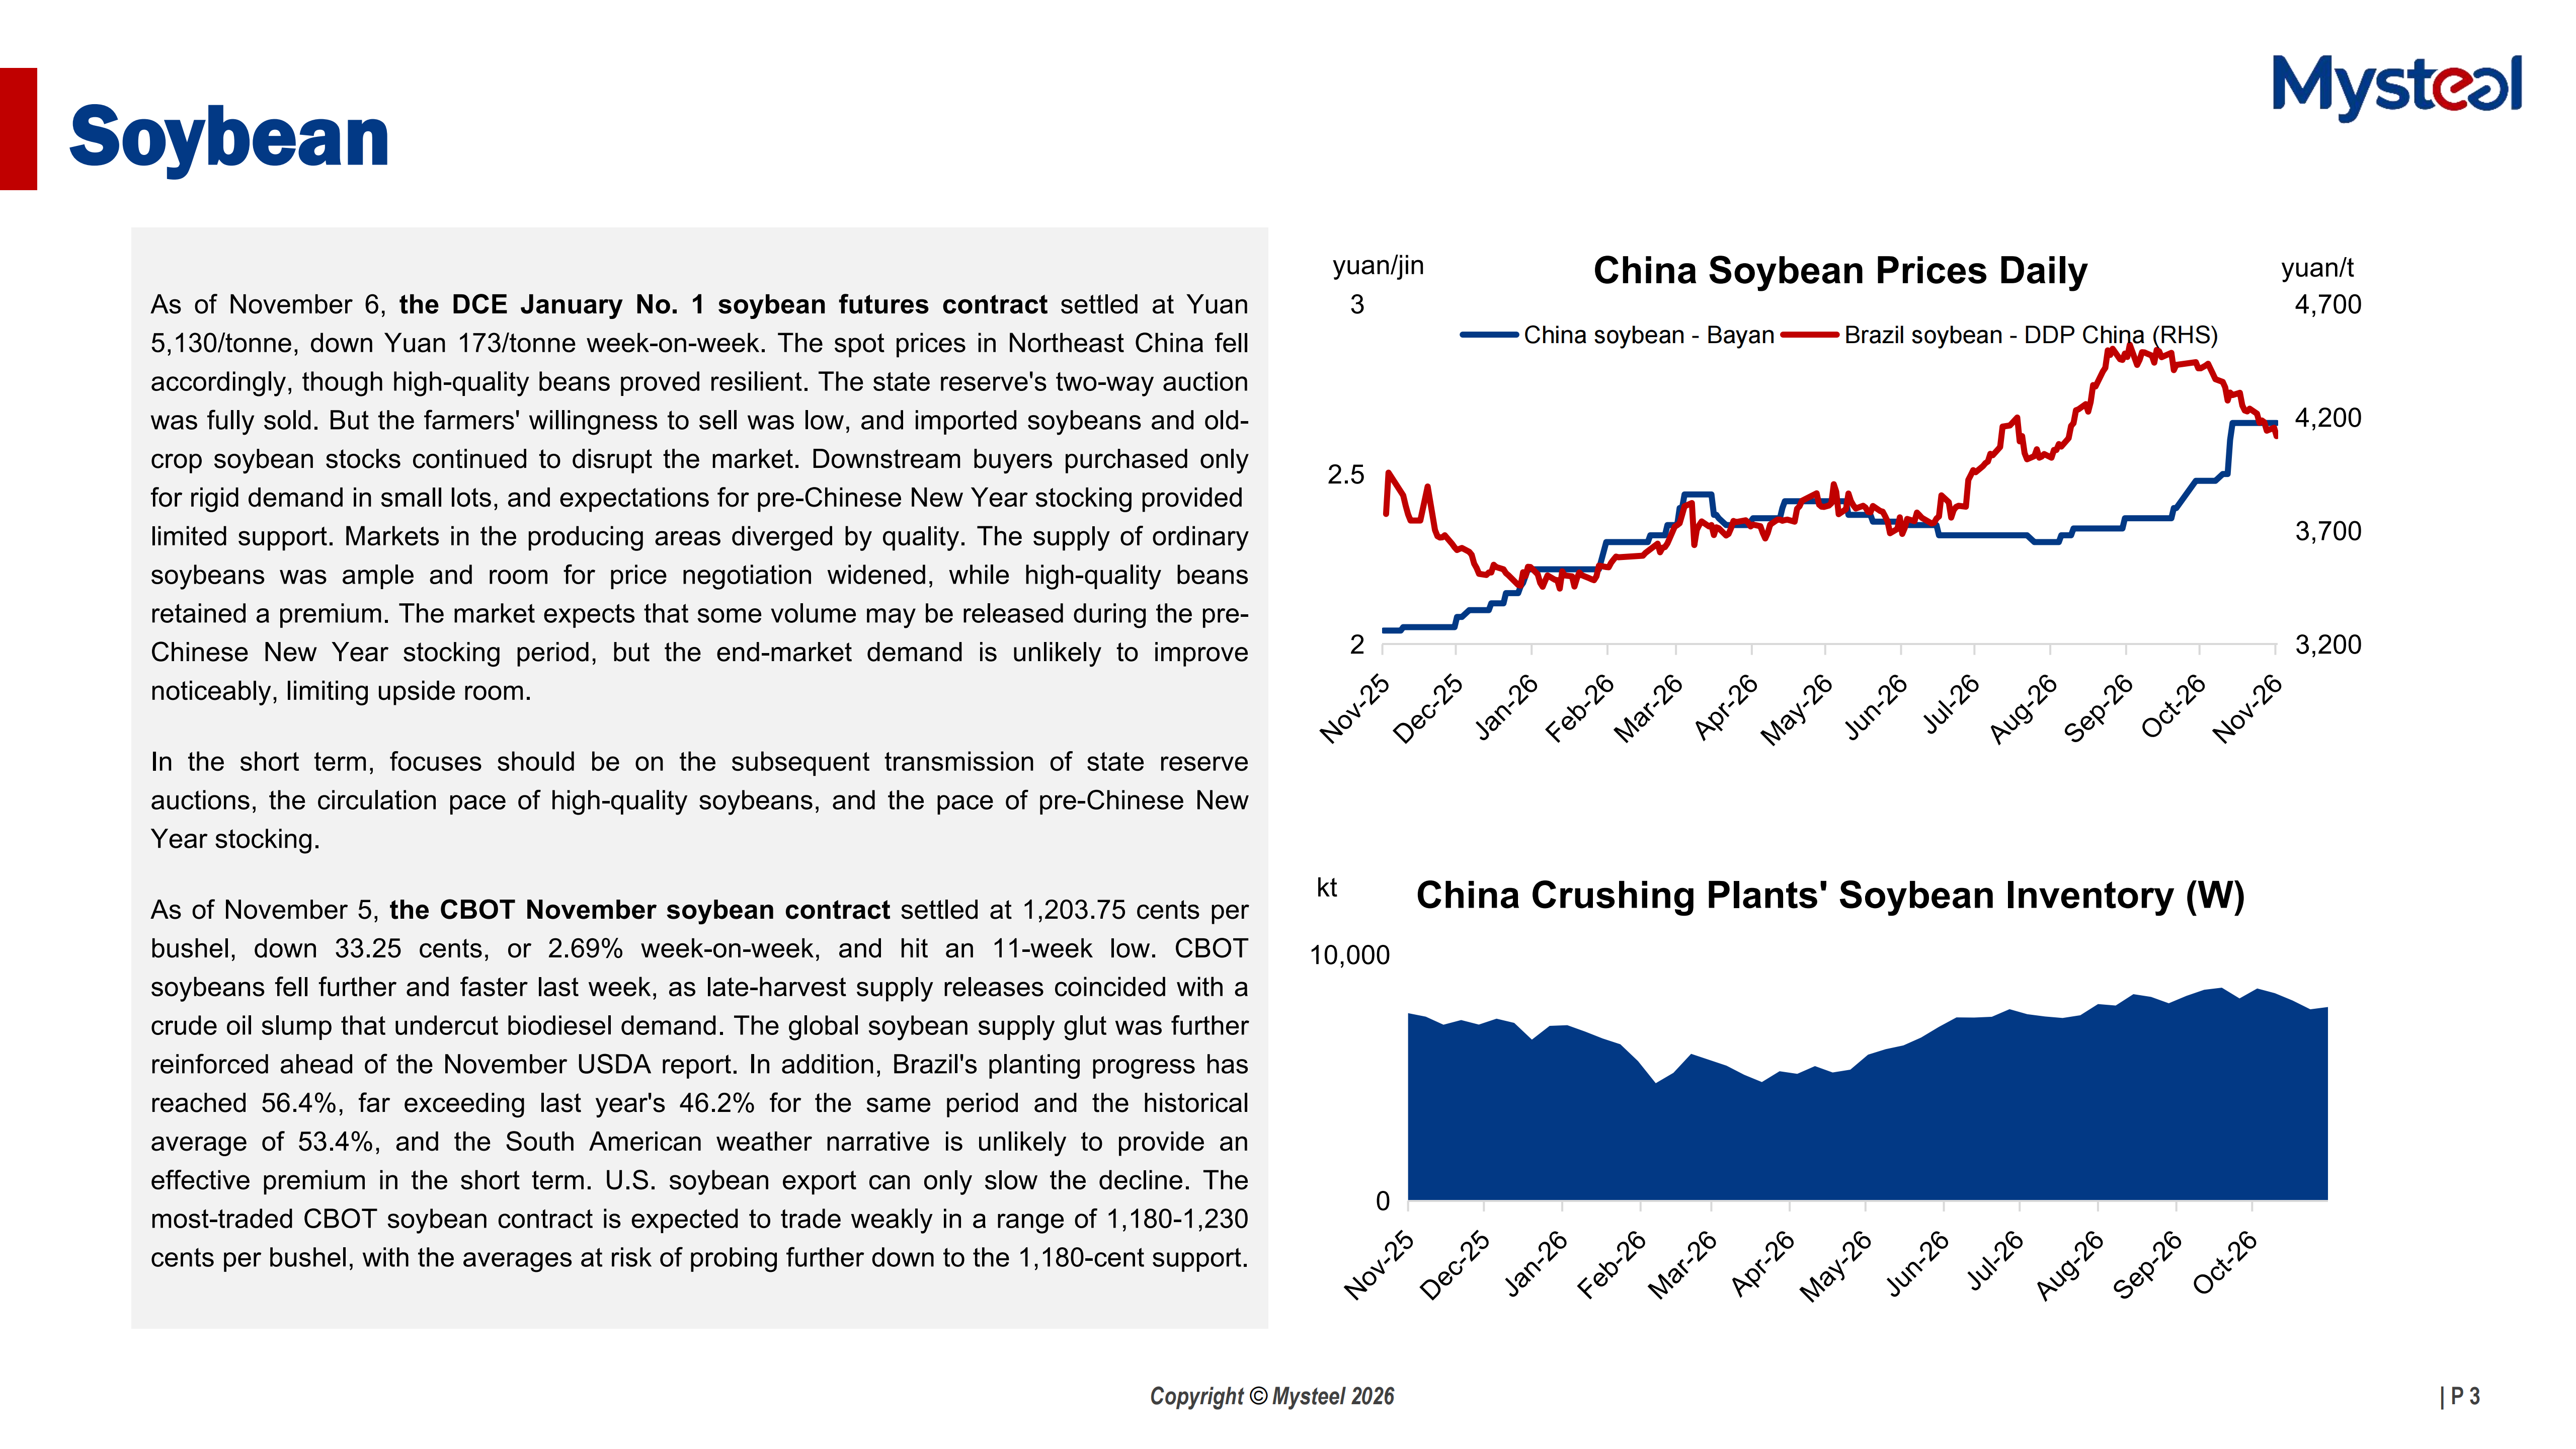
Soybean: DCE January soybean No. 1 fell week-on-week, with Northeast China spot prices following futures lower, though high-quality beans held firm. Short-term focuses include state reserve auction transmission, high-quality beans spots availability, and pre-Chinese New Year stocking pace.
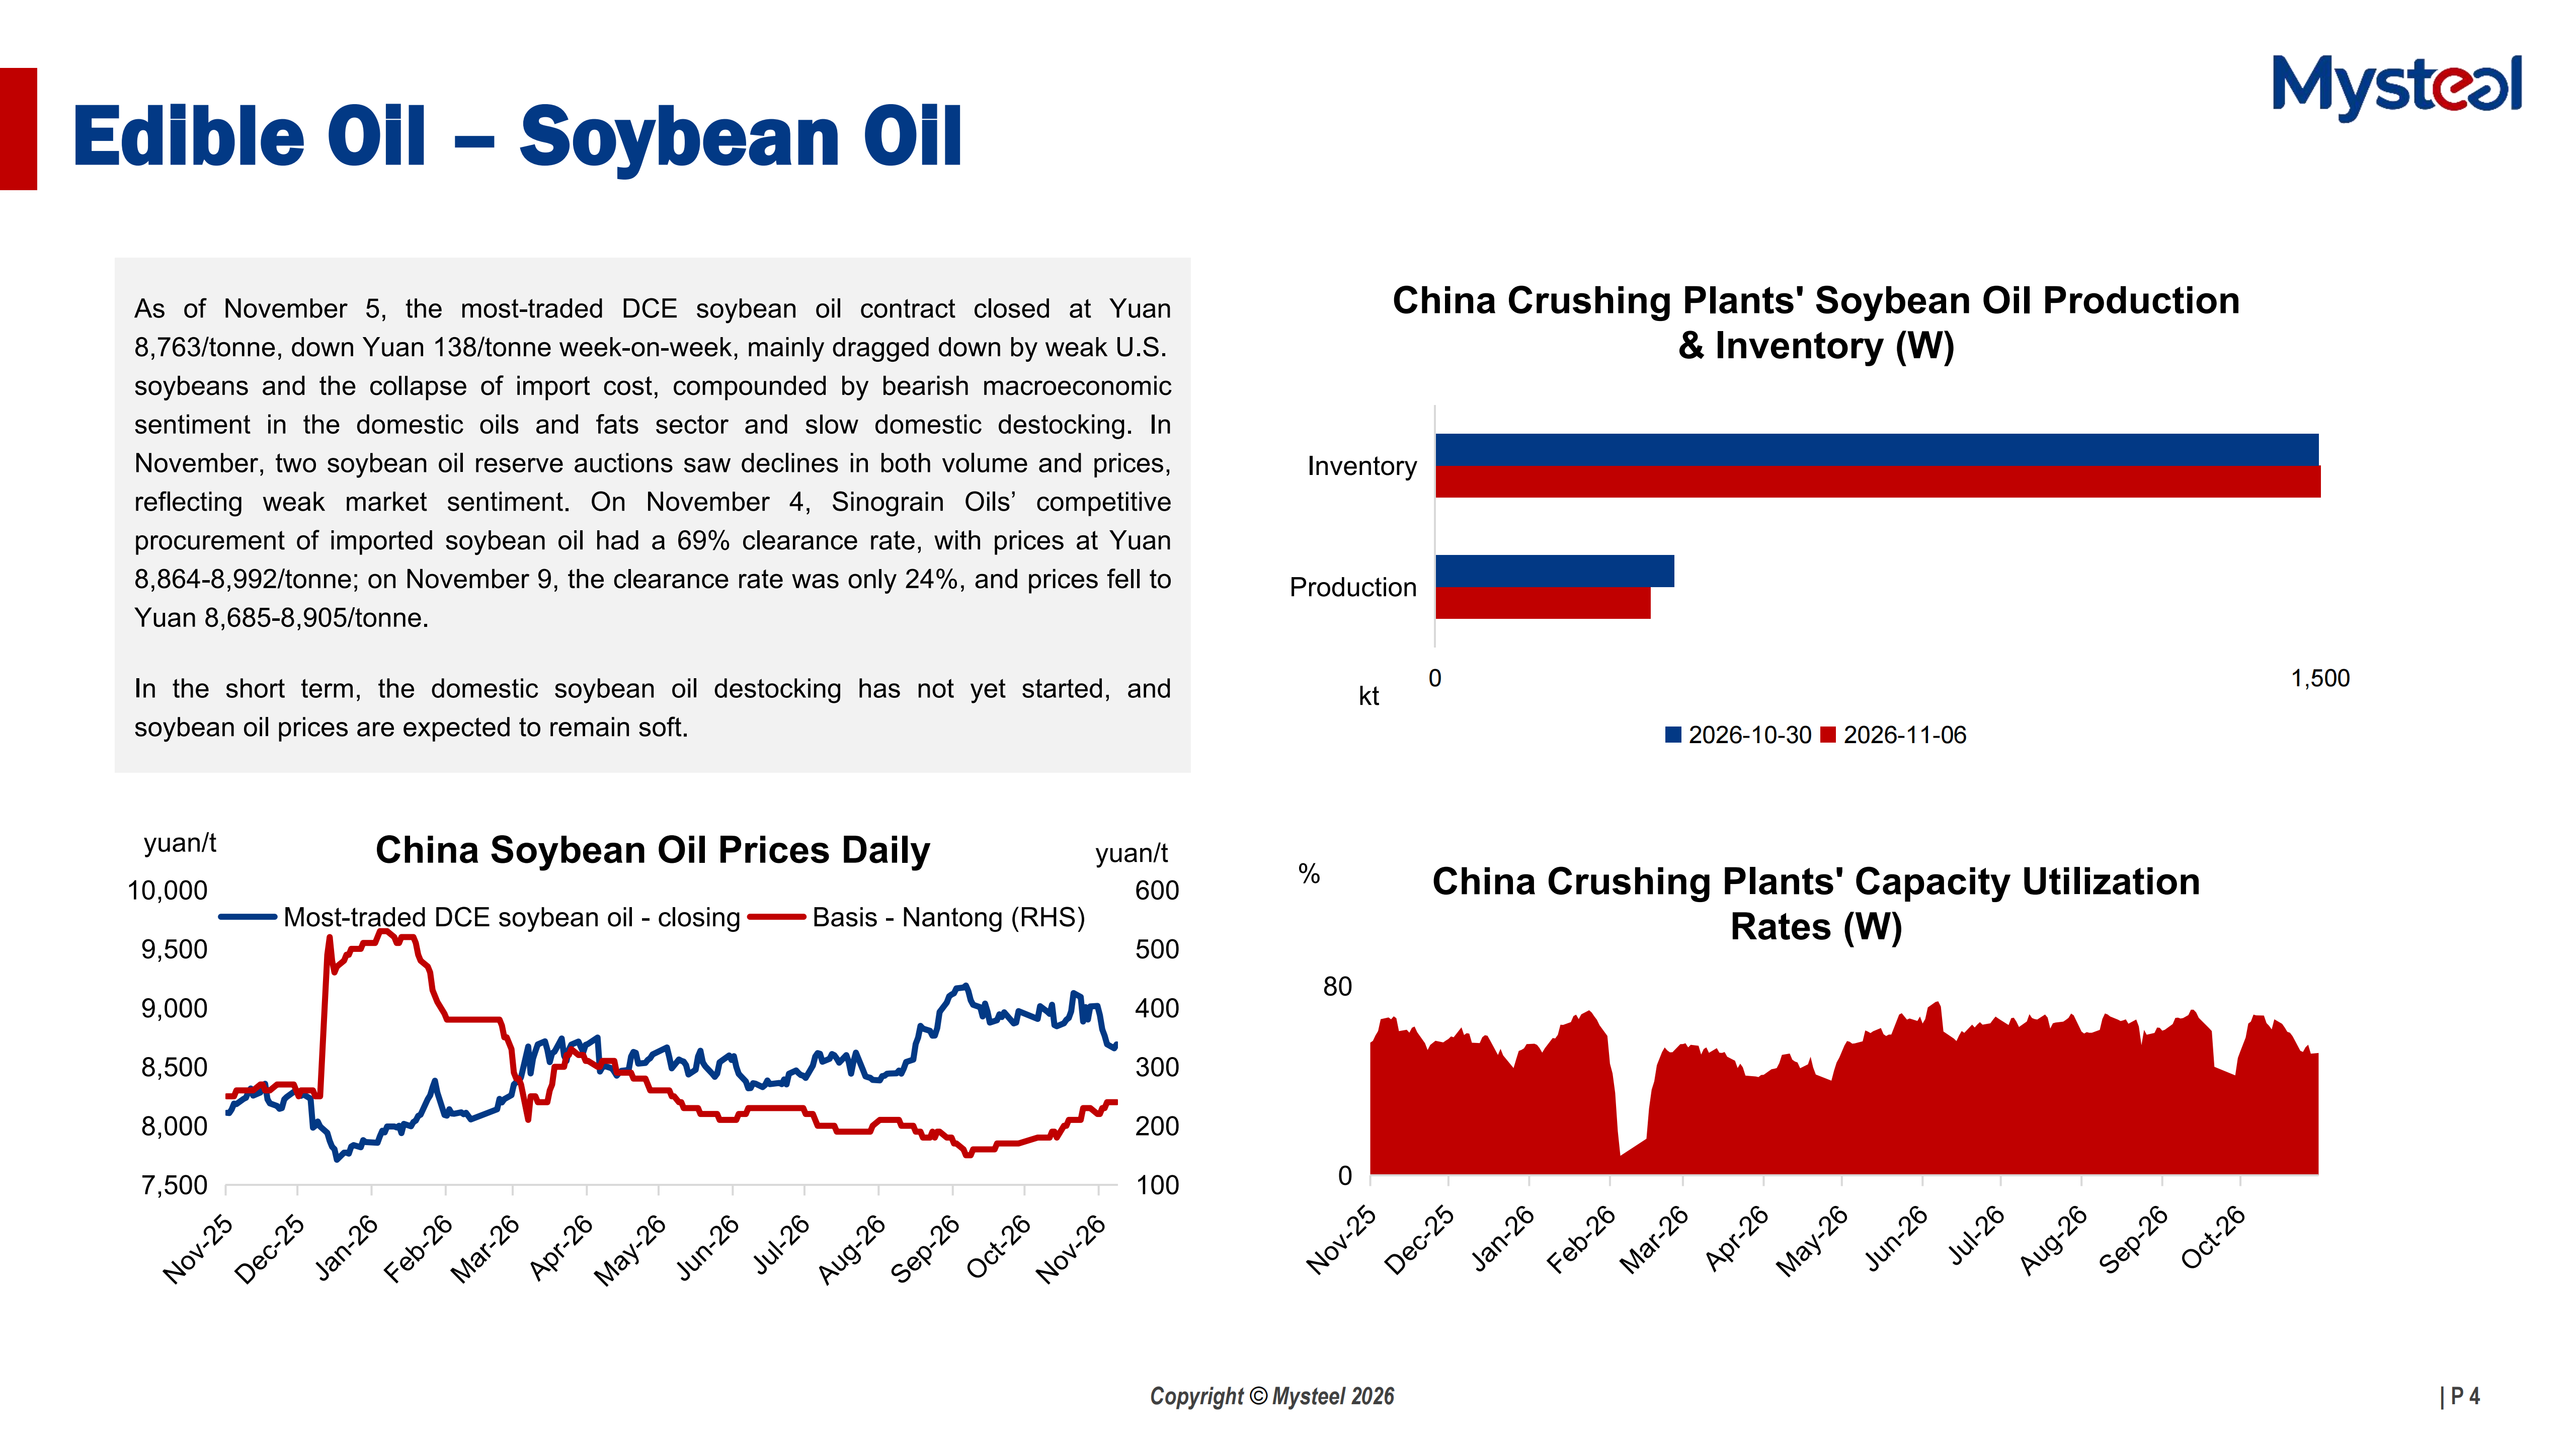
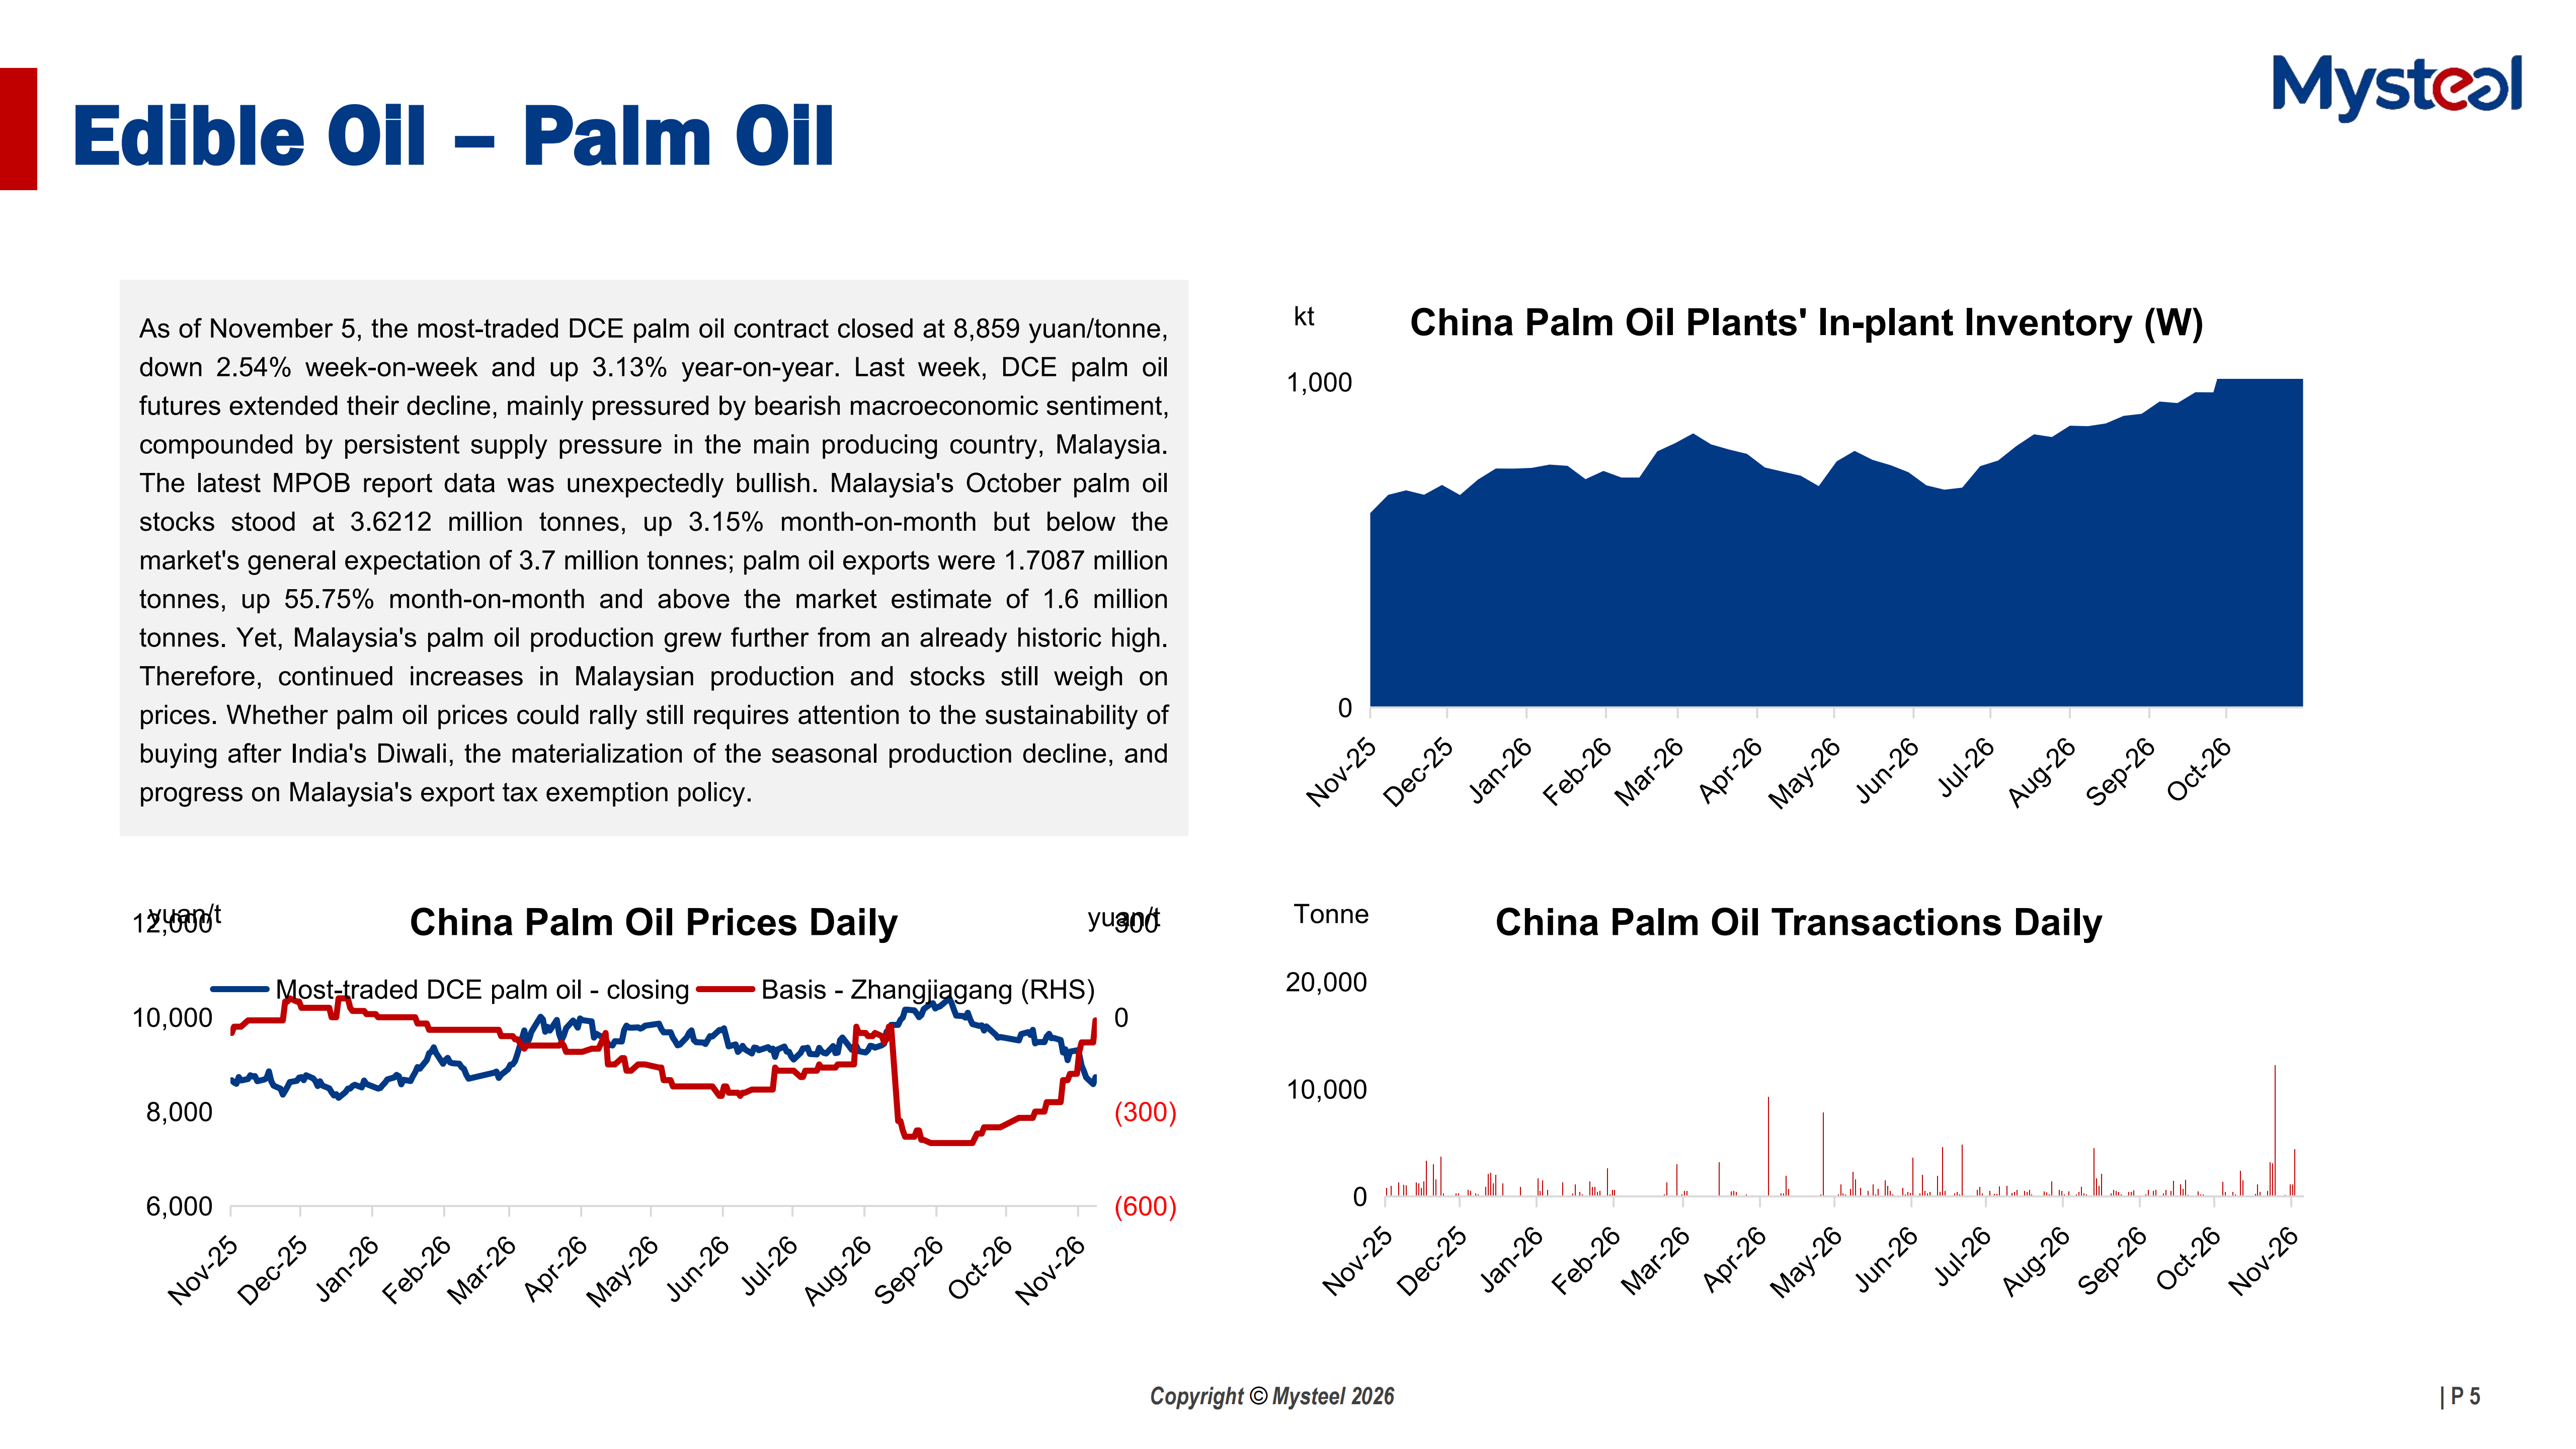
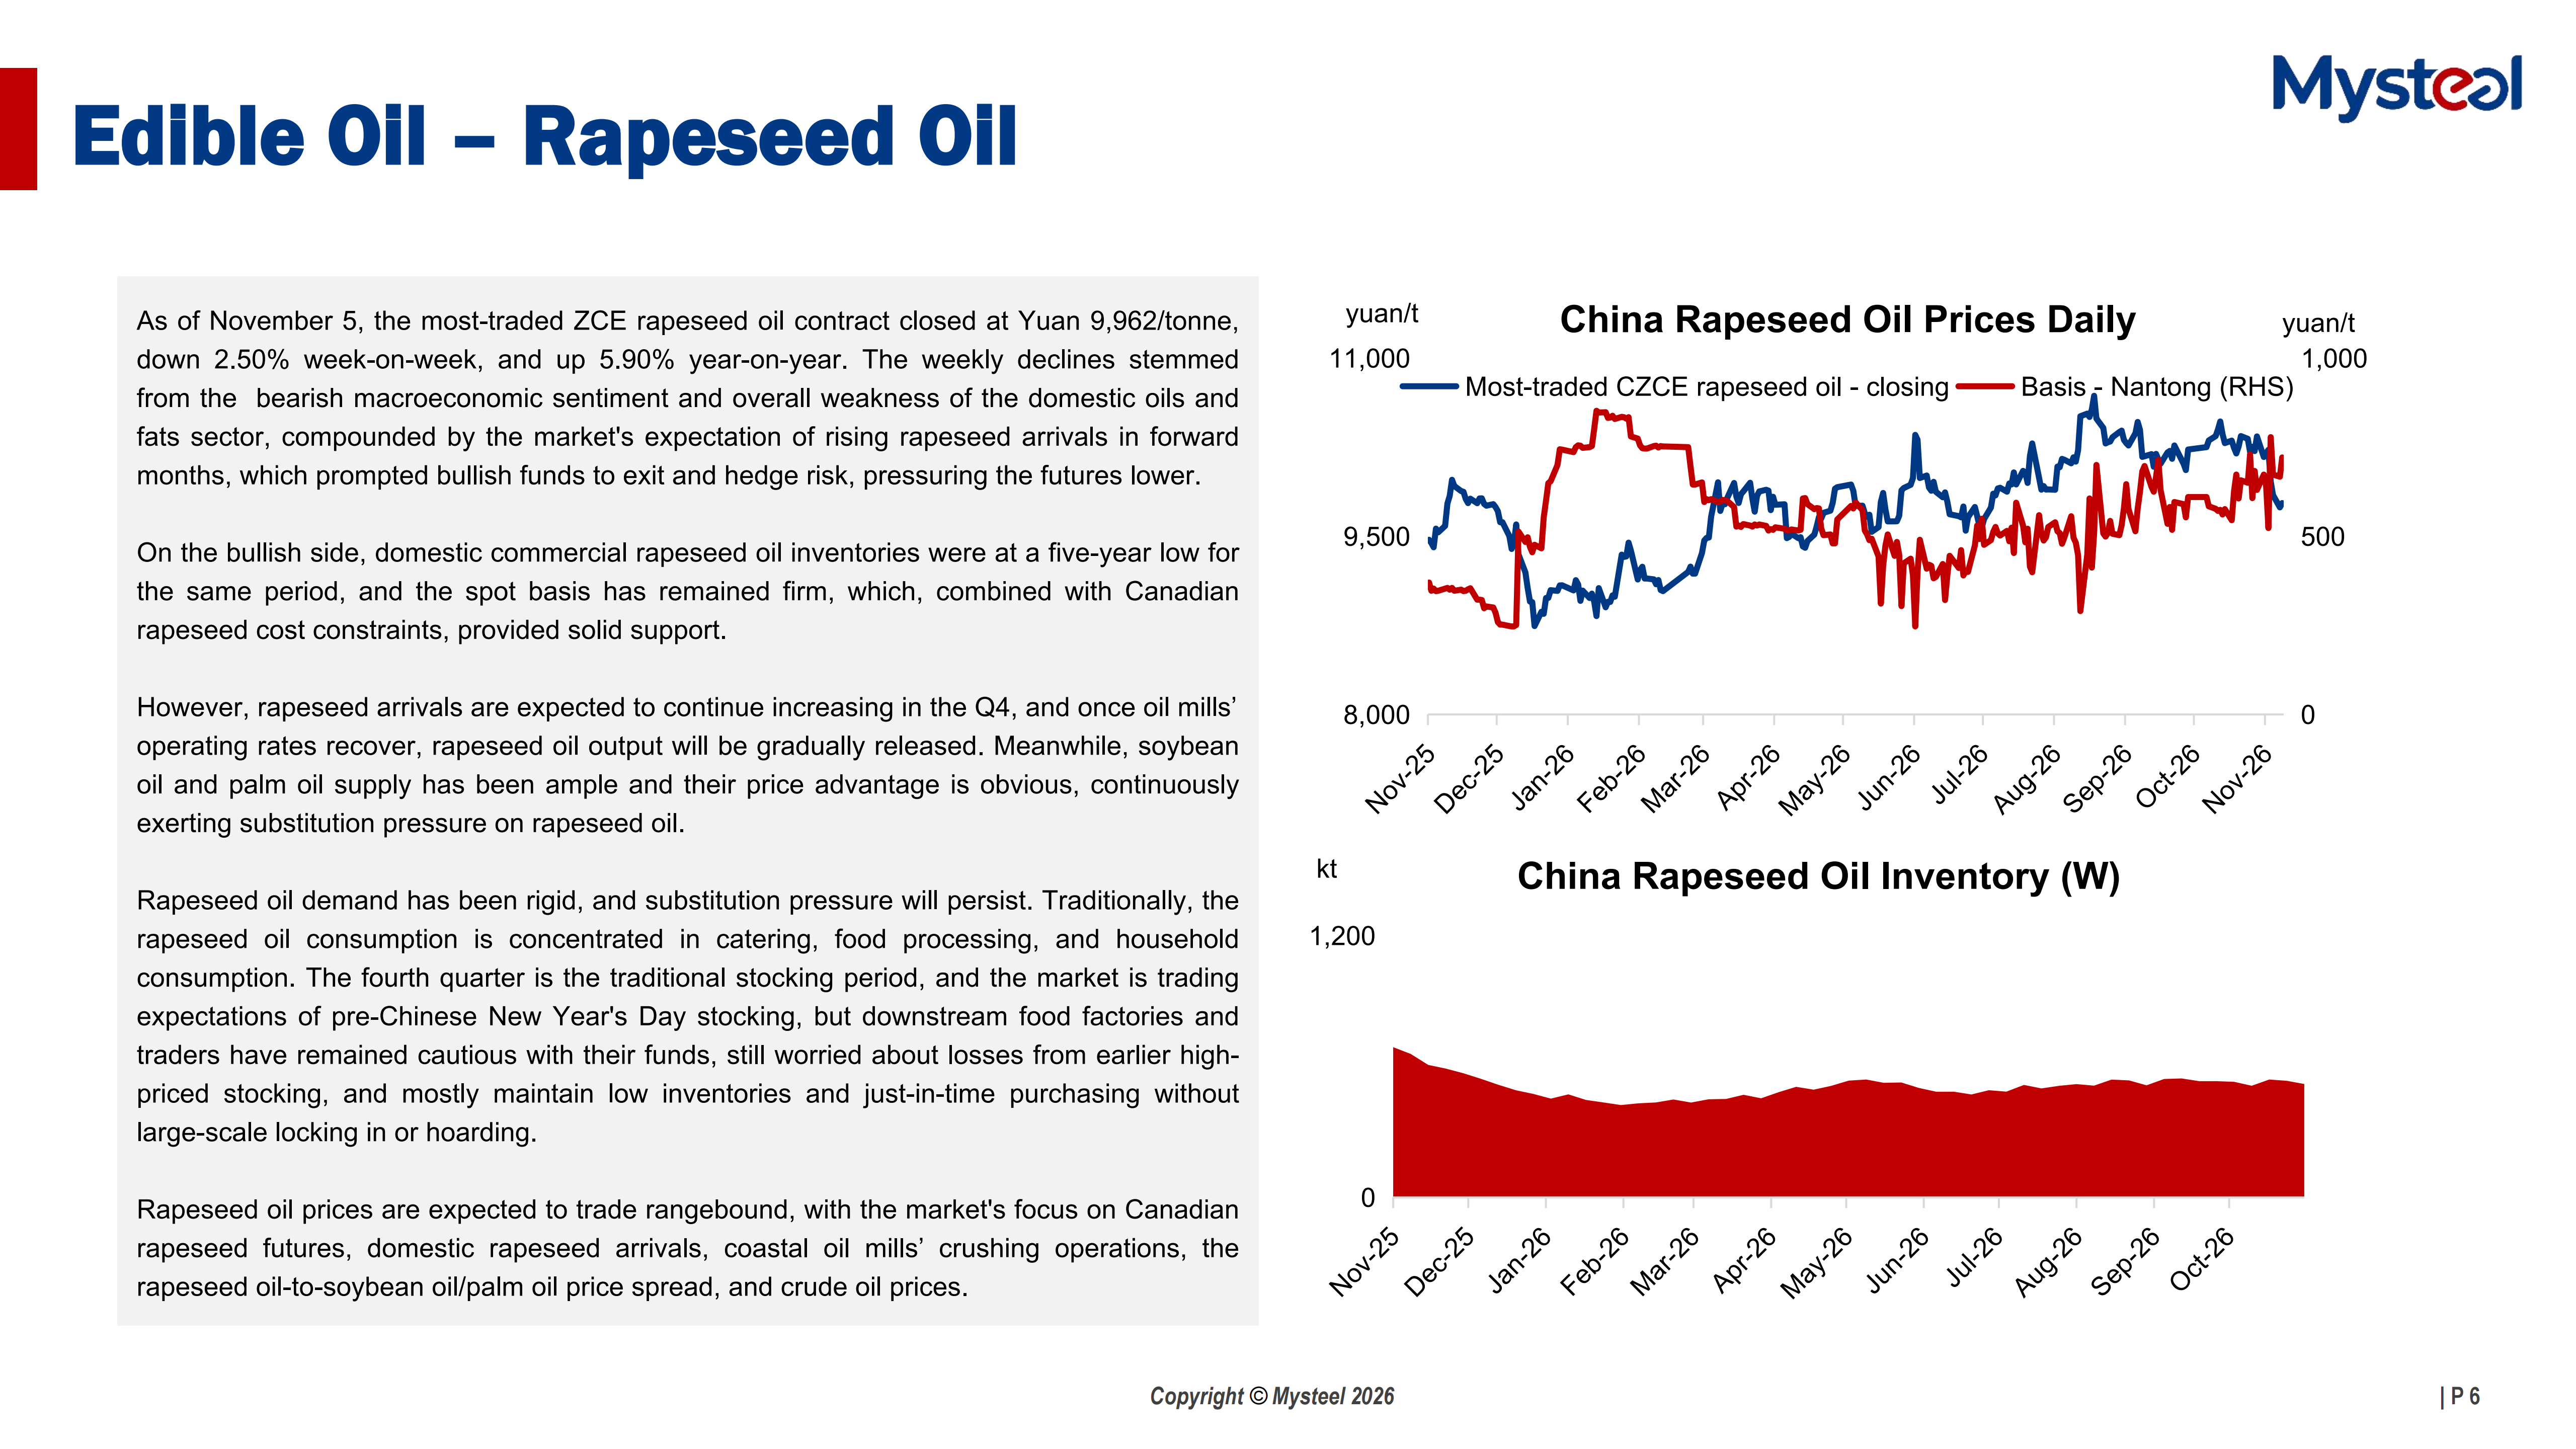
Edible Oil: The domestic oils and fats sector was in a phase of tug-of-war between retreating macroeconomic sentiment and high inventories in producing regions, with both futures and spot prices of domestic oils under board pressure. WTI crude fell to $96.76/bbl, significantly weakening cost support and dragging the oils and fats sector lower. Palm oil futures led the decline, soybean oil futures followed, and rapeseed oil futures edged lower.
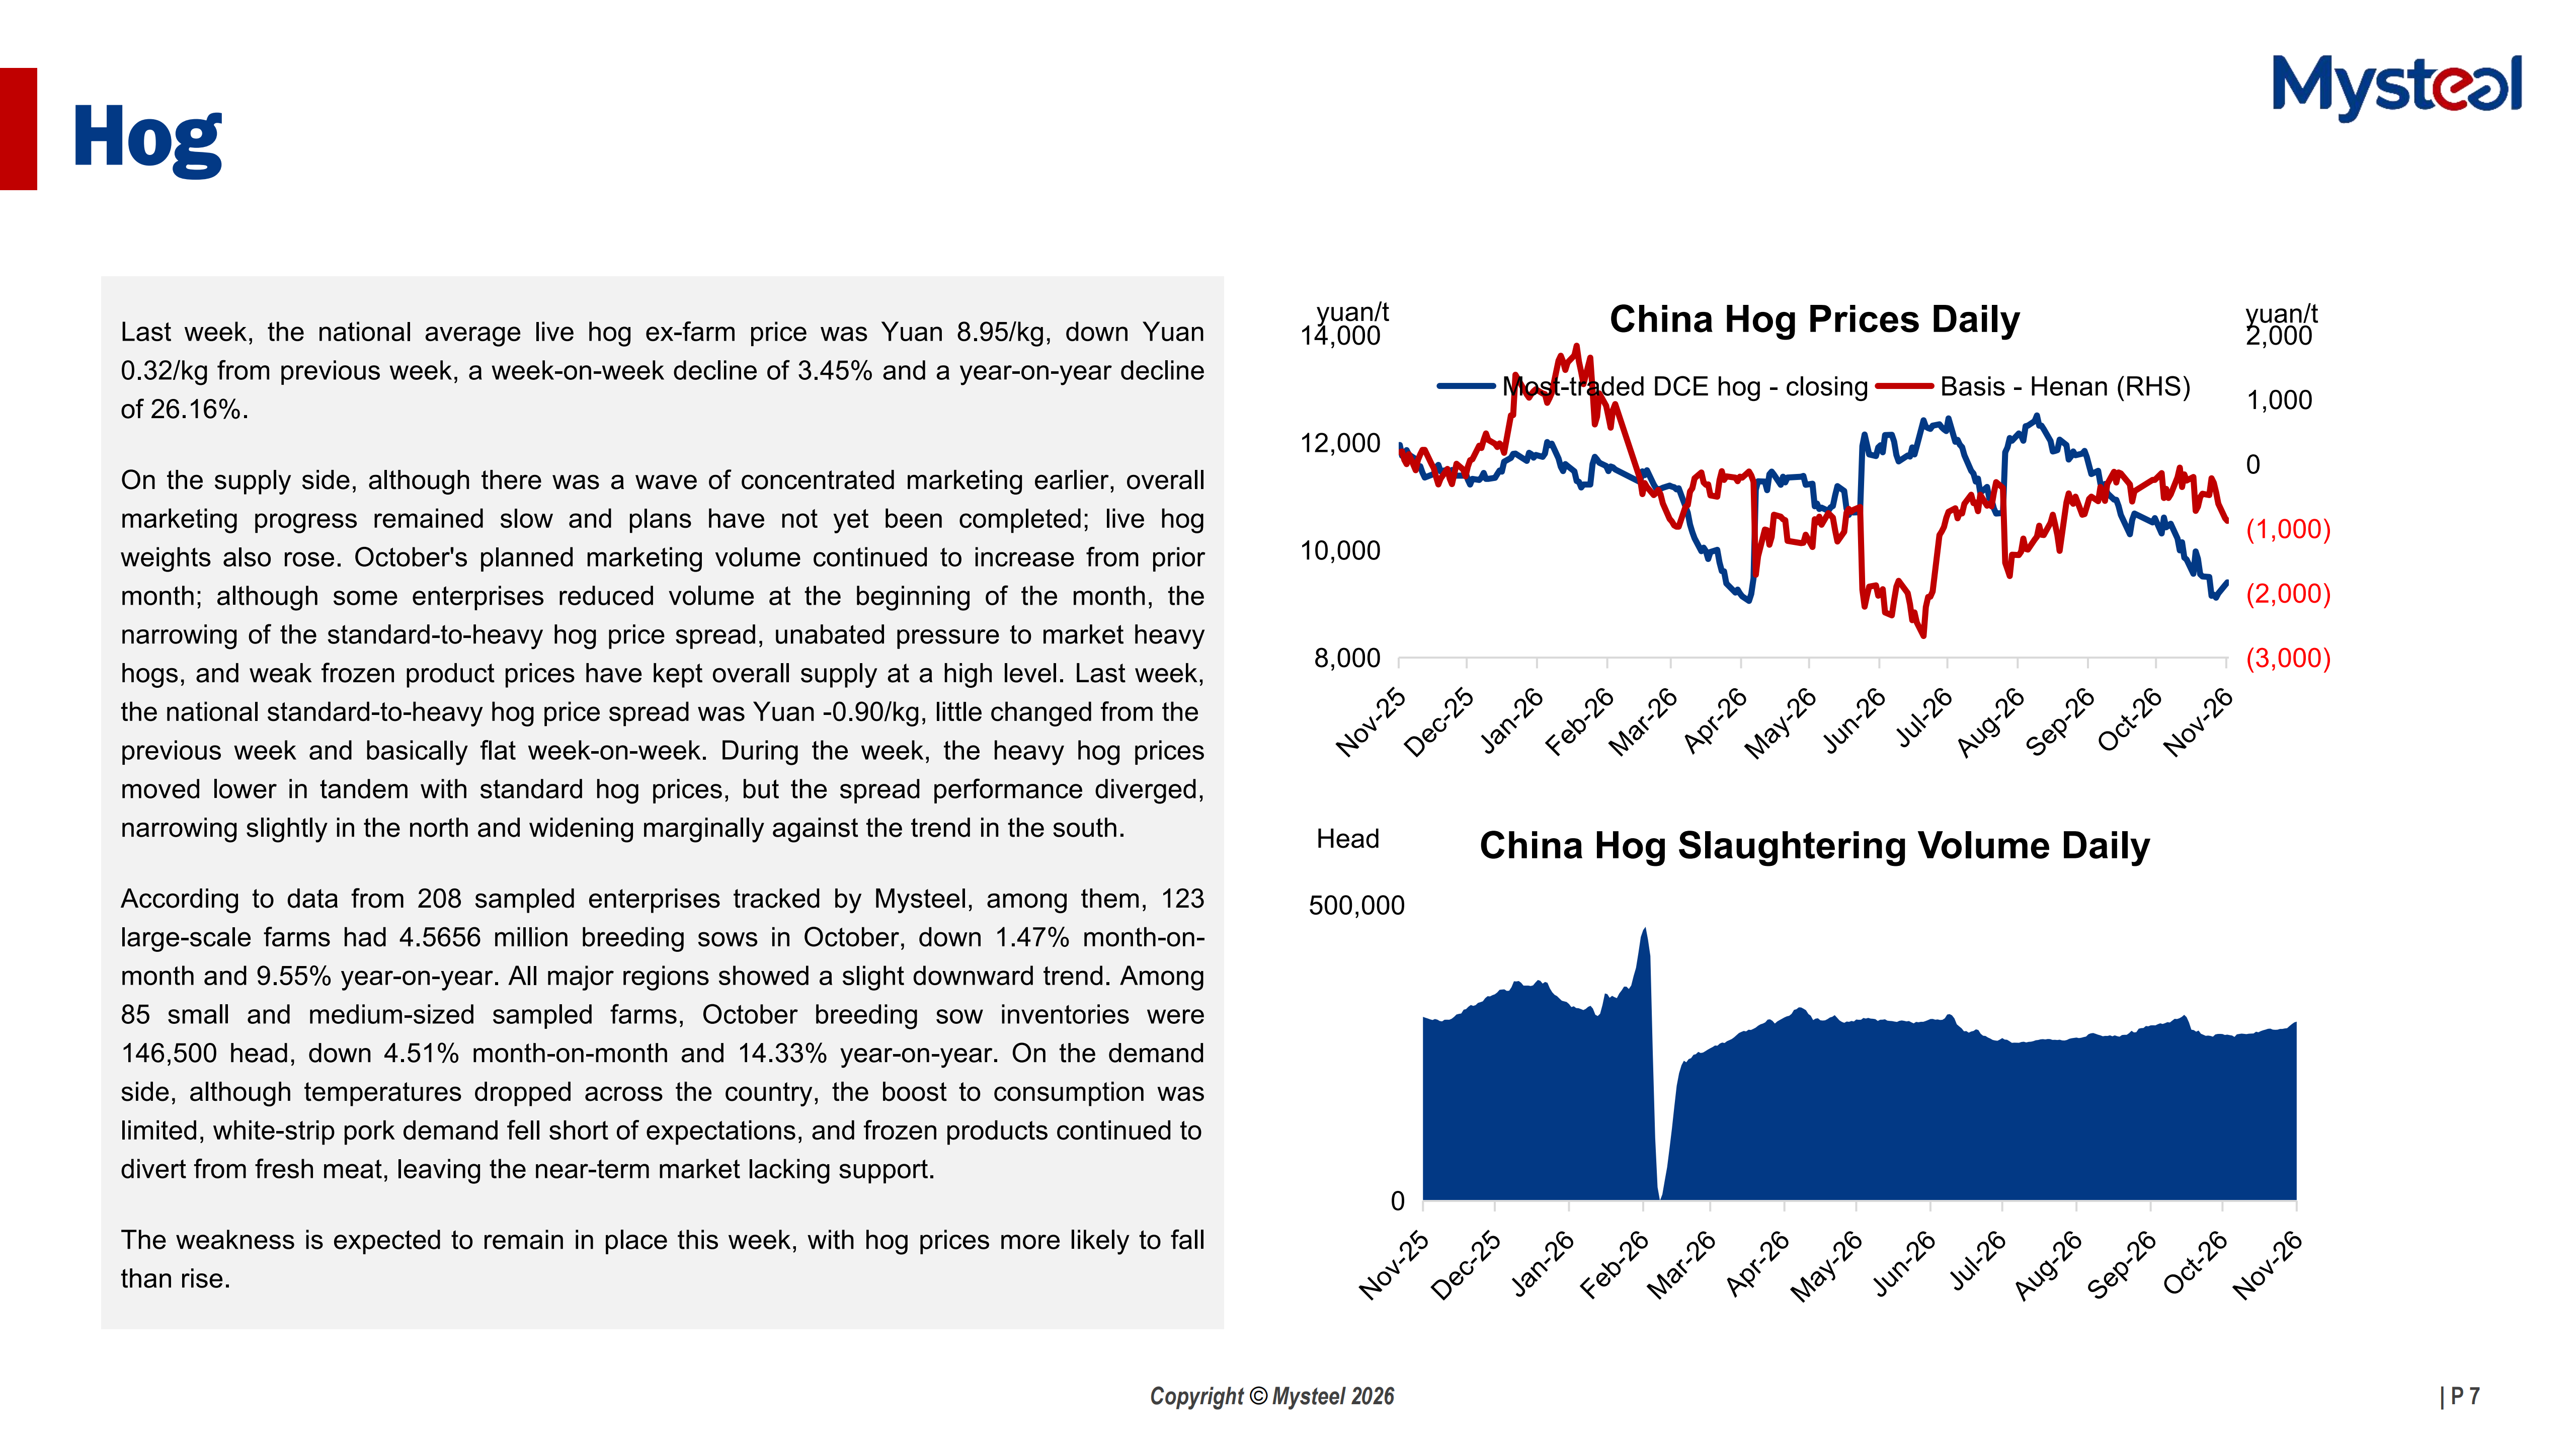
Hog: National average ex-farm hog price fell both week-on-week and year-on-year. Slaughter progress stayed slow, weights rose, and supply remained ample; frozen product prices were soft. Hog prices are expected to stay weak, more likely to fall than rise.
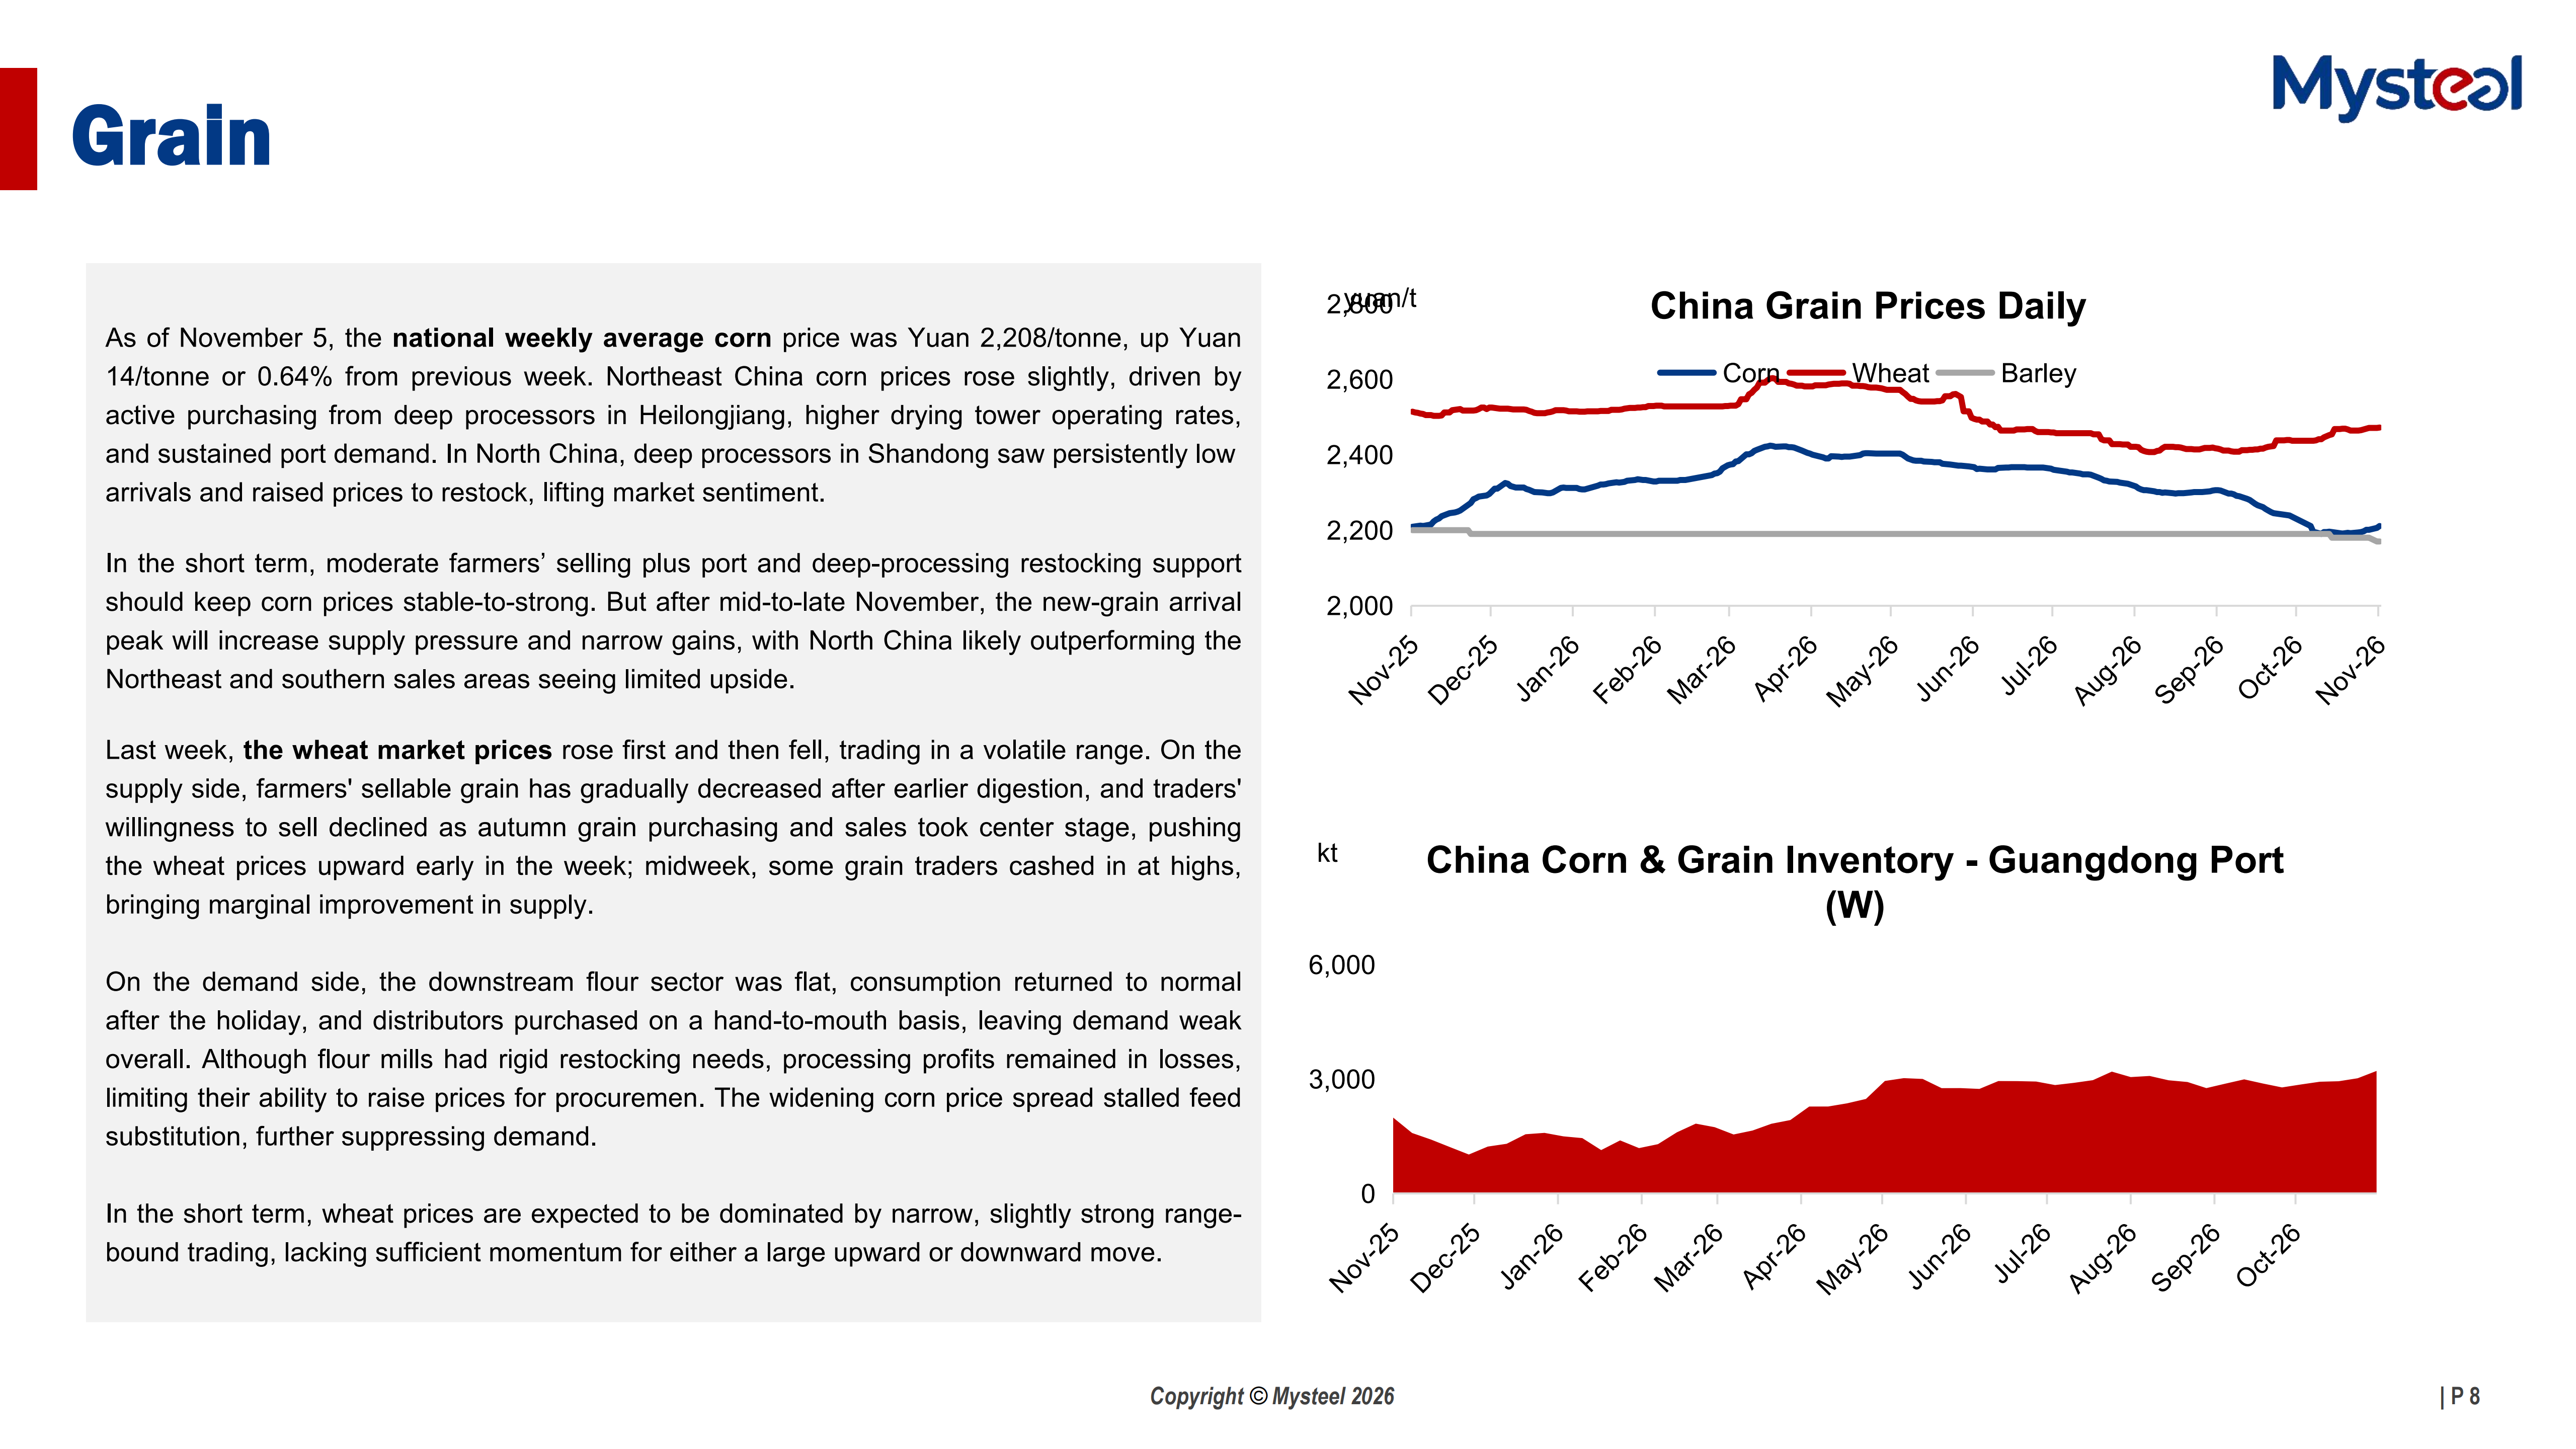
Grain: China's weekly average corn price rose week-on-week. Northeast prices edged up on active g deep-processor buying. Near term corn prices are likely to stay firm. After mid-to-late November, the new-grain peak will cap gains, with North China outperforming the Northeast.
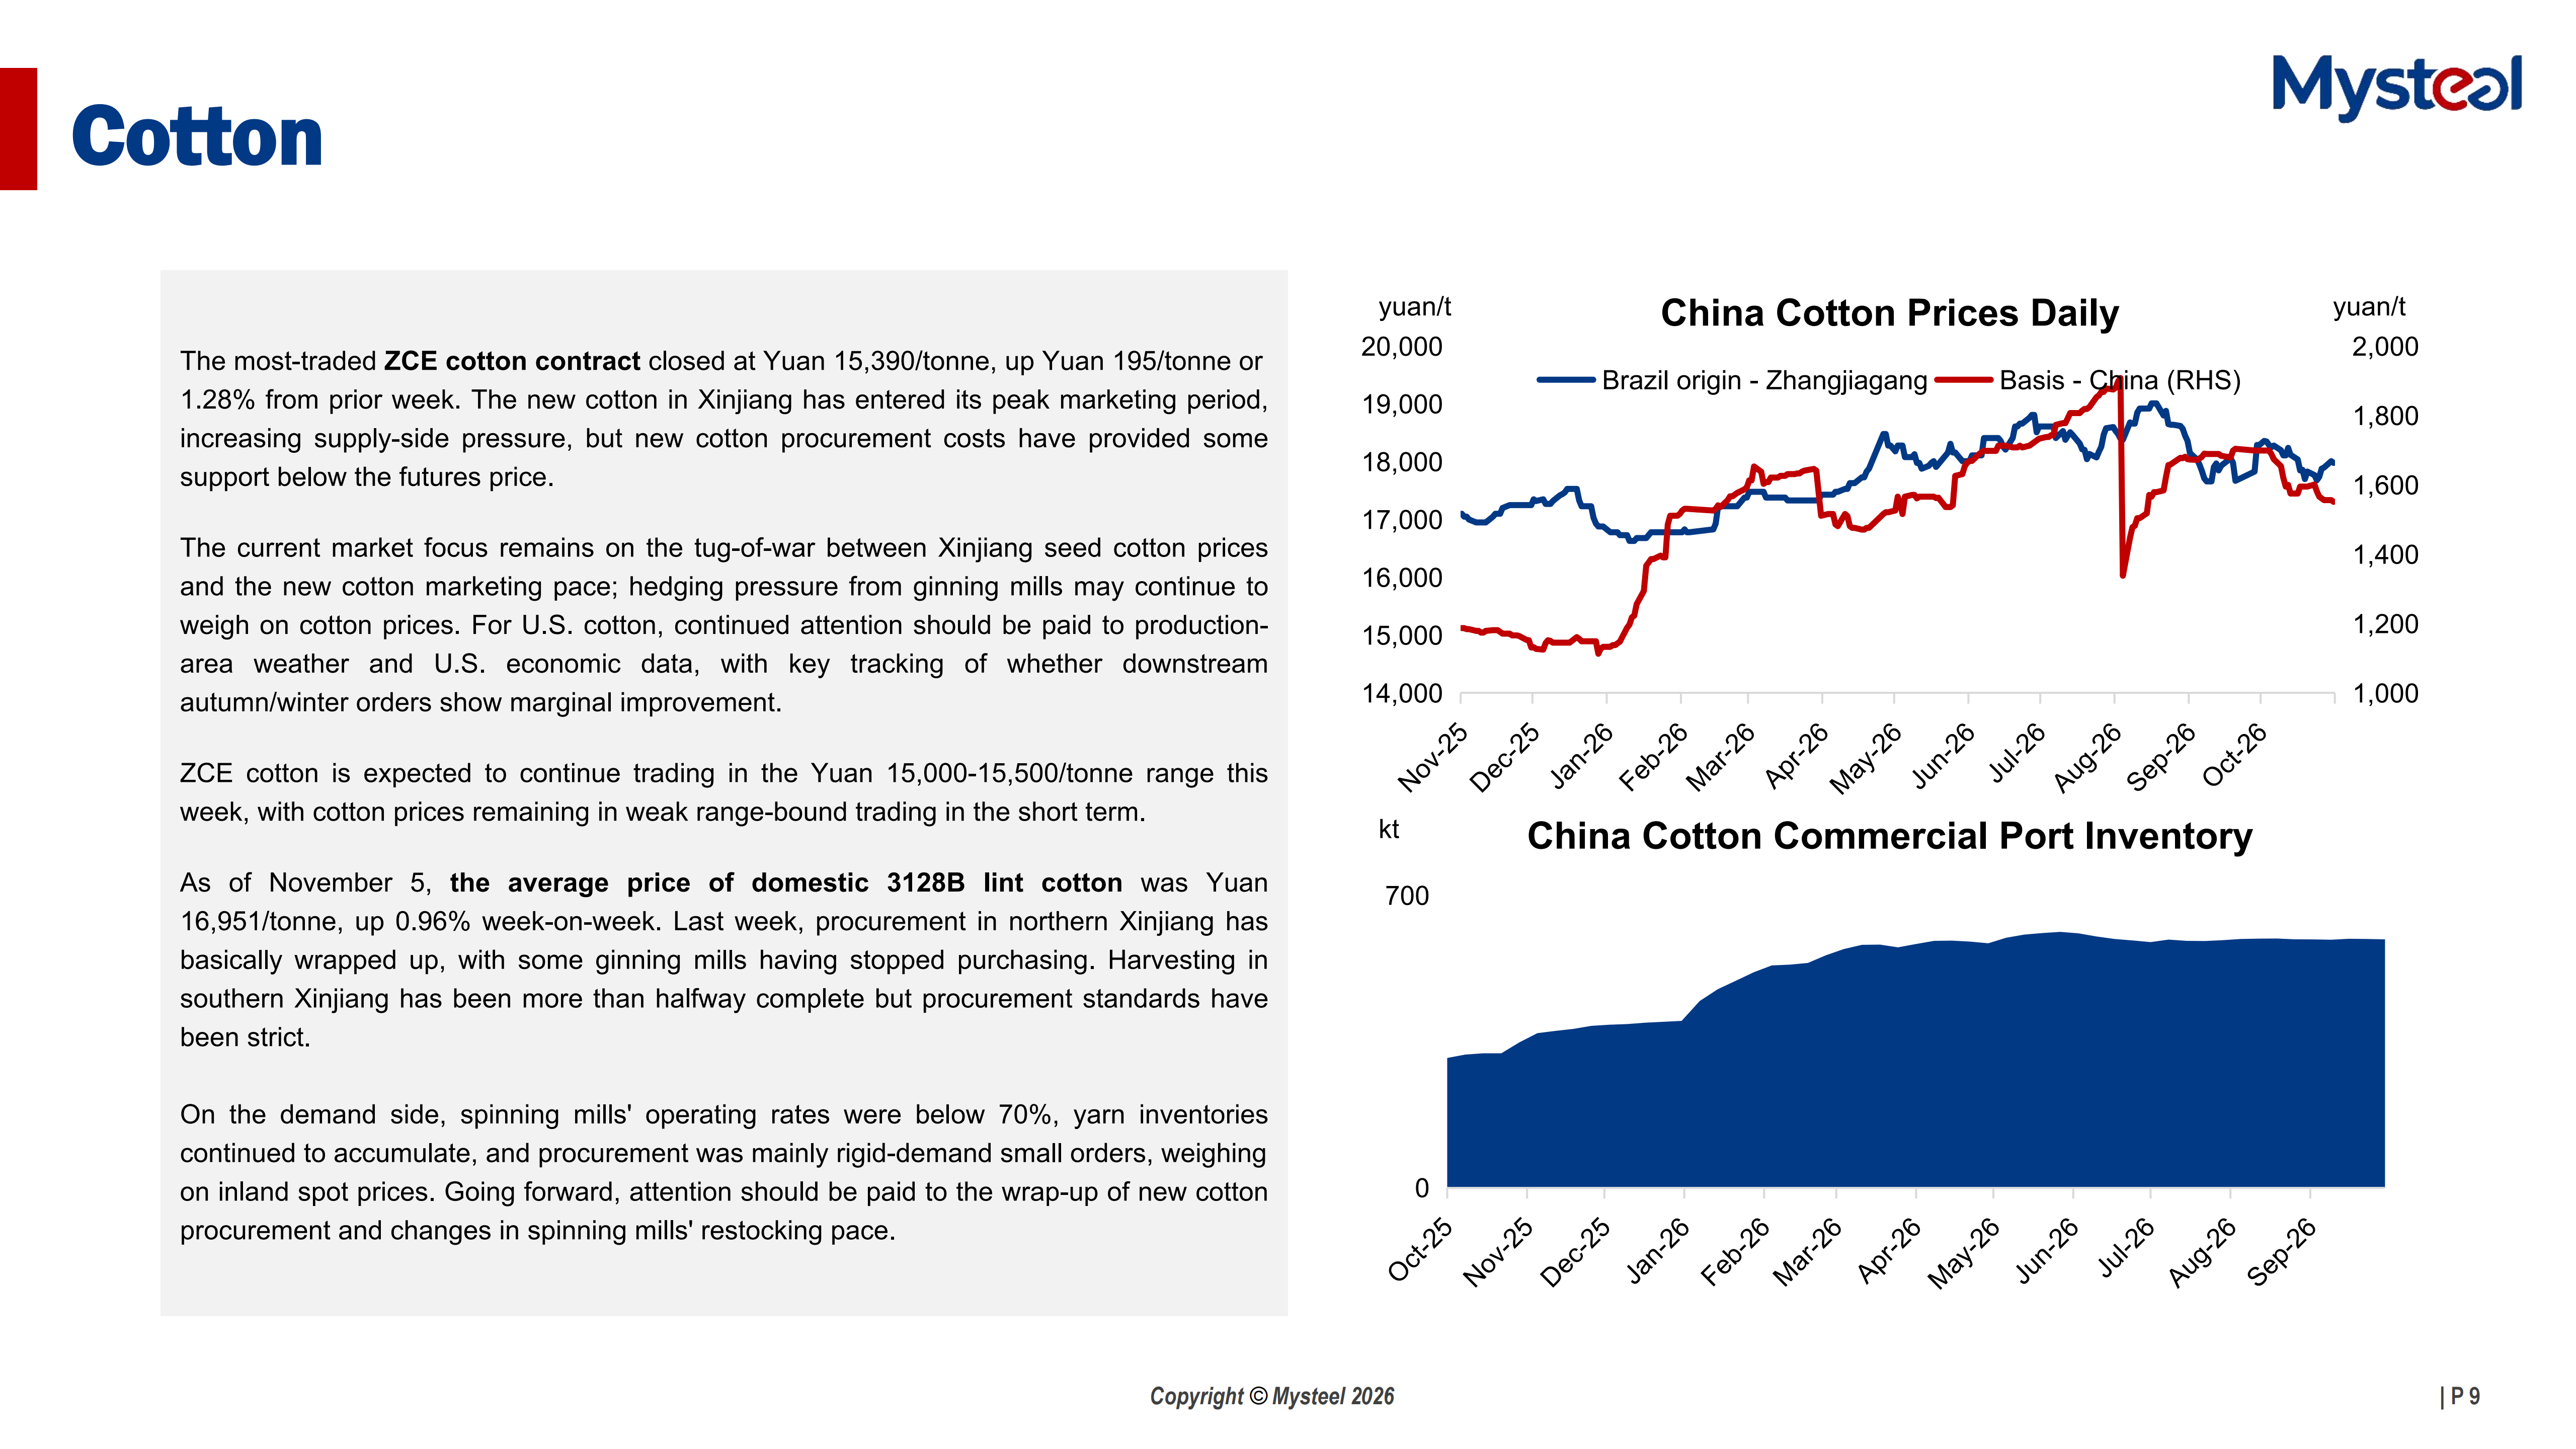
Cotton: ZCE cotton fell week-on-week. The new cotton Xinjiang is at peak marketing season, adding up to the supply pressure, though procurement costs underpin the market. The cotton prices are expected to remain weak and range-bound.