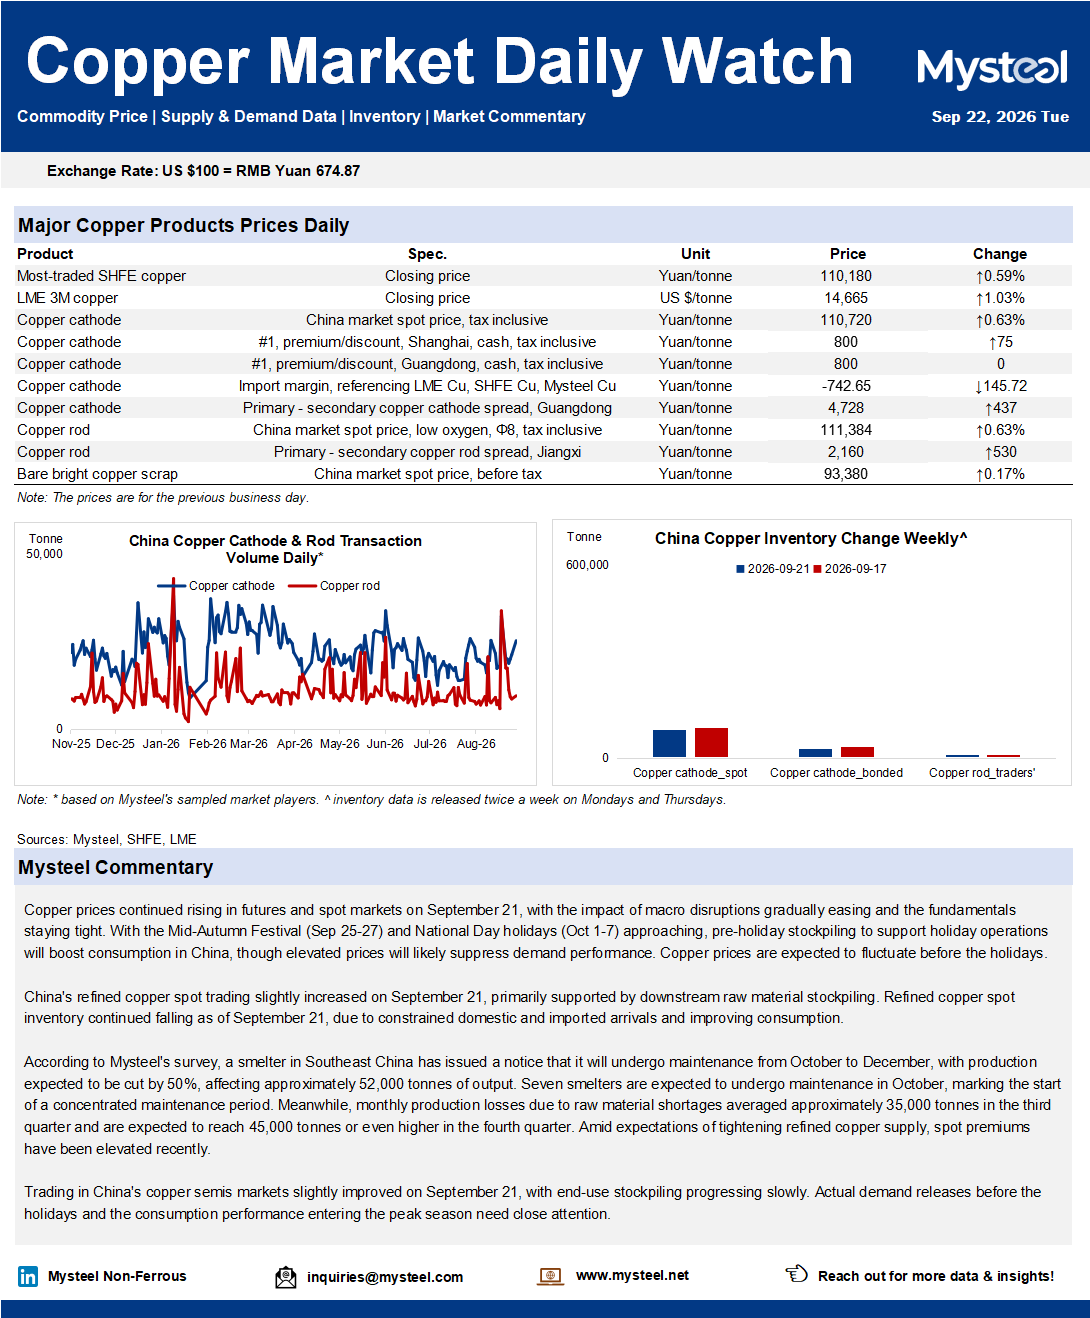
Copper prices continued rising in futures and spot markets on September 21, with the impact of macro disruptions gradually easing and the fundamentals staying tight. With the Mid-Autumn Festival (Sep 25-27) and National Day holidays (Oct 1-7) approaching, pre-holiday stockpiling to support holiday operations will boost copper consumption in China, though elevated prices will likely suppress demand performance. Copper prices are expected to fluctuate before the holidays.
China's refined copper spot trading slightly increased on September 21, primarily supported by downstream raw material stockpiling. Refined copper spot inventory continued falling as of September 21, due to constrained domestic and imported arrivals and improving consumption.
According to Mysteel's survey, a smelter in Southeast China has issued a notice that it will undergo maintenance from October to December, with production expected to be cut by 50%, affecting approximately 52,000 tonnes of output. Seven smelters are expected to undergo maintenance in October, marking the start of a concentrated maintenance period. Meanwhile, monthly production losses due to raw material shortages averaged approximately 35,000 tonnes in the third quarter and are expected to reach 45,000 tonnes or even higher in the fourth quarter. Amid expectations of tightening refined copper supply, spot premiums have been elevated recently.
Trading in China's copper semis markets slightly improved on September 21, with end-use stockpiling progressing slowly. Actual demand releases before the holidays and the consumption performance entering the peak season need close attention.