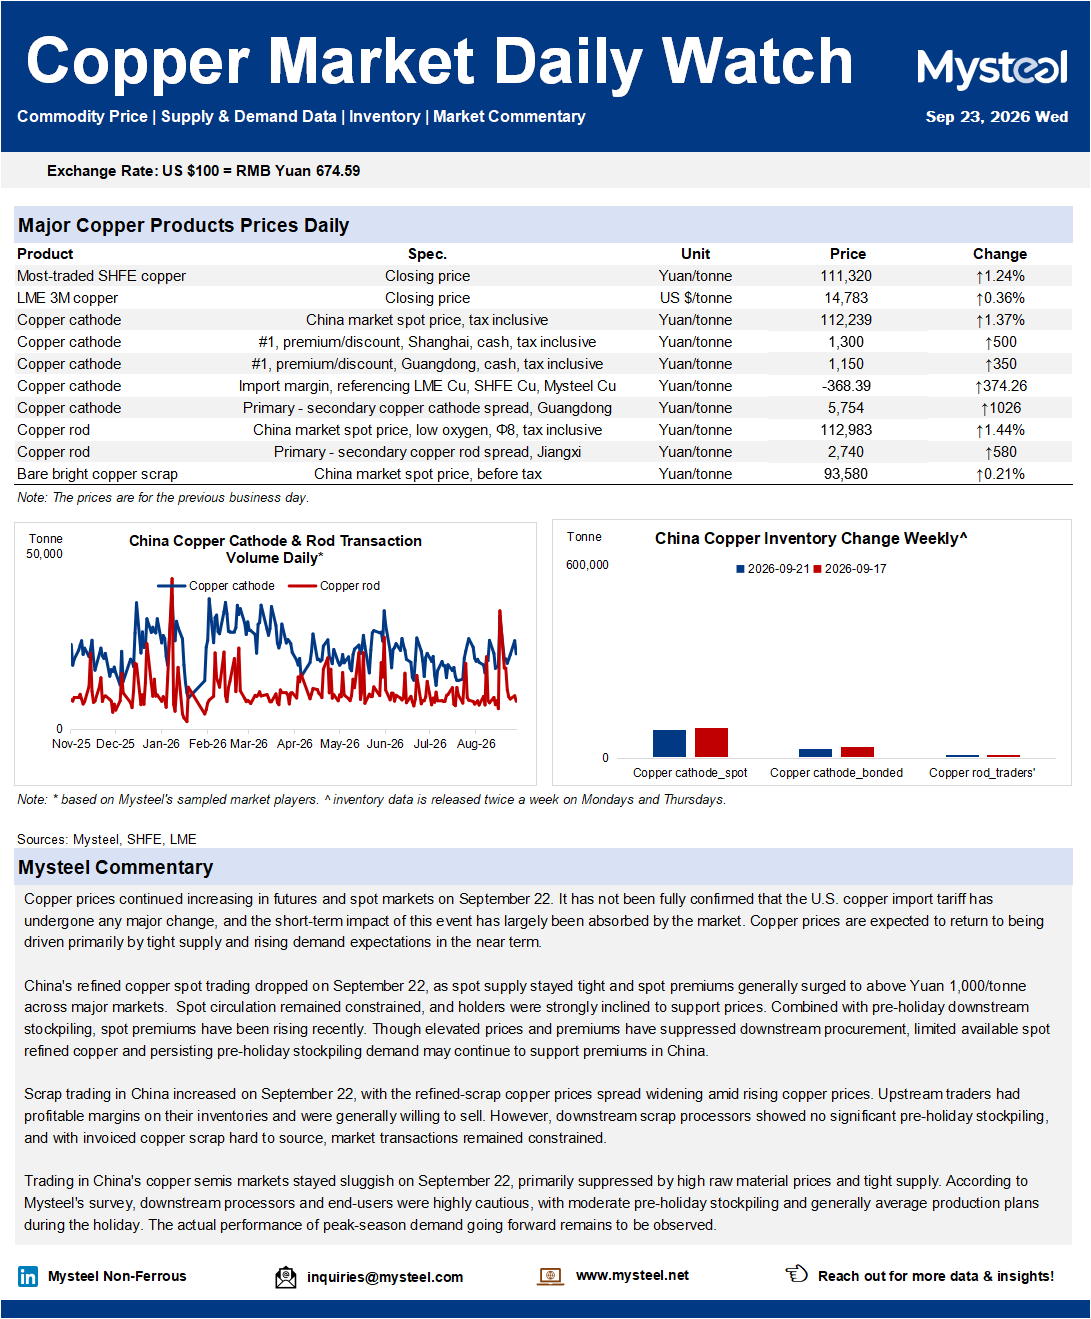
Copper prices continued increasing in futures and spot markets on September 22. It has not been fully confirmed that the U.S. copper import tariff has undergone any major change, and the short-term impact of this event has largely been absorbed by the market. Copper prices are expected to return to being driven primarily by tight supply and rising demand expectations in the near term.
China's refined copper spot trading dropped on September 22, as spot supply stayed tight and spot premiums generally surged to above Yuan 1,000/tonne across major markets. Spot circulation remained constrained, and holders were strongly inclined to support prices. Combined with pre-holiday downstream stockpiling, spot premiums have been rising recently. Though elevated prices and premiums have suppressed downstream procurement, limited available spot refined copper and persisting pre-holiday stockpiling demand may continue to support premiums in China.
Scrap trading in China increased on September 22, with the refined-scrap copper prices spread widening amid rising copper prices. Upstream traders had profitable margins on their inventories and were generally willing to sell. However, downstream scrap processors showed no significant pre-holiday stockpiling, and with invoiced copper scrap hard to source, market transactions remained constrained.
Trading in China's copper semis markets stayed sluggish on September 22, primarily suppressed by high raw material prices and tight supply. According to Mysteel's survey, downstream processors and end-users were highly cautious, with moderate pre-holiday stockpiling and generally average production plans during the holiday. The actual performance of peak-season demand going forward remains to be observed.