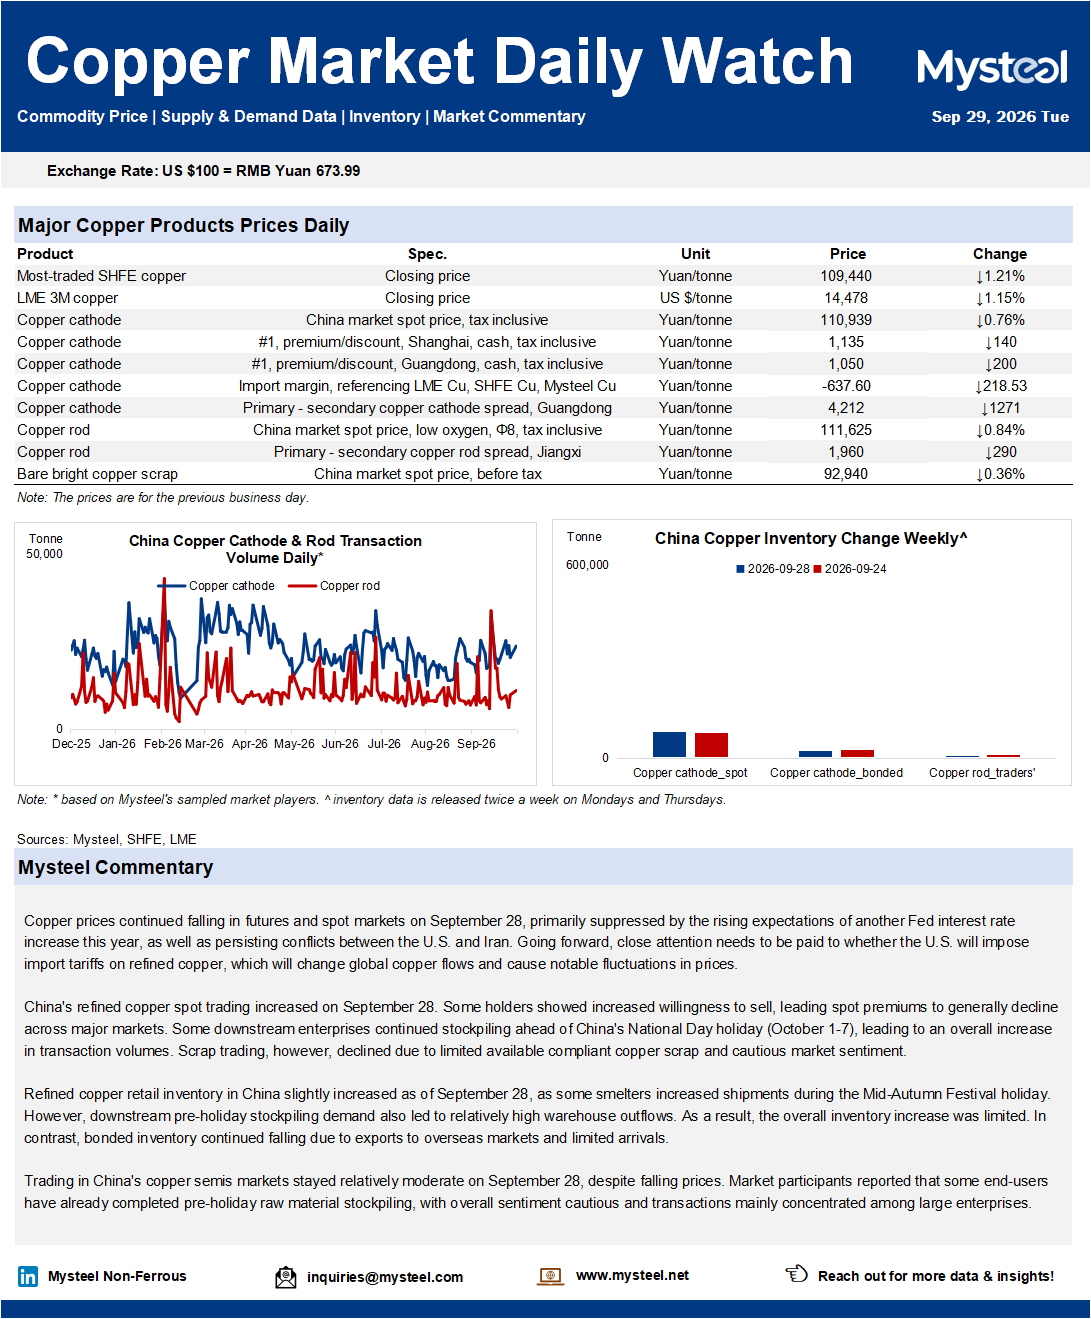
Copper prices continued falling in futures and spot markets on September 28, primarily suppressed by the rising expectations of another Fed interest rate increase this year, as well as persisting conflicts between the U.S. and Iran. Going forward, close attention needs to be paid to whether the U.S. will impose import tariffs on refined copper, which will change global copper flows and cause notable fluctuations in prices.
China's refined copper spot trading increased on September 28. Some holders showed increased willingness to sell, leading spot premiums to generally decline across major markets. Some downstream enterprises continued stockpiling ahead of China's National Day holiday (October 1-7), leading to an overall increase in transaction volumes. Scrap trading, however, declined due to limited available compliant copper scrap and cautious market sentiment.
Refined copper retail inventory in China slightly increased as of September 28, as some smelters increased shipments during the Mid-Autumn Festival holiday. However, downstream pre-holiday stockpiling demand also led to relatively high warehouse outflows. As a result, the overall inventory increase was limited. In contrast, bonded inventory continued falling due to exports to overseas markets and limited arrivals.
Trading in China's copper semis markets stayed relatively moderate on September 28, despite falling prices. Market participants reported that some end-users have already completed pre-holiday raw material stockpiling, with overall sentiment cautious and transactions mainly concentrated among large enterprises.