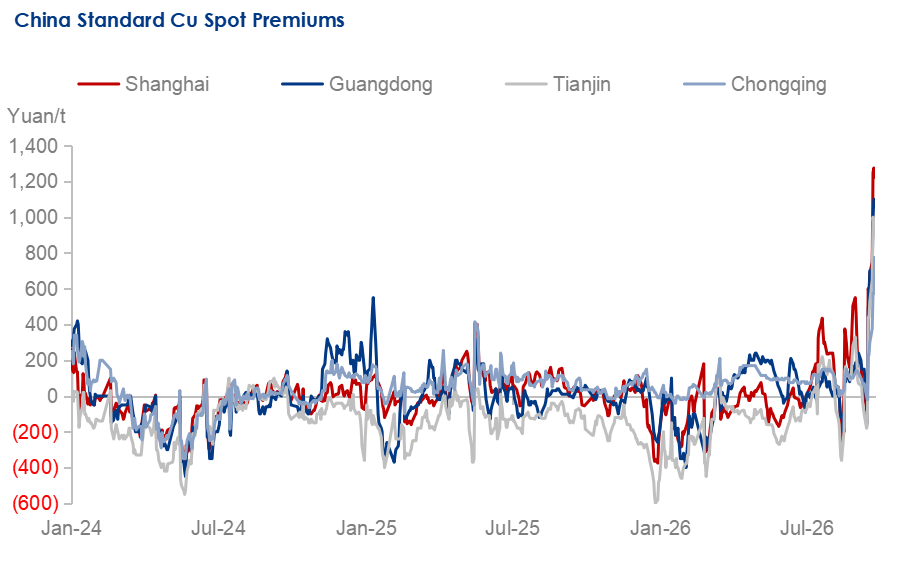
Premium: Tight supply and pre-holiday restocking push spot premiums sharply higher
Before the Mid-Autumn Festival, smelters concentrated on long-term contract shipments, so spot shipments were limited. As a result, fewer domestic cargoes arrived in the spot market, and the increase in imported copper arrivals remained limited. Consequently, tight supply kept spot premiums elevated. Meanwhile, as the holiday approached, downstream stockpiling demand rose and holders held firm on prices, driving China's refined copper spot premiums sharply higher to a new year-to-date high.
Data Source: Mysteel
Looking ahead to this week, with China's National Day holiday approaching, stockpiling demand is expected to continue, and spot tightness is unlikely to ease significantly in the short term. Therefore, China's refined copper spot premium is expected to remain elevated. According to Mysteel, refined copper spot premium ranges are forecast with Guangdong at Yuan 600/tonne to Yuan 1,200/tonne, Tianjin at Yuan 500/tonne to Yuan 1,000/tonne, and Chongqing at Yuan 400/tonne to Yuan 700/tonne this week.
Supply: Imported copper arrivals fail to ease spot tightness
China's refined copper spot supply remained tight last week. By market, in Shanghai, spot circulation was tight. Although some previously delayed imported copper gradually arrived during the week, the increase was limited. Meanwhile, domestic smelters' finished-product inventories were relatively low and long-term contract shipments rose during the week, keeping spot supply limited. In Guangdong, smelters increased direct shipments to end users, further reducing tradable spot resources. Combined with concentrated pre-holiday stockpiling by downstream enterprises, regional spot supply was tight. In Tianjin, maintenance at some major smelters left regional spot supply relatively short. In Chongqing, although smelter shipments increased in the latter half of last week, this did little to ease the tightness. Looking ahead to this week, with the National Day holiday approaching, downstream stockpiling is expected to remain strong, and arrivals of domestic and imported refined copper are unlikely to improve much. China's refined copper supply tightness is therefore expected to persist.
Demand: Downstream pre-holiday raw material restocking demand rises
Although copper prices moved higher last week, China's refined copper spot trading volume rose week on week, supported by pre-holiday restocking demand. By market, in Shanghai, downstream purchasing sentiment was fairly active. Although the sharp rise in spot premiums weighed somewhat on trading volume, overall pre-holiday restocking demand increased. In Guangdong, downstream processors concentrated their pre-holiday restocking, with a stronger willingness to buy on dips. When premiums rose sharply, essential purchasing remained steady. In Tianjin, as the holiday approached, local copper-processing downstream enterprises in North China became noticeably more active in fixing prices on dips and restocking, with essential purchasing activity improving. By contrast, in Chongqing, refined copper spot trading slowed amid high copper prices, sharply higher spot premiums and limited orders. According to Mysteel's survey of 56 Chinese refined copper trading enterprises (including smelters, traders, and downstream processors), the daily average transaction volume between September 21 and September 24 increased by 13.74% or 2,752.5 tonnes compared with the previous week, reaching 22,793 tonnes. Looking ahead to this week, with the National Day holiday approaching, downstream restocking demand is expected to continue, but the dampening effect of high copper prices and high premiums on spot trading needs close attention.
Import: Widening import losses dampen foreign trade market activity
As the LME copper backwardation widened, China's refined copper import arbitrage ratio fell last week, leaving import trade broadly loss-making. Combined with relatively limited supply, foreign trade market trading was quiet. Regarding prices, although arriving cargoes increased, they mostly flowed into the domestic market. Limited supply thus supported Yangshan refined copper warrant and B/L premiums, but slower foreign trade trading still dragged the overall weekly average premium down week on week. Looking ahead, with the import arbitrage ratio expected to stay weak in the short term, trading volume in China's refined copper foreign trade market is unlikely to improve significantly.
Inventory: China's refined copper retail and bonded inventory both decline further
China's refined copper retail inventory fell further last week. As the holiday approached, downstream restocking sentiment emerged and purchasing volume rose during the week, increasing spot warehouse outbound volumes. Meanwhile, smelters' finished-product inventories were limited, so available shipments were low, capping inbound volumes at spot warehouses. Therefore, refined copper retail inventory fell week on week. Looking ahead to this week, domestic cargo arrivals are expected to remain relatively low. Although some imported copper is expected to arrive, overall replenishment will be limited. With some downstream enterprises still expected to restock during the week, China's refined copper retail inventory is likely to decline further.
China's refined copper bonded inventory also fell last week. Some bonded zone warehouses exported goods overseas during the week, and as the import arbitrage window had opened earlier, some bonded zone cargoes were cleared into the domestic market, reducing bonded zone inventories. Looking ahead to this week, bonded zone cargoes that are expected to be exported overseas or enter the domestic market remain, while export cargoes from domestic smelters arriving at bonded zones are expected to be limited in the short term. Therefore, bonded inventory is expected to edge down further.
The weekly average spread between the main COMEX and LME copper contracts was up by $100.93/tonne week on week to $263.85/tonne last week. The average LME cash-3M copper contract settlement spread was $78/tonne last week, up by $88.6/tonne week on week. As the COMEX-LME refined copper price spread stayed relatively low, COMEX refined copper inventory growth slowed, while LME refined copper inventory increased. Looking ahead, as expectations of additional U.S. tariffs on refined copper ease, the COMEX copper premium may narrow, so the flow of cargoes into North America is expected to slow and may even reverse, with copper likely starting flowing back from North America to other markets.
More regular analysis and comprehensive data on China's copper industry are available in Mysteel Copper Weekly, Mysteel Copper Monthly, and Mysteel Copper Database. Reach out to us via Mysteel's official website: Latest & Reliable Copper Market Price in China | Mysteel, and follow Mysteel Non-Ferrous for more insights!
Written by Zhaorui Cui, cuizhaorui@mysteel.com
Edited by Mingyuan Wang, wangmingyuan@mysteel.com