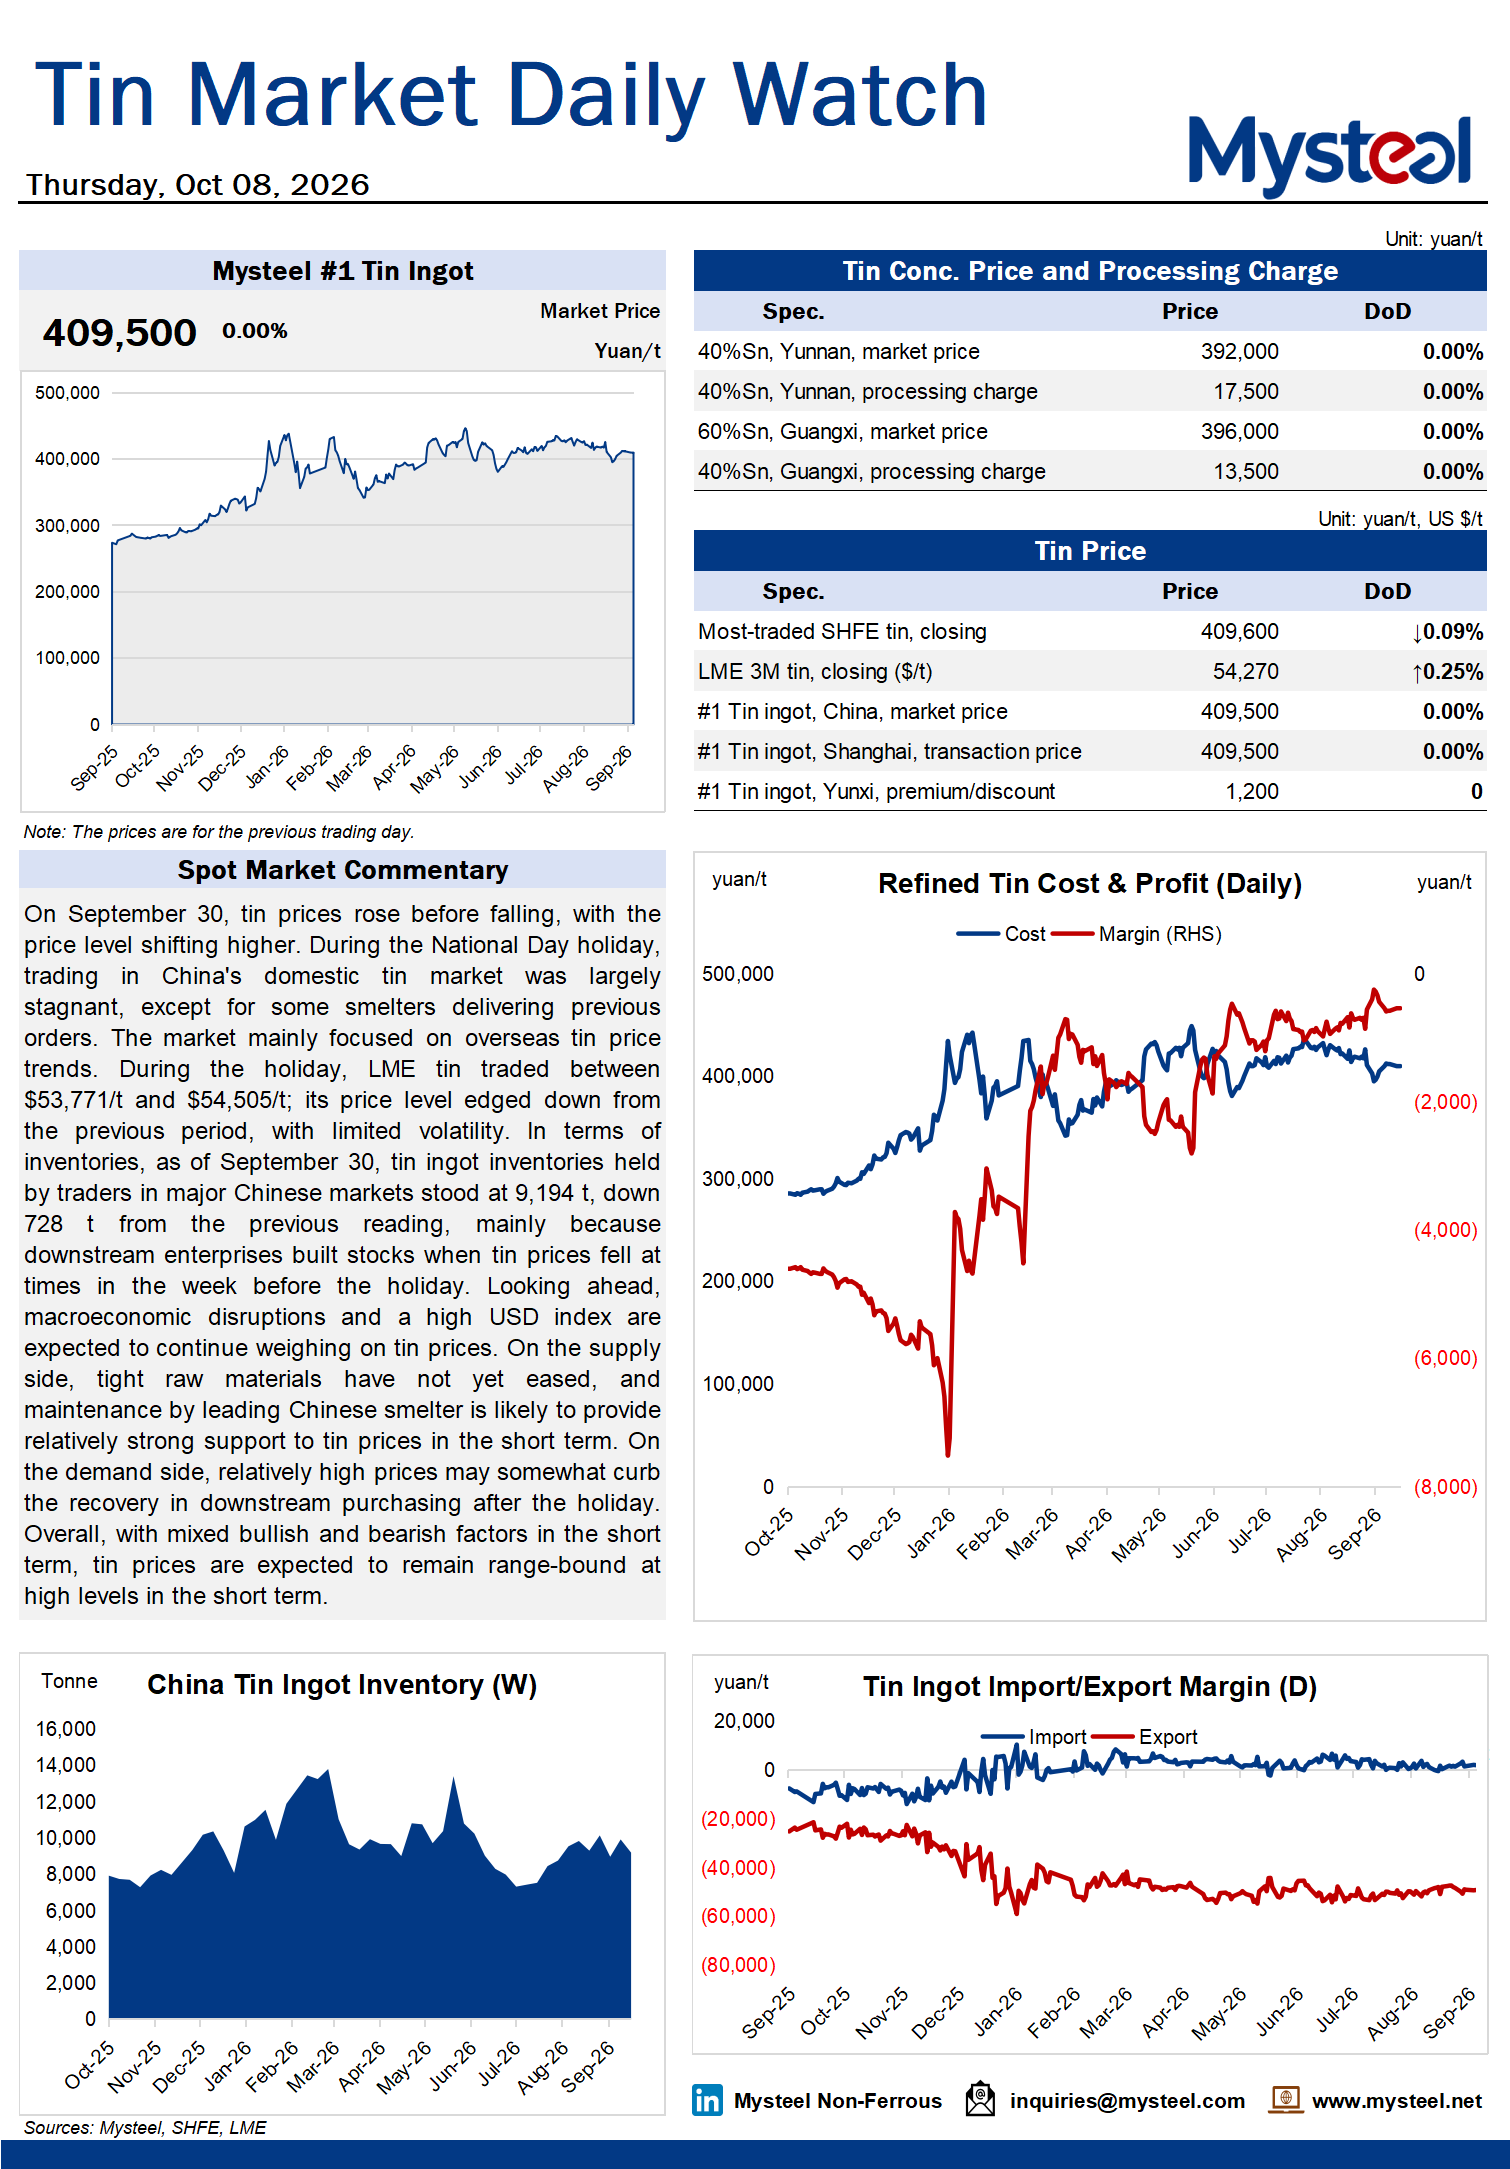
On September 30, tin prices rose before falling, with the price level shifting higher. During the National Day holiday, trading in China's domestic tin market was largely stagnant, except for some smelters delivering previous orders. The market mainly focused on overseas tin price trends. During the holiday, LME tin traded between $53,771/t and $54,505/t; its price level edged down from the previous period, with limited volatility. In terms of inventories, as of September 30, tin ingot inventories held by traders in major Chinese markets stood at 9,194 t, down 728 t from the previous reading, mainly because downstream enterprises built stocks when tin prices fell at times in the week before the holiday. Looking ahead, macroeconomic disruptions and a high USD index are expected to continue weighing on tin prices. On the supply side, tight raw materials have not yet eased, and maintenance by leading Chinese smelter is likely to provide relatively strong support to tin prices in the short term. On the demand side, relatively high prices may somewhat curb the recovery in downstream purchasing after the holiday. Overall, with mixed bullish and bearish factors in the short term, tin prices are expected to remain range-bound at high levels in the short term.