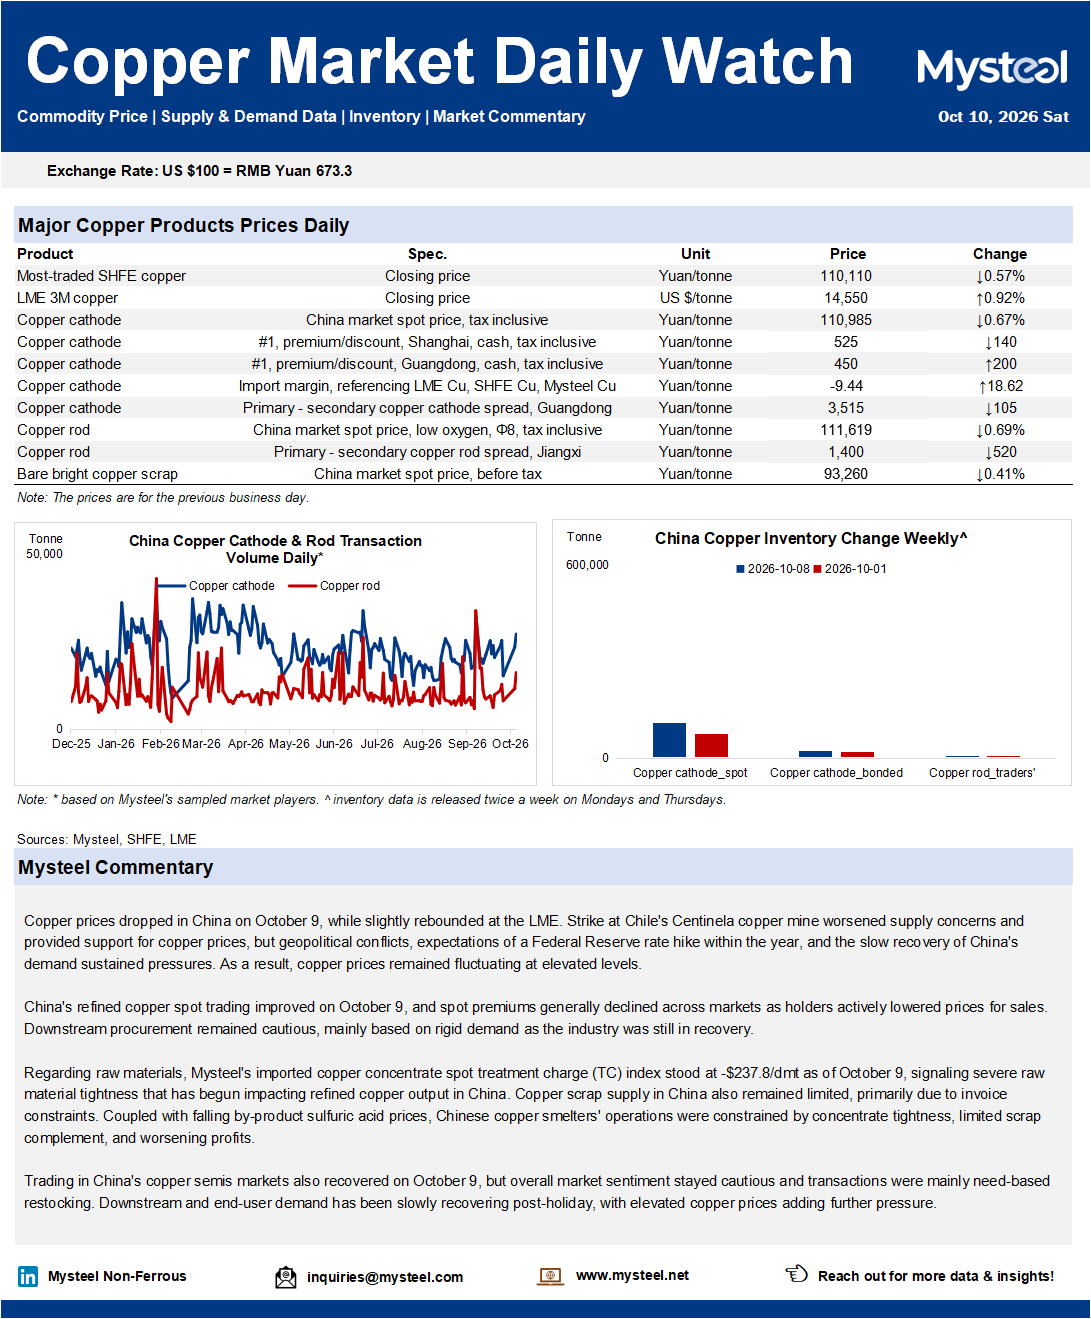
Copper prices dropped in China on October 9, while slightly rebounded at the LME. Strike at Chile's Centinela copper mine worsened supply concerns and provided support for copper prices, but geopolitical conflicts, expectations of a Federal Reserve rate hike within the year, and the slow recovery of China's demand sustained pressures. As a result, copper prices remained fluctuating at elevated levels.
China's refined copper spot trading improved on October 9, and spot premiums generally declined across markets as holders actively lowered prices for sales. Downstream procurement remained cautious, mainly based on rigid demand as the industry was still in recovery.
Regarding raw materials, Mysteel's imported copper concentrate spot treatment charge (TC) index stood at -$237.8/dmt as of October 9, signaling severe raw material tightness that has begun impacting refined copper output in China. Copper scrap supply in China also remained limited, primarily due to invoice constraints. Coupled with falling by-product sulfuric acid prices, Chinese copper smelters' operations were constrained by concentrate tightness, limited scrap complement, and worsening profits.
Trading in China's copper semis markets also recovered on October 9, but overall market sentiment stayed cautious and transactions were mainly need-based restocking. Downstream and end-user demand has been slowly recovering post-holiday, with elevated copper prices adding further pressure.