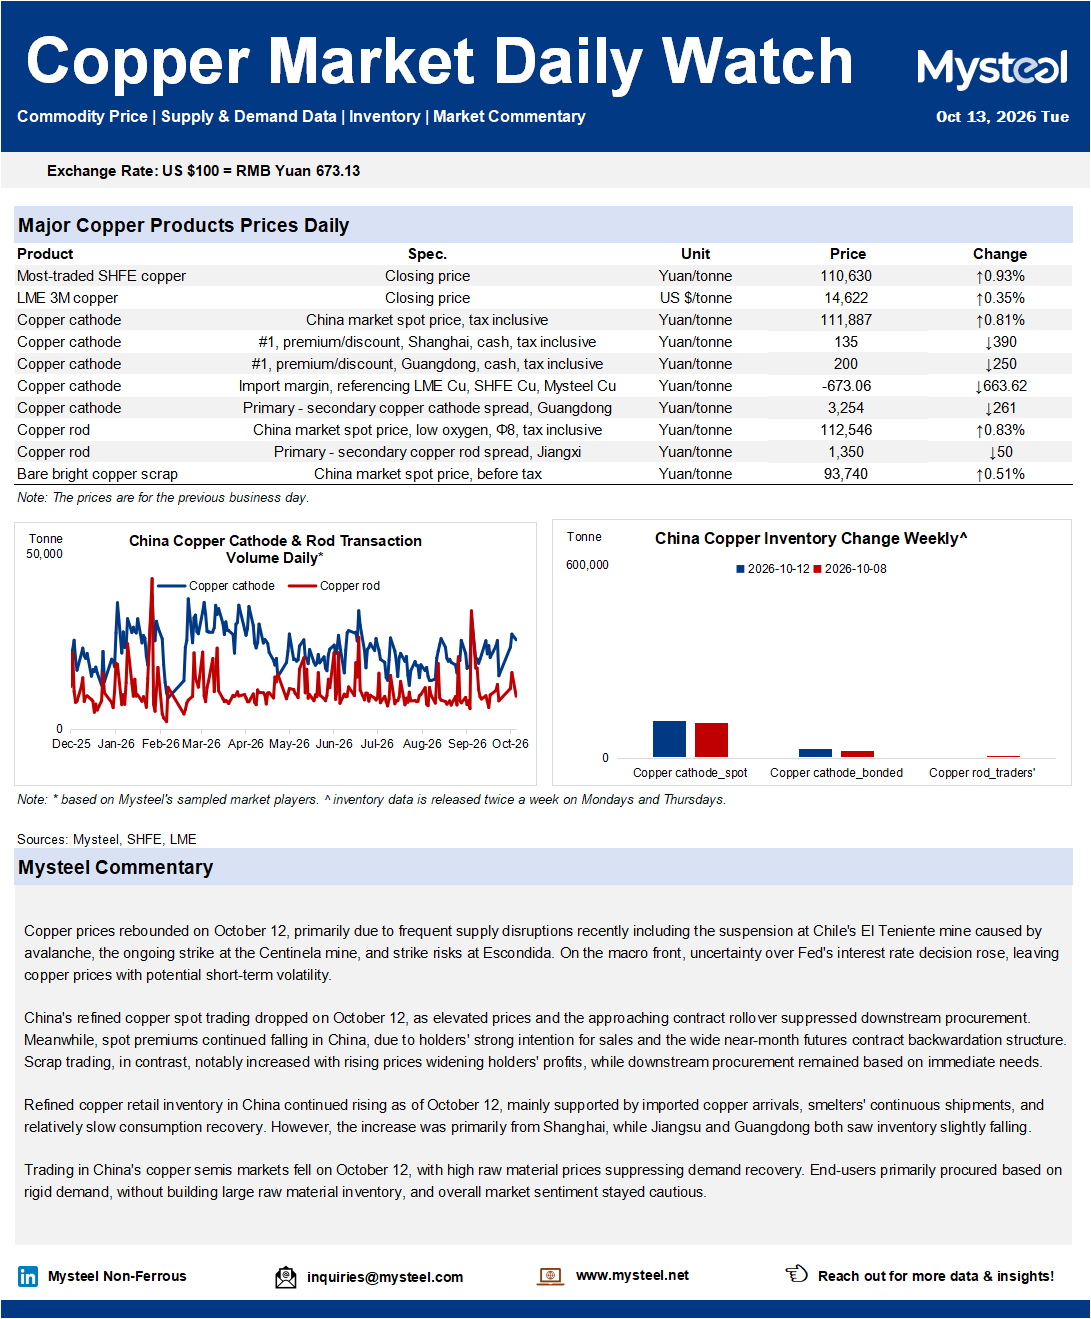
Copper prices rebounded on October 12, primarily due to frequent supply disruptions recently including the suspension at Chile's El Teniente mine caused by avalanche, the ongoing strike at the Centinela mine, and strike risks at Escondida. On the macro front, uncertainty over Fed's interest rate decision rose, leaving copper prices with potential short-term volatility.
China's refined copper spot trading dropped on October 12, as elevated prices and the approaching contract rollover suppressed downstream procurement. Meanwhile, spot premiums continued falling in China, due to holders' strong intention for sales and the wide near-month futures contract backwardation structure. Scrap trading, in contrast, notably increased with rising prices widening holders' profits, while downstream procurement remained based on immediate needs.
Refined copper retail inventory in China continued rising as of October 12, mainly supported by imported copper arrivals, smelters' continuous shipments, and relatively slow consumption recovery. However, the increase was primarily from Shanghai, while Jiangsu and Guangdong both saw inventory slightly falling.
Trading in China's copper semis markets fell on October 12, with high raw material prices suppressing demand recovery. End-users primarily procured based on rigid demand, without building large raw material inventory, and overall market sentiment stayed cautious.