Premium: Spot premium retreats from highs on holidays and approaching futures delivery
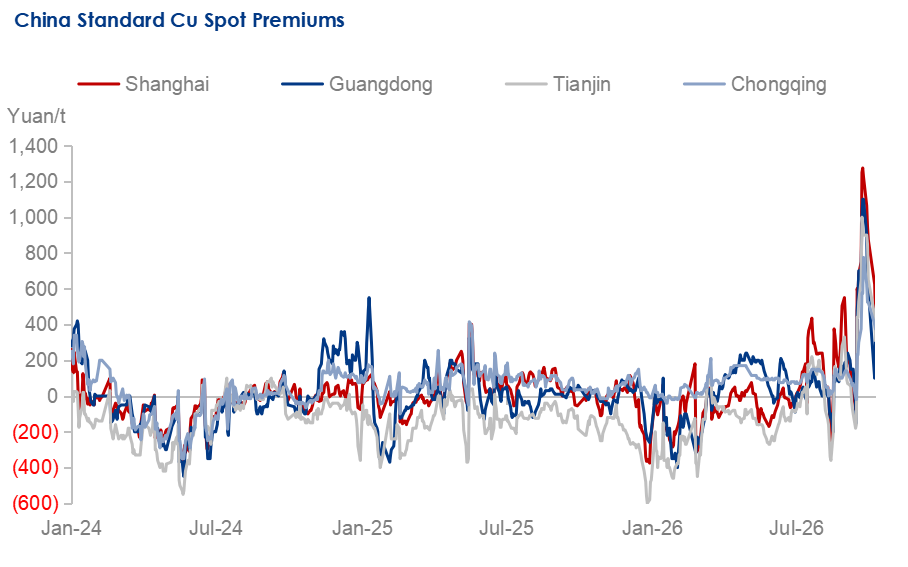
Before China's National Day holiday, although downstream raw material procurement demand still supported the spot premium, traders stepped up pre-holiday selling to avoid the risk of holding inventory over the holiday. Consequently, China's refined copper spot premium had already begun to decline gradually before the holiday. During the holiday, domestic smelters maintained output and shipments, but spot market trading stalled, and some imported copper also flowed into the domestic market, leaving spot supply relatively ample and pressuring the refined copper spot premium further. After the holiday, with futures delivery approaching and the SHFE near-month backwardation widening, holders actively cut prices to sell, while downstream companies remained cautious in procurement. Therefore, China's refined copper spot premium continued to decline.
Data Source: Mysteel
Looking ahead, spot supply in the refined copper market is still expected to increase this week, and with SHFE refined copper contract delivery coinciding, China's refined copper spot premium is expected to decline in the short term. According to Mysteel, refined copper spot premium ranges are forecast with Guangdong at Yuan 200/tonne to Yuan 1,000/tonne, Tianjin at Yuan 200/tonne to Yuan 600/tonne, and Chongqing at Yuan 0/tonne to Yuan 400/tonne this week.
Supply: Spot supply ample on increased smelter shipments
China's refined copper spot supply diverged across markets but improved overall from earlier levels. By market, Shanghai and Guangdong saw normal smelter production and shipments during the holiday, and imported copper arrivals also increased, improving spot availability. In Tianjin, maintenance at major regional smelters continued, so supply improvement was less evident and regional refined copper spot availability remained relatively tight. In Chongqing, refined copper arrivals during the holiday were low, and increased long-term contract deliveries further reduced spot availability. Looking ahead, some in-transit cargoes will gradually arrive in certain markets in the short term, so China's refined copper spot supply is still expected to improve versus pre-holiday levels. However, as holiday cargoes are gradually consumed and post-holiday downstream consumption is expected to show some resilience, supply is likely to gradually return to a relatively tight state.
Demand: Post-holiday restocking by downstream lifts spot market trading volume
According to Mysteel's survey of 56 Chinese refined copper trading enterprises (including smelters, traders, and downstream processors), China's refined copper spot average daily trading volume was 22,990 tonne over September 28 to October 9, up by 197.5 tonne, or 0.87%, from the daily average for September 21-24. Although downstream stockpiling demand slowed on September 30 ahead of the holiday, leaving that day's volume at only 15,255 tonne, pre-holiday restocking sentiment on September 28 and September 29 was fair, with daily volumes both above 23,000 tonne. After the holiday (October 8-9), downstream essential demand for refined copper recovered quickly, with trading volumes of 23,440 tonne and 27,170 tonne, respectively. Looking ahead, although short-term spot availability is expected to improve and may weigh on the spot premium, copper's absolute price remains high, which is expected to restrain the recovery in downstream consumption to some extent. Therefore, China's refined copper spot trading volume is unlikely to rise further significantly in the short term.
Import: Widening import losses dampen foreign trade market activity
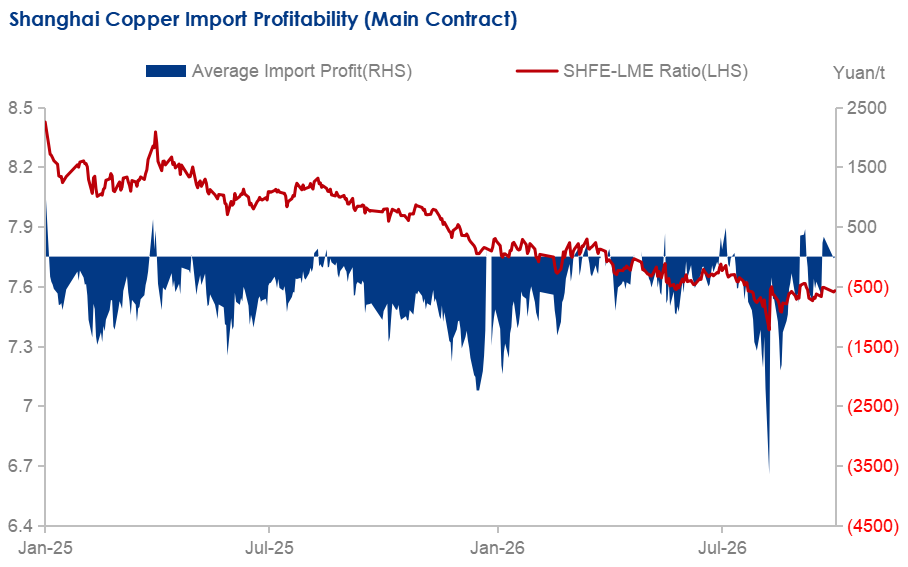
During September 28 - October 9, as copper prices fluctuated at home and abroad, China's refined copper import ratio improved, and traders' import losses narrowed. On September 29, September 30, and October 8, import trade even turned from loss to profit. However, imported copper supply and quotes in the foreign trade market were scarce, so the improvement in trading activity was limited. With imported supply tight and the import ratio improving, holders continued to raise quotes, driving a notable increase in refined copper warrant and bill of lading premiums at Shanghai Yangshan Port. Looking ahead, as China's refined copper import ratio improves, trading activity in the foreign trade market is expected to rise, and refined copper imports are likely to improve.
Data Source: Mysteel
Inventory: China's refined copper retail inventory surges post-holiday on smelter shipments during holiday
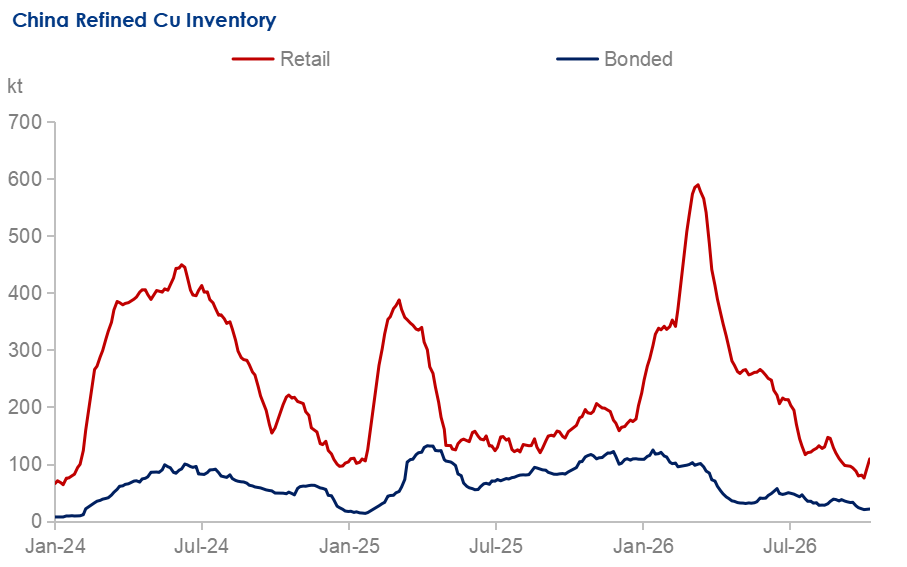
China's refined copper retail inventory rose after the National Day holiday. During the holiday, smelters maintained normal production while spot market trading stalled. With supply strong and demand weak, warehouse inventory accumulated. In addition, imported copper inflows into China's domestic market also increased. Overall, refined copper retail inventory showed a post-holiday buildup trend. Looking ahead to this week, some in-transit cargoes will continue to arrive at warehouses, while spot consumption is expected to see limited growth given high copper prices and futures delivery. Therefore, China's refined copper retail inventory is expected to keep rising slightly.
China's refined copper bonded inventory also edged up from pre-holiday levels, mainly because smelters' planned export cargoes gradually arrived in bonded zones during the holiday. Looking ahead, some warehouses report that refined copper planned for export by smelters is still expected to gradually enter bonded zones. Therefore, China's refined copper bonded inventory is also expected to build up in the short term.
Data Source: Mysteel
In October, the COMEX-LME refined copper price spread stayed low, averaging $175.34/tonne over October 1-9, though it still exceeded $200/tonne on October 5, 6, and 7. On inventories, LME inventories gradually declined entering October, with larger drawdowns when the COMEX-LME refined copper price spread rose, while COMEX inventories increased over the same period. Looking ahead, the U.S. refined copper tariff ruling is a key factor shaping global refined copper inventory trends from Q4 2026 to H1 2027. If implemented as scheduled, COMEX inventories will remain high, while LME inventories are expected to stay in a tight balance due to tight non-U.S. spot supply; if the ruling is further delayed or weakened, COMEX inventory backflow and an LME inventory rebound may occur simultaneously.
More regular analysis and comprehensive data on China's copper industry are available in Mysteel Copper Weekly, Mysteel Copper Monthly, and Mysteel Copper Database. Reach out to us via Mysteel's official website: Latest & Reliable Copper Market Price in China | Mysteel, and follow Mysteel Non-Ferrous for more insights!
Don't miss Mysteel's Q3 2026 Copper Market FREE Webinar! Check the link below to learn more, and register to secure your spots:
https://zoom.us/webinar/register/5417916229515/WN_RWKsQmKPQgeI0fTfEodcMQ
Written by Zhaorui Cui, cuizhaorui@mysteel.com
Edited by Mingyuan Wang, wangmingyuan@mysteel.com
