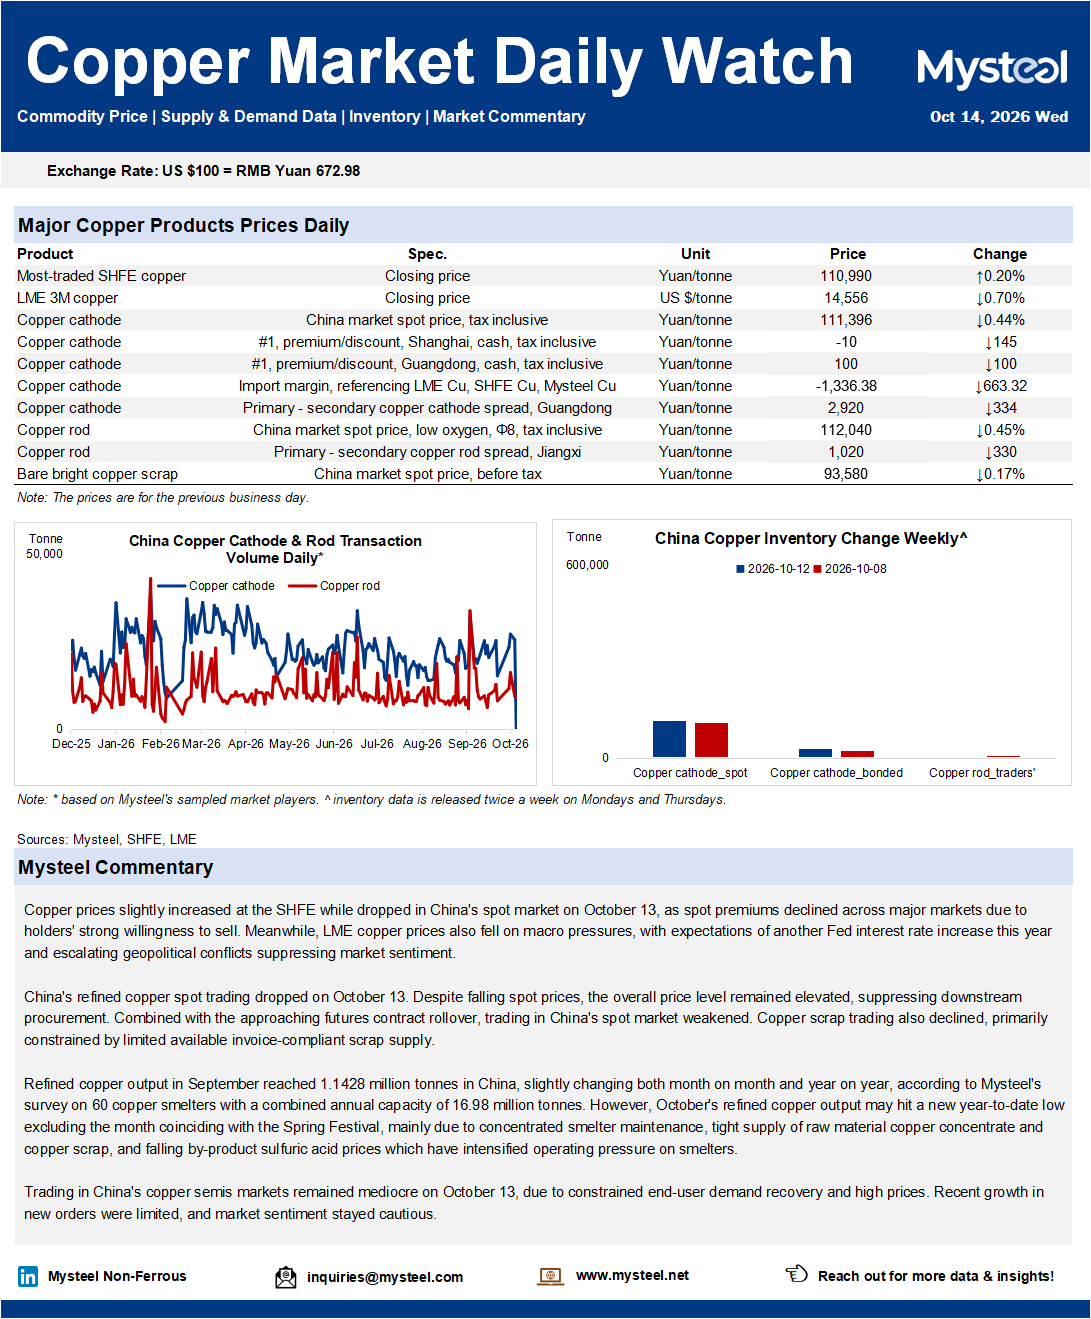
Copper prices slightly increased at the SHFE while dropped in China's spot market on October 13, as spot premiums declined across major markets due to holders' strong willingness to sell. Meanwhile, LME copper prices also fell on macro pressures, with expectations of another Fed interest rate increase this year and escalating geopolitical conflicts suppressing market sentiment.
China's refined copper spot trading dropped on October 13. Despite falling spot prices, the overall price level remained elevated, suppressing downstream procurement. Combined with the approaching futures contract rollover, trading in China's spot market weakened. Copper scrap trading also declined, primarily constrained by limited available invoice-compliant scrap supply.
Refined copper output in September reached 1.1428 million tonnes in China, slightly changing both month on month and year on year, according to Mysteel's survey on 60 copper smelters with a combined annual capacity of 16.98 million tonnes. However, October's refined copper output may hit a new year-to-date low excluding the month coinciding with the Spring Festival, mainly due to concentrated smelter maintenance, tight supply of raw material copper concentrate and copper scrap, and falling by-product sulfuric acid prices which have intensified operating pressure on smelters.
Trading in China's copper semis markets remained mediocre on October 13, due to constrained end-user demand recovery and high prices. Recent growth in new orders were limited, and market sentiment stayed cautious.