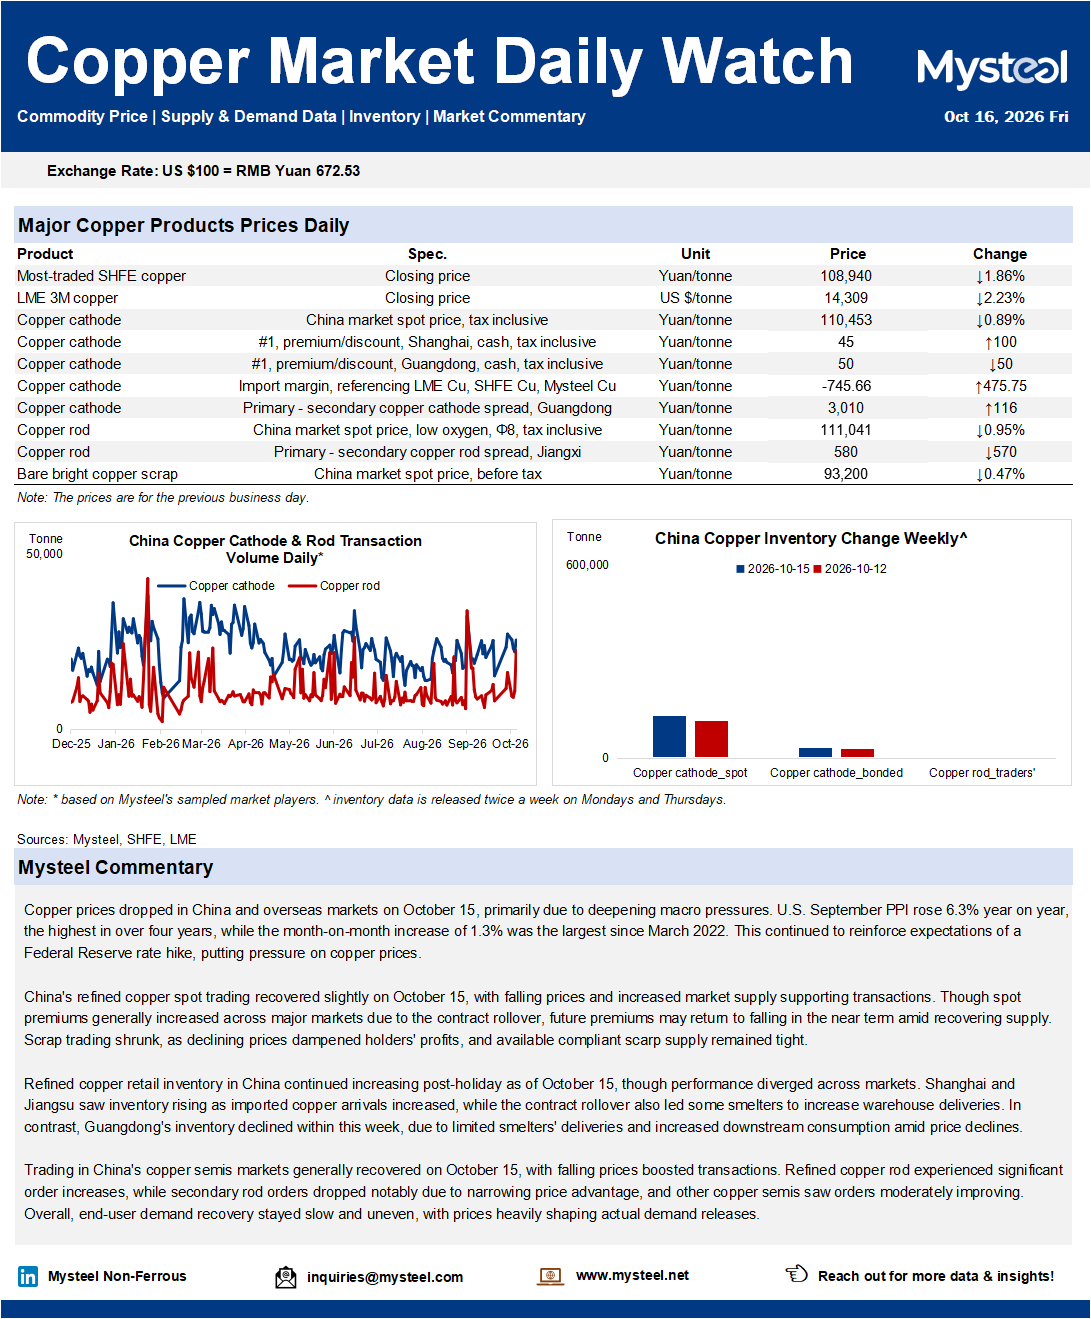
Copper prices dropped in China and overseas markets on October 15, primarily due to deepening macro pressures. U.S. September PPI rose 6.3% year on year, the highest in over four years, while the month-on-month increase of 1.3% was the largest since March 2022. This continued to reinforce expectations of a Federal Reserve rate hike, putting pressure on copper prices.
China's refined copper spot trading recovered slightly on October 15, with falling prices and increased market supply supporting transactions. Though spot premiums generally increased across major markets due to the contract rollover, future premiums may return to falling in the near term amid recovering supply. Scrap trading shrunk, as declining prices dampened holders' profits, and available compliant scarp supply remained tight.
Refined copper retail inventory in China continued increasing post-holiday as of October 15, though performance diverged across markets. Shanghai and Jiangsu saw inventory rising as imported copper arrivals increased, while the contract rollover also led some smelters to increase warehouse deliveries. In contrast, Guangdong's inventory declined within this week, due to limited smelters' deliveries and increased downstream consumption amid price declines.
Trading in China's copper semis markets generally recovered on October 15, with falling prices boosted transactions. Refined copper rod experienced significant order increases, while secondary rod orders dropped notably due to narrowing price advantage, and other copper semis saw orders moderately improving. Overall, end-user demand recovery stayed slow and uneven, with prices heavily shaping actual demand releases.
Join Mysteel's Q3 Review & Q4 Outlook Copper FREE Webinar to dig deep into the volatile market! Check the link below to learn more, and register NOW to secure your spots:
