Premium: Spot premiums rebound after contract rollover as regional supply stays tight
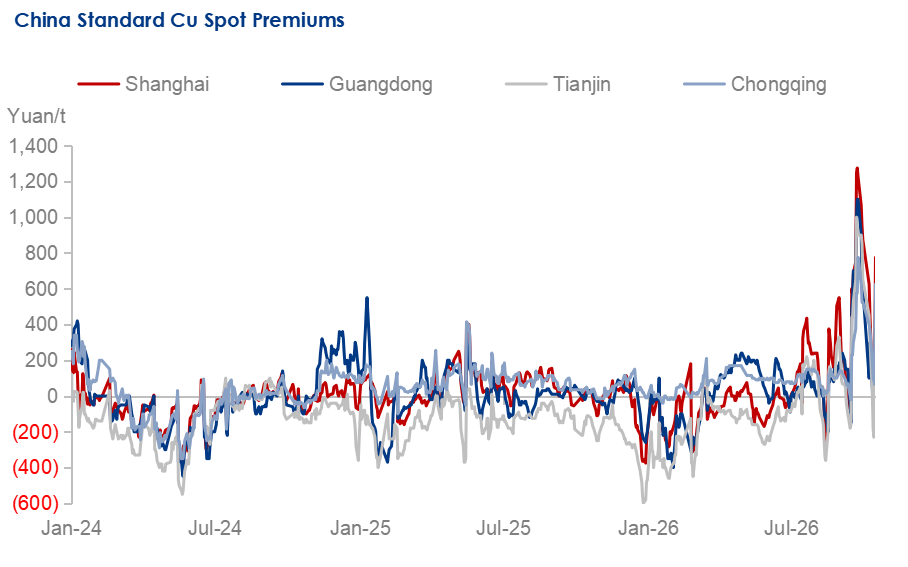
China's refined copper spot premiums generally dropped before rebounding last week. Ahead of the delivery and rollover of the SHFE 2610 contract, the near-month backwardation structure stayed wide, while a large volume of non-registered imported brands and additional smelter cargoes flowed into the market. Improved spot availability, combined with holders' growing willingness to cut prices, pushed Shanghai premiums down quickly, with the market slipping into discount in the first half of the week. Once the rollover was completed, however, quotations were re-based onto the 2611 contract. As copper prices fell, downstream buying interest recovered and holders turned more inclined to hold out for higher prices, sending spot premiums back to elevated levels. In Guangdong, where circulating supply remained tight and the backwardation structure held firm, premiums jumped to Yuan 530-830/tonne immediately after the rollover.
Data Source: Mysteel
Looking ahead, imported copper arrivals still have room to increase, but domestic smelter shipments are set to edge lower and the availability of domestic cargoes is likely to stay relatively limited. Combined with falling copper prices, downstream consumption is expected to have some room to improve. China's refined copper spot premiums are therefore expected to largely stabilize at high levels in the short term. According to Mysteel, refined copper spot premium ranges are forecast with Guangdong at Yuan 300-800/tonne, Tianjin at Yuan 300-700/tonne, and Chongqing at Yuan 400-800/tonne next week.
Supply: Supply diverges across markets
China's refined copper spot supply diverged by region last week. In Shanghai, sizeable volumes of imported copper arrived and some smelter cargoes also added to arrivals as contract delivery and rollover approached, improving the availability of circulating spot and extending the increase in retail inventory. In Guangdong, smelter shipments were limited and warehouse arrivals were modest, while downstream consumption recovered and outward movements increased, so inventories resumed a destocking trend from the post-holiday high, leaving tradable spot resources persistently tight. In North China, maintenance at major regional smelters continued and output was not yet back to normal, so arrivals were limited and holders' available inventories stayed generally low. In Chongqing, the pace of long-term contract pick-ups accelerated after the rollover, but overall arrivals were larger, leading Chongqing refined copper spot supply to improve slightly. Overall, refined copper spot supply in China improved last week.
Looking ahead, the improvement in China's refined copper spot supply is unlikely to be sustained. Although some imported copper is still expected to flow into certain markets, supply from domestic smelters is expected to decline due to maintenance and raw material issues. Meanwhile, consumption may rise slightly as copper prices fall. As a result, China's refined copper spot supply is expected to gradually tighten in the short term.
Demand: Wide backwardation curbs restocking
Demand remained cautious overall last week. With the 2610 contract delivery and rollover underway and the near-month backwardation running at a high level, downstream procurement willingness was constrained and most buyers stuck to essential purchases and small-scale low-price restocking. After the rollover, copper prices fell and market consumption improved to some extent. In Guangdong, buyers were deterred by elevated prices early in the week and bought only as needed. A slight price correction on Tuesday brought a mild recovery in dip-buying interest, but once prices stabilized and delivery approached, a wait-and-see mood dominated and trading stayed thin. In Tianjin, the spot average price ran around Yuan 111,000/tonne with the price center falling within the week. Transactions picked up slightly after the price decline, but the improvement was limited. In Chongqing, the wide futures backwardation in the first half of the week kept downstream interest in spot transactions extremely low, with buyers mostly drawing on long-term contracts. After the rollover, the pace of long-term contract pick-ups accelerated visibly and a few essential spot deals were concluded, warming the trading atmosphere somewhat.
According to Mysteel's survey of 56 Chinese refined copper trading enterprises (including smelters, traders and downstream processors), China's refined copper spot average daily trading volume was 24,900 tonnes over October 12-16, down by 400 tonnes, or 1.69%, from the daily average of 25,300 tonnes for October 8-9.
Going forward, consumption in China's refined copper market is expected to have some room for improvement as holiday effects fade and macroeconomic factors weigh on copper prices.
Import: China refined copper import arbitrage fluctuates sharply last week
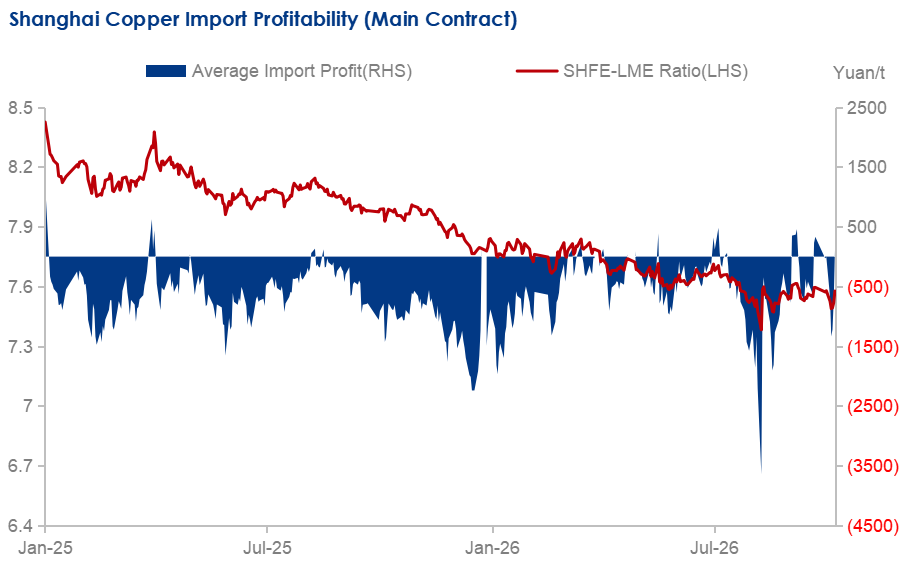
During October 12-16, as copper prices fluctuated at home and abroad, China's refined copper import arbitrage ratio deteriorated rapidly, with import profit turning from positive to negative. Combined with large fluctuations in the LME backwardation structure, market sentiment became increasingly cautious. However, as copper prices later fell, the import arbitrage ratio recovered and spot trading activity picked up. Therefore, although arrivals of imported cargo at Shanghai Yangshan Port increased, Yangshan refined copper warrant and bill of lading premiums remained high amid recovering import trade and firm seller pricing. Looking ahead, China's refined copper import arbitrage ratio is expected to remain decent in the near term, with import volumes likely stable.
Data Source: Mysteel
Inventory: China's refined copper retail and bonded inventory rise WoW
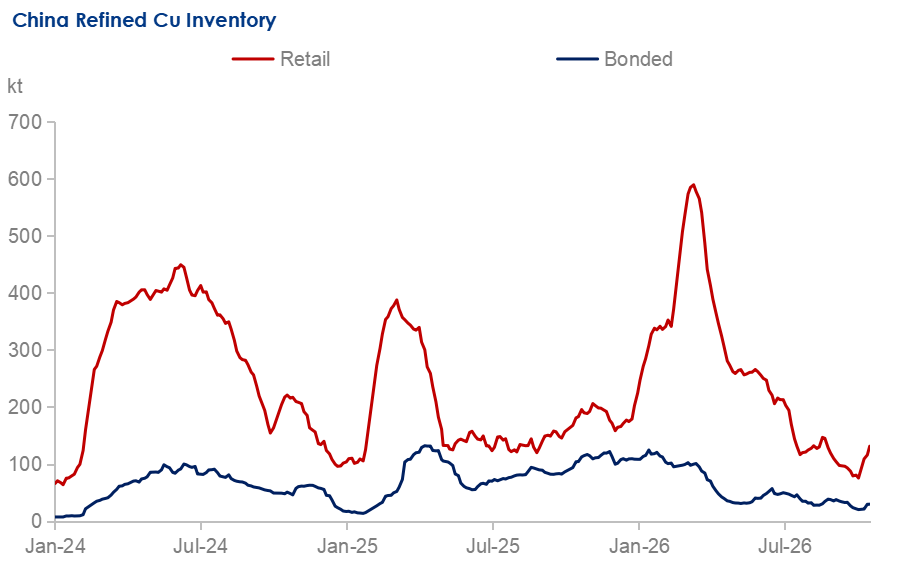
China's refined copper retail inventory rose last week. In Shanghai, inventory continued to build after the holiday. Imported copper arrivals into the market were relatively heavy during the week, and with the delivery contract rollover approaching, some smelter cargoes kept arriving. Meanwhile, downstream consumption remained modest and warehouse outflows were limited, so inventory accumulated. In Guangdong, by contrast, inventory declined through the week, as smelter shipments fell again and warehouse inflows stayed light, while recovering downstream consumption lifted outflows, returning the market to destocking. Looking ahead to this week, although imported copper arrivals still have room to increase, smelter cargoes are expected to arrive in smaller volumes, and lower copper prices are likely to support downstream purchasing demand. Therefore, the pace of buildup in China's refined copper retail inventory is expected to slow, or the inventory may even return to declining.
China's refined copper bonded inventory also edged up, mainly because domestic smelters' cargoes planned for export gradually moved into bonded zones during the week, while cargoes arriving at port were progressively warehoused. Looking ahead, although smelters have relatively few cargoes planned for export, port arrivals are still scheduled to enter warehouses. Therefore, China's refined copper bonded inventory is also expected to build up in the short term.
The COMEX-LME refined copper price spread stayed low, averaging $113.68/tonne over October 12-16, decreasing by $83.42/tonne week on week. As the COMEX-LME copper price spread narrowed, LME inventories declined, while COMEX inventories increased. Looking ahead, the U.S. refined copper tariff ruling is a key factor shaping global refined copper inventory trends from Q4 2026 to H1 2027. If implemented as scheduled, COMEX inventories will remain high, while LME inventories are expected to stay in a tight balance due to tight non-U.S. spot supply. If the ruling is further delayed or weakened, COMEX inventory backflow and an LME inventory rebound may occur simultaneously.
Data Source: Mysteel
More regular analysis and comprehensive data on China's copper industry are available in Mysteel Copper Weekly, Mysteel Copper Monthly, and Mysteel Copper Database. Reach out to us via Mysteel's official website: Latest & Reliable Copper Market Price in China | Mysteel, and follow Mysteel Non-Ferrous for more insights!
Don't miss Mysteel's Q3 2026 Copper Market FREE Webinar! Check the link below to learn more, and register to secure your spots:
Written by Zhaorui Cui, cuizhaorui@mysteel.com
Edited by Mingyuan Wang, wangmingyuan@mysteel.com