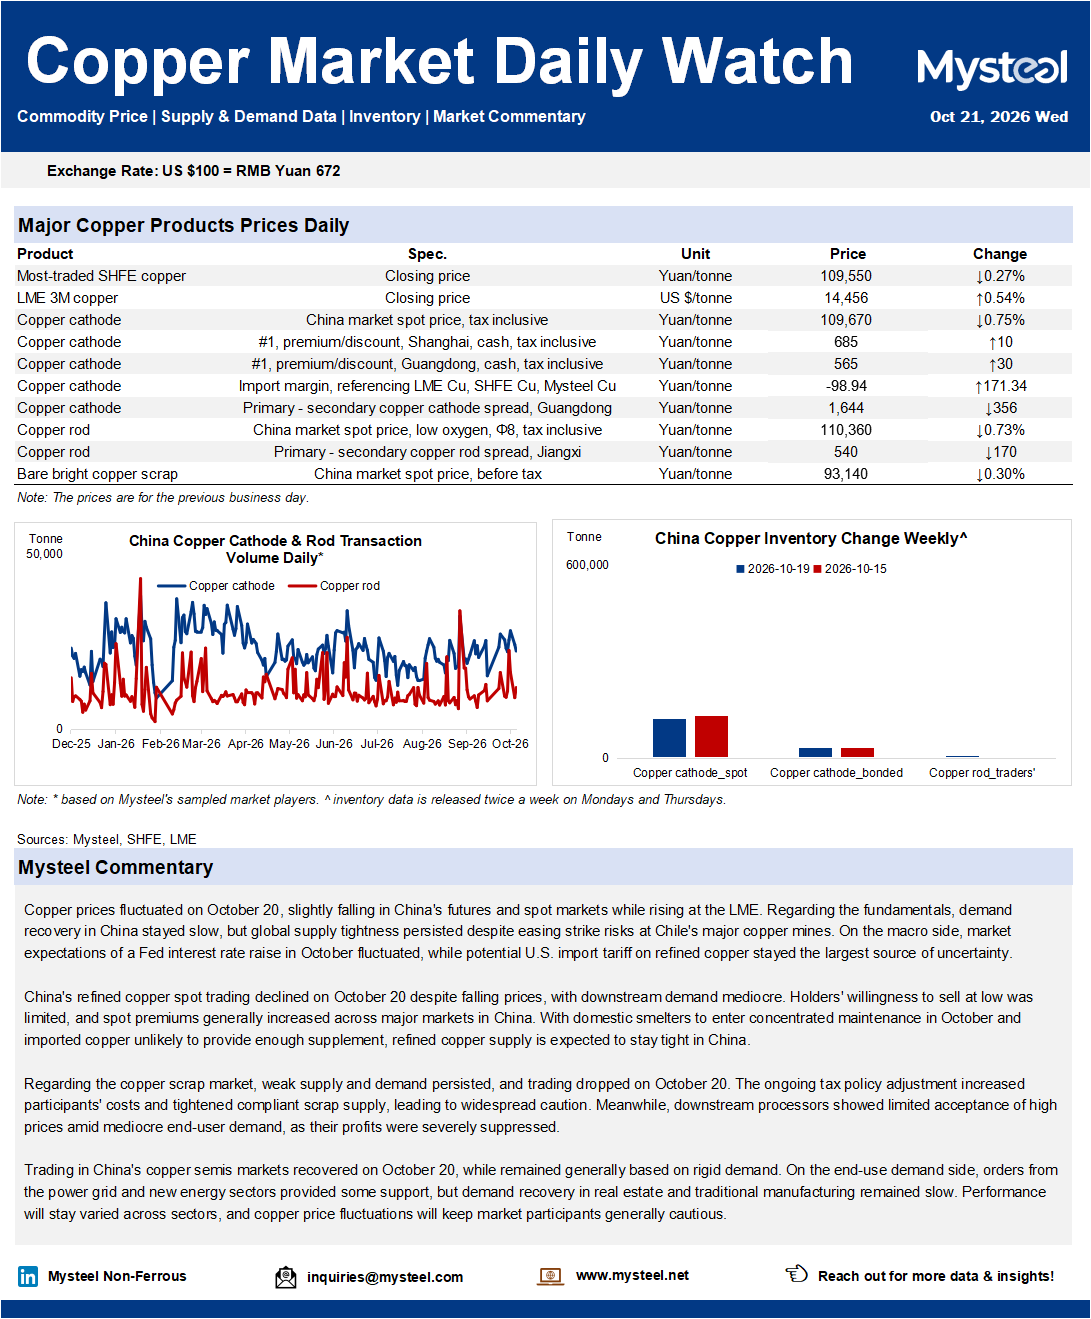
Copper prices fluctuated on October 20, slightly falling in China's futures and spot markets while rising at the LME. Regarding the fundamentals, demand recovery in China stayed slow, but global supply tightness persisted despite easing strike risks at Chile's major copper mines. On the macro side, market expectations of a Fed interest rate raise in October fluctuated, while potential U.S. import tariff on refined copper stayed the largest source of uncertainty.
China's refined copper spot trading declined on October 20 despite falling prices, with downstream demand mediocre. Holders' willingness to sell at low was limited, and spot premiums generally increased across major markets in China. With domestic smelters to enter concentrated maintenance in October and imported copper unlikely to provide enough supplement, refined copper supply is expected to stay tight in China.
Regarding the copper scrap market, weak supply and demand persisted, and trading dropped on October 20. The ongoing tax policy adjustment increased participants' costs and tightened compliant scrap supply, leading to widespread caution. Meanwhile, downstream processors showed limited acceptance of high prices amid mediocre end-user demand, as their profits were severely suppressed.
Trading in China's copper semis markets recovered on October 20, while remained generally based on rigid demand. On the end-use demand side, orders from the power grid and new energy sectors provided some support, but demand recovery in real estate and traditional manufacturing remained slow. Performance will stay varied across sectors, and copper price fluctuations will keep market participants generally cautious.
Join Mysteel's Q3 Review & Q4 Outlook Copper FREE Webinar to dig deep into the volatile market! Check the link below to learn more, and register NOW to secure your spots: