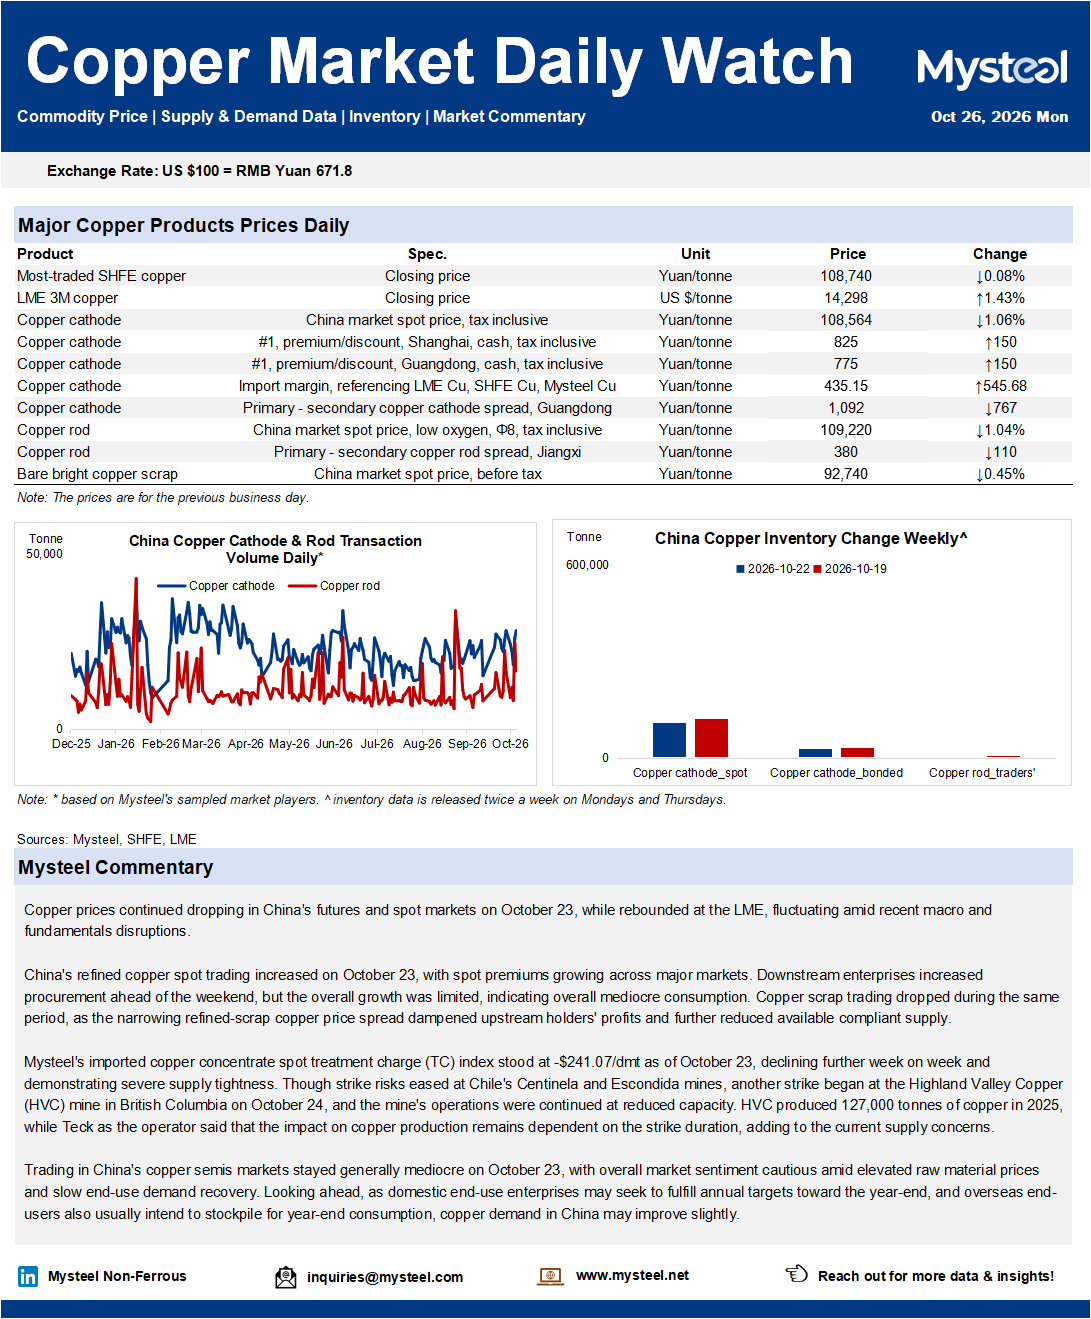
Copper prices continued dropping in China's futures and spot markets on October 23, while rebounded at the LME, fluctuating amid recent macro and fundamentals disruptions.
China's refined copper spot trading increased on October 23, with spot premiums increasing across major markets. Downstream enterprises increased procurement ahead of the weekend, but the overall growth was limited, indicating mediocre consumption. Copper scrap trading dropped during the same period, as the narrowing refined-scrap copper price spread dampened upstream holders' profits and further shrinking available compliant supply.
Mysteel's imported copper concentrate spot treatment charge (TC) index stood at -$241.07/dmt as of October 23, declining further week on week and demonstrating severe supply tightness. Though strike risks eased at Chile's Centinela and Escondida mines, another strike began at the Highland Valley Copper (HVC) mine in British Columbia on October 24, and the mine's operations were continued at reduced capacity. HVC produced 127,000 tonnes of copper in 2025, while Teck as the operator said that the impact on copper production remains dependent on the strike duration, adding to the current supply concerns.
Trading in China's copper semis markets stayed generally mediocre on October 23, with overall market sentiment cautious amid elevated raw material prices and slow end-use demand recovery. Looking ahead, as domestic end-use enterprises seek to fulfill annual targets toward the year-end, while overseas end-users also need to stockpile for year-end consumption, copper demand in China may improve. Close attention should be paid to the actual release of consumption.
Join Mysteel's Q3 Review & Q4 Outlook Copper FREE Webinar to dig deep into the volatile market! Check the link below to learn more, and register NOW to secure your spots: