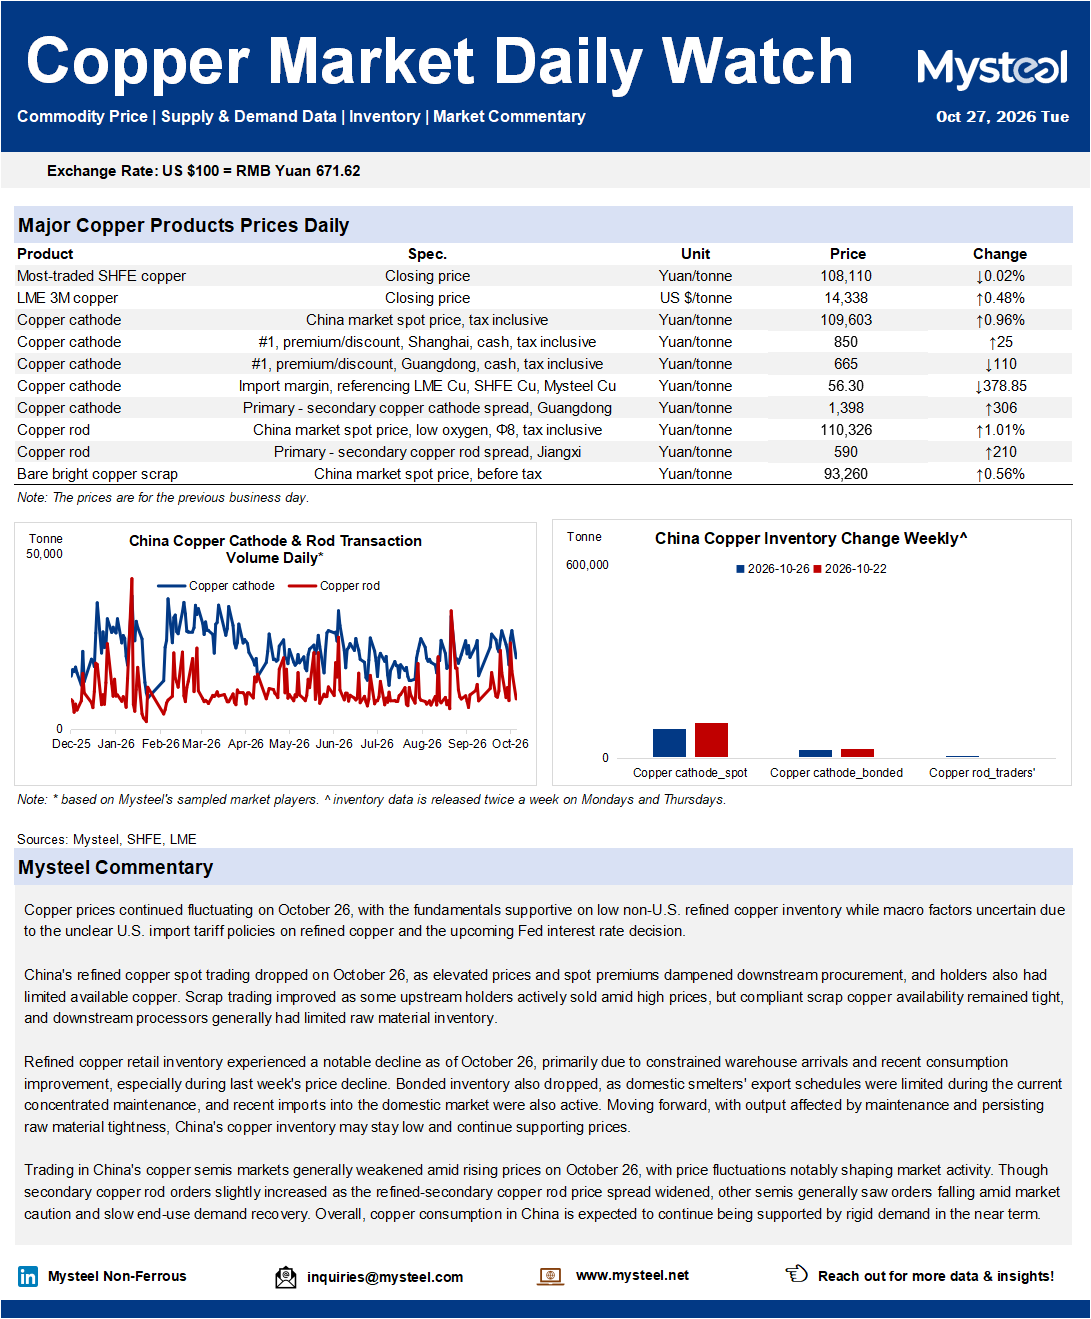
Copper prices continued fluctuating on October 26, with the fundamentals supportive on low non-U.S. refined copper inventory while macro factors uncertain due to the unclear U.S. import tariff on refined copper and the upcoming Fed interest rate decision.
China's refined copper spot trading dropped on October 26, as elevated prices and spot premiums dampened downstream procurement, and holders also had limited available copper. Scrap trading improved as some upstream holders actively sold amid high prices, but compliant scrap copper availability remained tight, and downstream processors generally had limited raw material inventory.
Refined copper retail inventory experienced a notable decline as of October 26, primarily due to constrained warehouse arrivals and recent consumption improvement, especially during last week's price decline. Bonded inventory also dropped, as domestic smelters' export schedules were limited during the current concentrated maintenance, and recent imports into the domestic market were also active. Moving forward, with output affected by maintenance and persisting raw material tightness, China's copper inventory may stay low and continue supporting prices.
Trading in China's copper semis markets generally weakened along with rising prices on October 26, with price fluctuations notably shaping market activity. Though secondary copper rod orders slightly increased as the refined-scrap copper price spread widened, other semis generally saw transactions falling amid market caution and slow end-use demand recovery. Overall, copper consumption in China is expected to continue being supported by rigid demand in the near term.
Join Mysteel's Q3 Review & Q4 Outlook Copper FREE Webinar to dig deep into the volatile market! Check the link below to learn more, and register NOW to secure your spots: