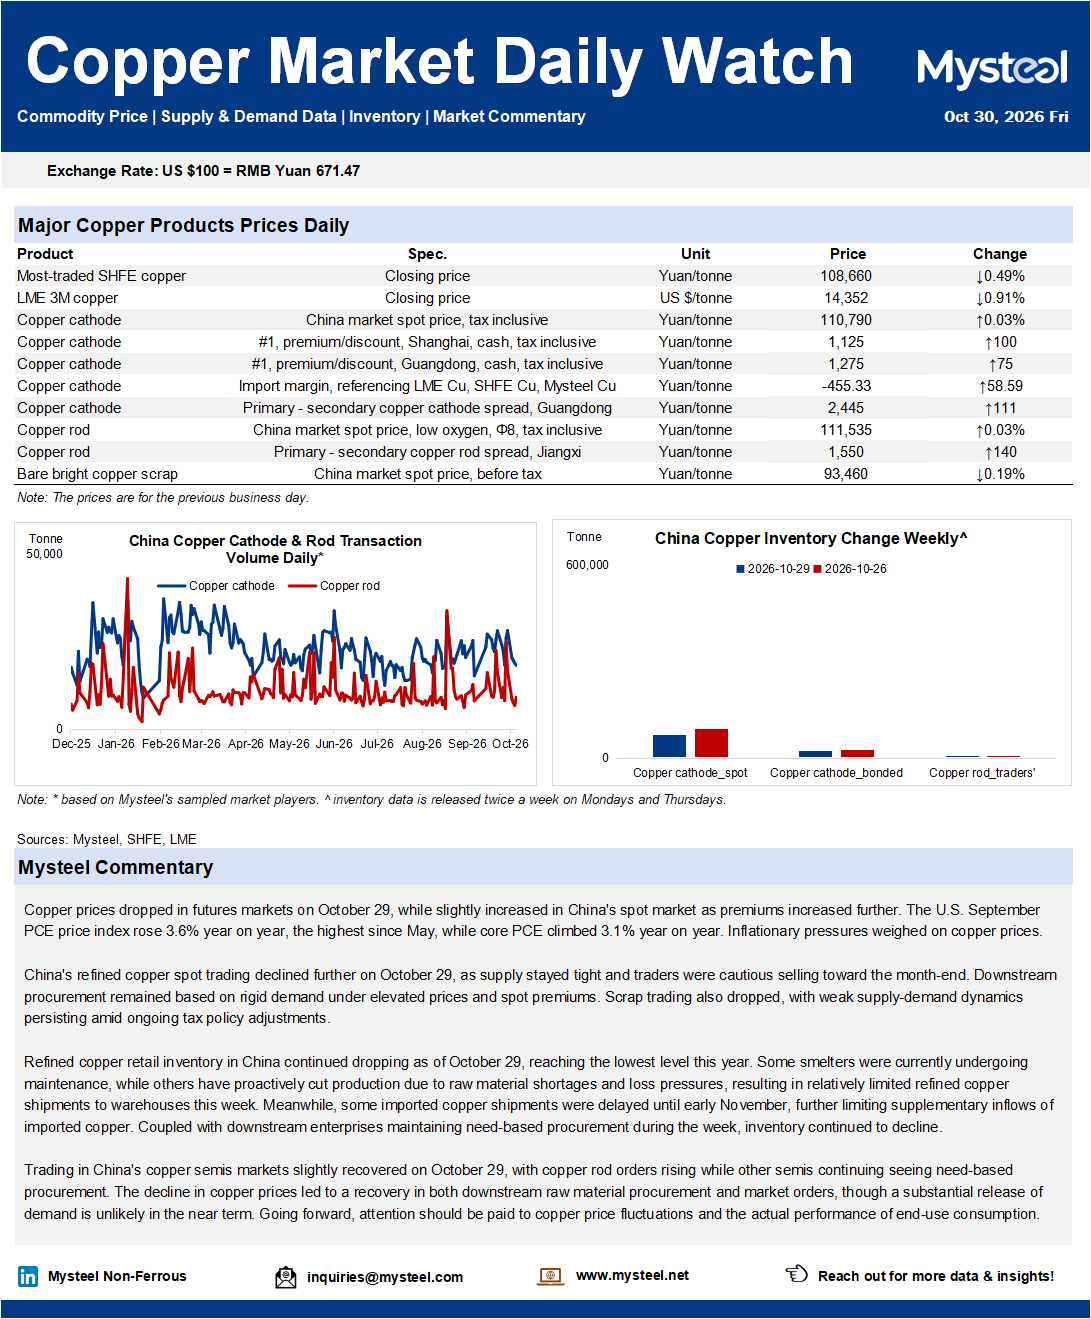
Copper prices dropped in futures markets on October 29, while slightly increased in China's spot market as premiums increased further. On the macro side, the U.S. September PCE price index rose 3.6% year on year, the highest since May, while core PCE climbed 3.1% year-on-year. Inflationary pressures weighed on copper prices.
China's refined copper spot trading declined further on October 29, as supply stayed tight and traders were cautious selling toward the month-end. Downstream procurement remained based on rigid demand under elevated prices and spot premiums. Scrap trading also dropped, with weak supply-demand dynamics persisting amid ongoing tax policy adjustments.
Refined copper retail inventory in China continued dropping as of October 29, reaching the lowest level this year. Some smelters were currently undergoing maintenance, while others have proactively cut production due to raw material shortages and loss pressures, resulting in relatively limited refined copper shipments to warehouses this week. Meanwhile, some imported copper shipments were delayed until early November, further limiting supplementary inflows of imported copper. Coupled with downstream enterprises maintaining need-based procurement during the week, inventories continued to decline.
Trading in China's copper semis markets slightly recovered on October 29, with copper rod orders rising while other semis continuing seeing need-based procurement. The decline in copper prices led to a recovery in both downstream raw material procurement and market orders, though a substantial release of demand is unlikely in the near term. Going forward, attention should be paid to copper price fluctuations and the actual performance of end-use demand.
LAST CALL! Join Mysteel's Q3 Review & Q4 Outlook Copper FREE Webinar to dig deep into the volatile market! Check the link below to learn more, and register NOW to secure your spots: