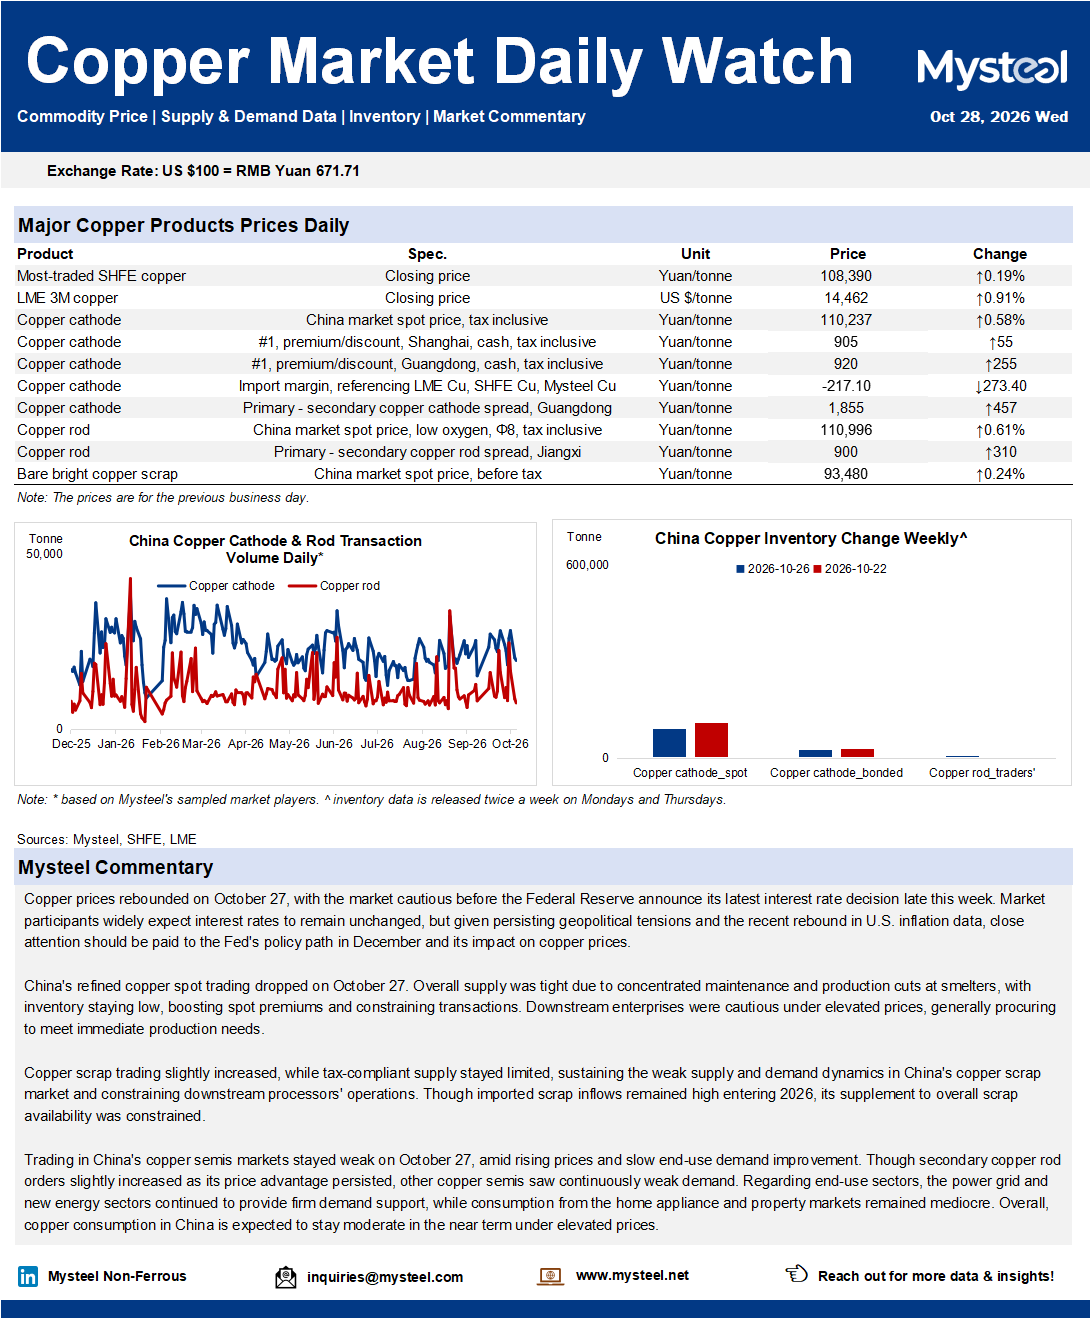
Copper prices rebounded on October 27, with the market cautious before the Federal Reserve announce its latest interest rate decision late this week. Market participants widely expect interest rates to remain unchanged, but given persisting geopolitical tensions and the recent rebound in U.S. inflation data, close attention should be paid to the Fed's policy path in December and its impact on copper prices.
China's refined copper spot trading dropped on October 27. Overall supply was tight due to concentrated maintenance and production cuts at smelters, with inventory staying low, boosting spot premiums and constraining transactions. Downstream enterprises were cautious under elevated prices, generally procuring to meet immediate production needs.
Copper scrap trading slightly increased, while tax-compliant supply stayed limited, sustaining the weak supply and demand dynamics in China's copper scrap market and constraining downstream processors' operations. Though imported scrap inflows remained high entering 2026, its supplement to overall scrap availability was constrained.
Trading in China's copper semis markets stayed weak on October 27, amid rising prices and slow end-use demand improvement. Though secondary copper rod orders slightly increased as its price advantage persisted, other copper semis saw continuously sluggish demand. Regarding end-use sectors, the power grid and new energy sectors continued to provide firm demand support, while consumption from the home appliance and property markets remained mediocre, indicating persistent divergence. Overall, copper consumption in China is expected to stay moderate in the near term under elevated prices.
Join Mysteel's Q3 Review & Q4 Outlook Copper FREE Webinar to dig deep into the volatile market! Check the link below to learn more, and register NOW to secure your spots: