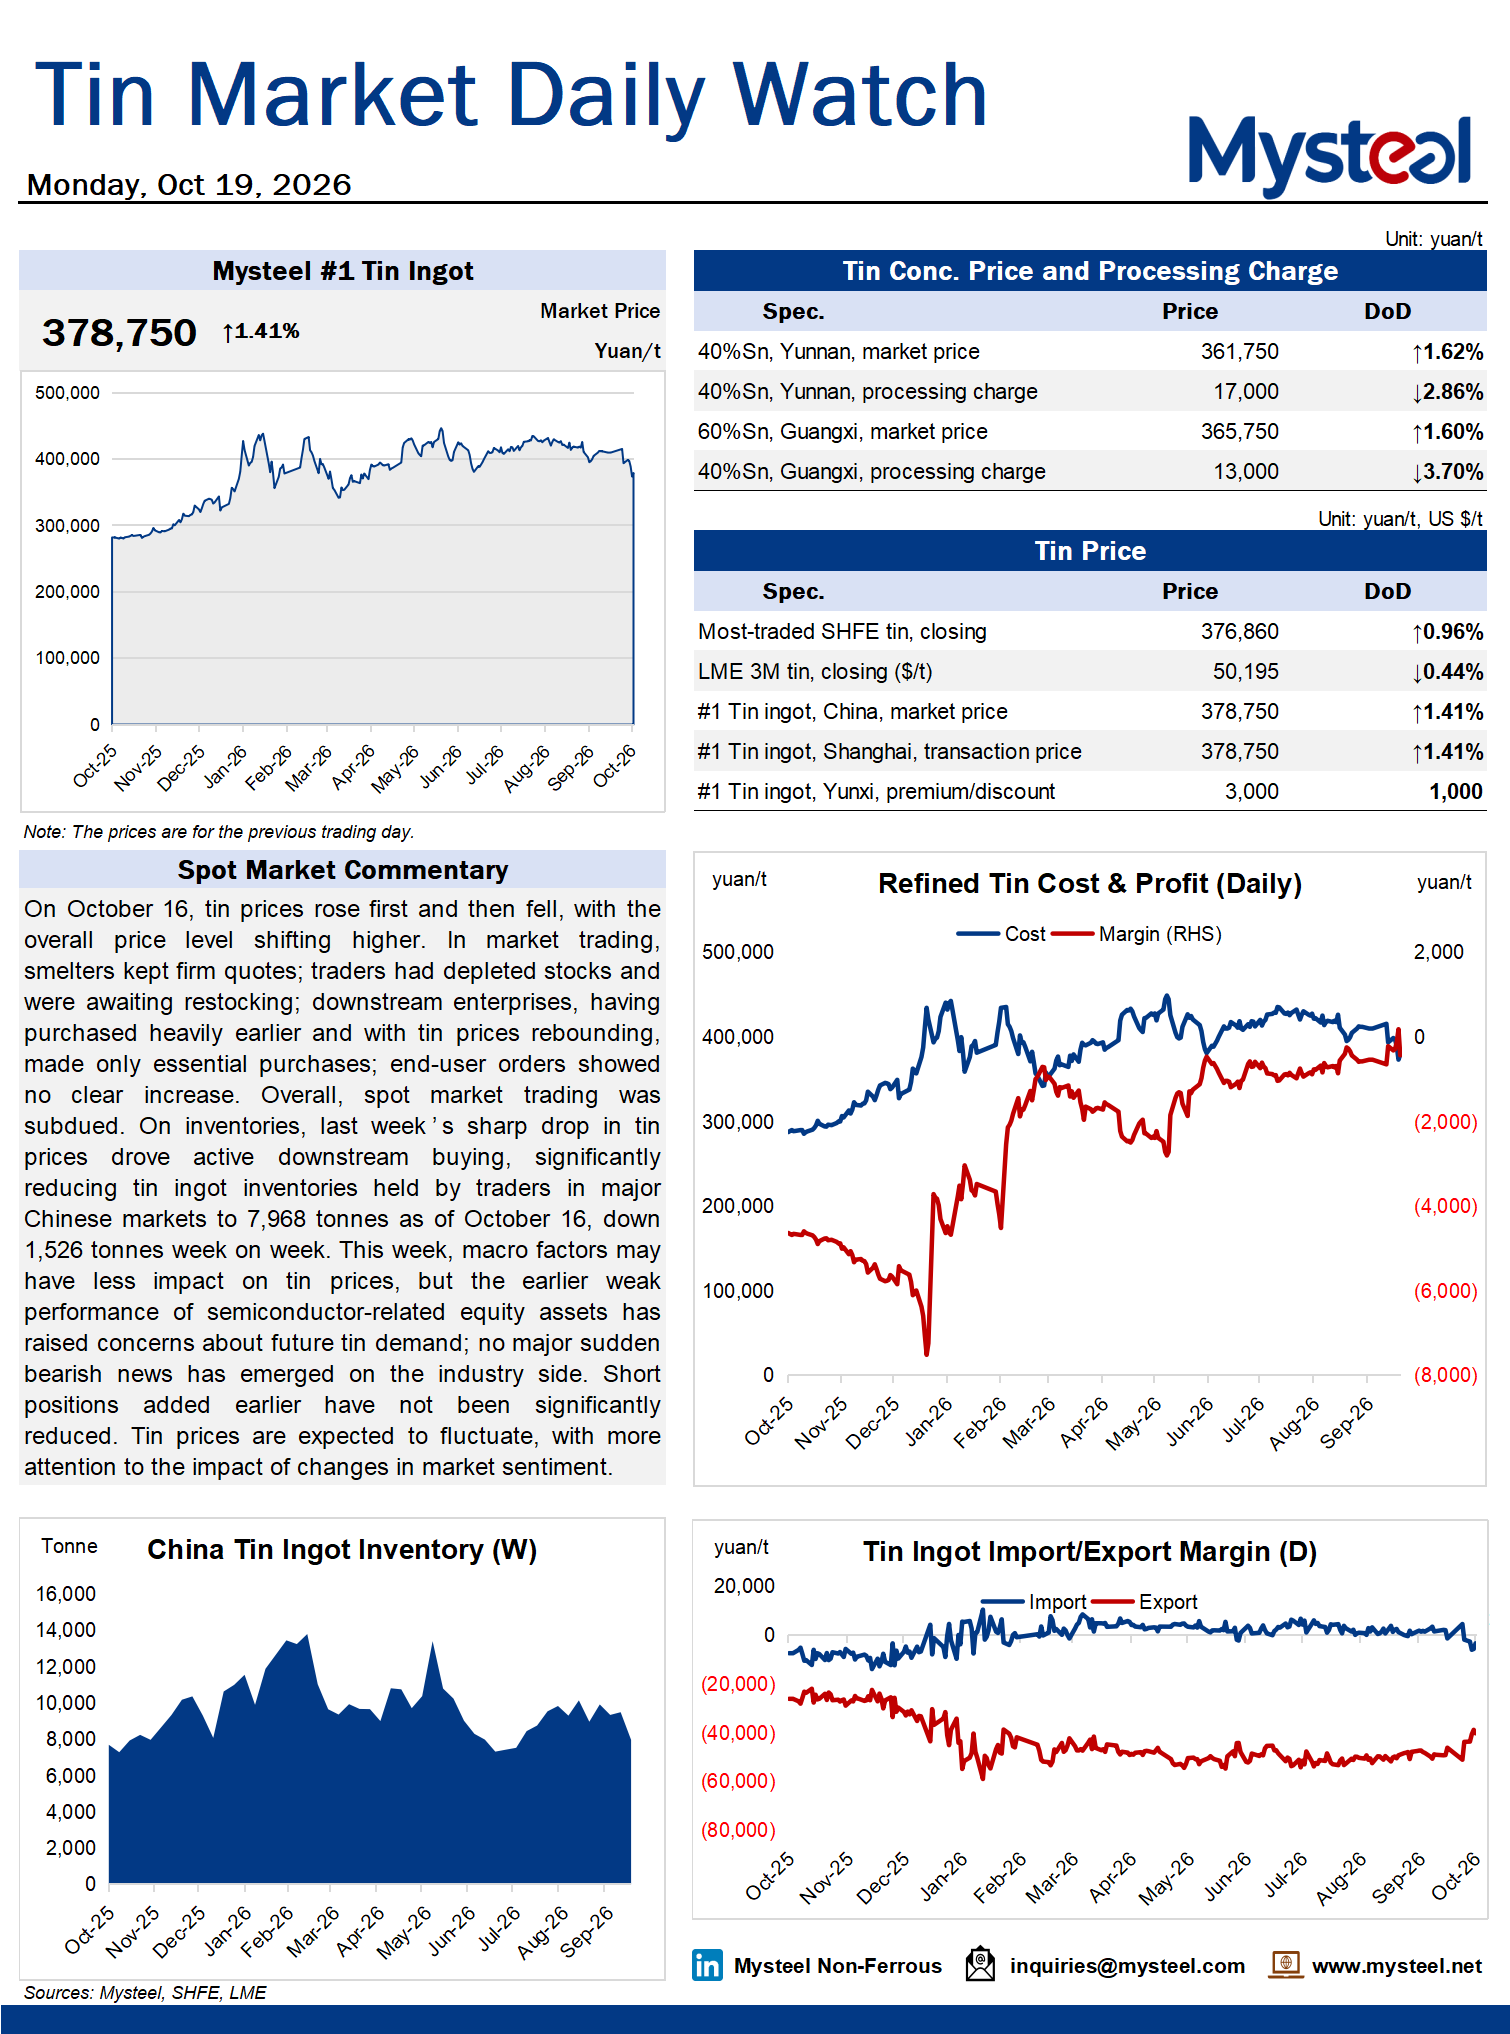
On October 16, tin prices rose first and then fell, with the overall price level shifting higher. In market trading, smelters kept firm quotes; traders had depleted stocks and were awaiting restocking; downstream enterprises, having purchased heavily earlier and with tin prices rebounding, made only essential purchases; end-user orders showed no clear increase. Overall, spot market trading was subdued. On inventories, last week's sharp drop in tin prices drove active downstream buying, significantly reducing tin ingot inventories held by traders in major Chinese markets to 7,968 tonnes as of October 16, down 1,526 tonnes week on week. This week, macro factors may have less impact on tin prices, but the earlier weak performance of semiconductor-related equity assets has raised concerns about future tin demand; no major sudden bearish news has emerged on the industry side. Short positions added earlier have not been significantly reduced. Tin prices are expected to fluctuate, with more attention to the impact of changes in market sentiment.