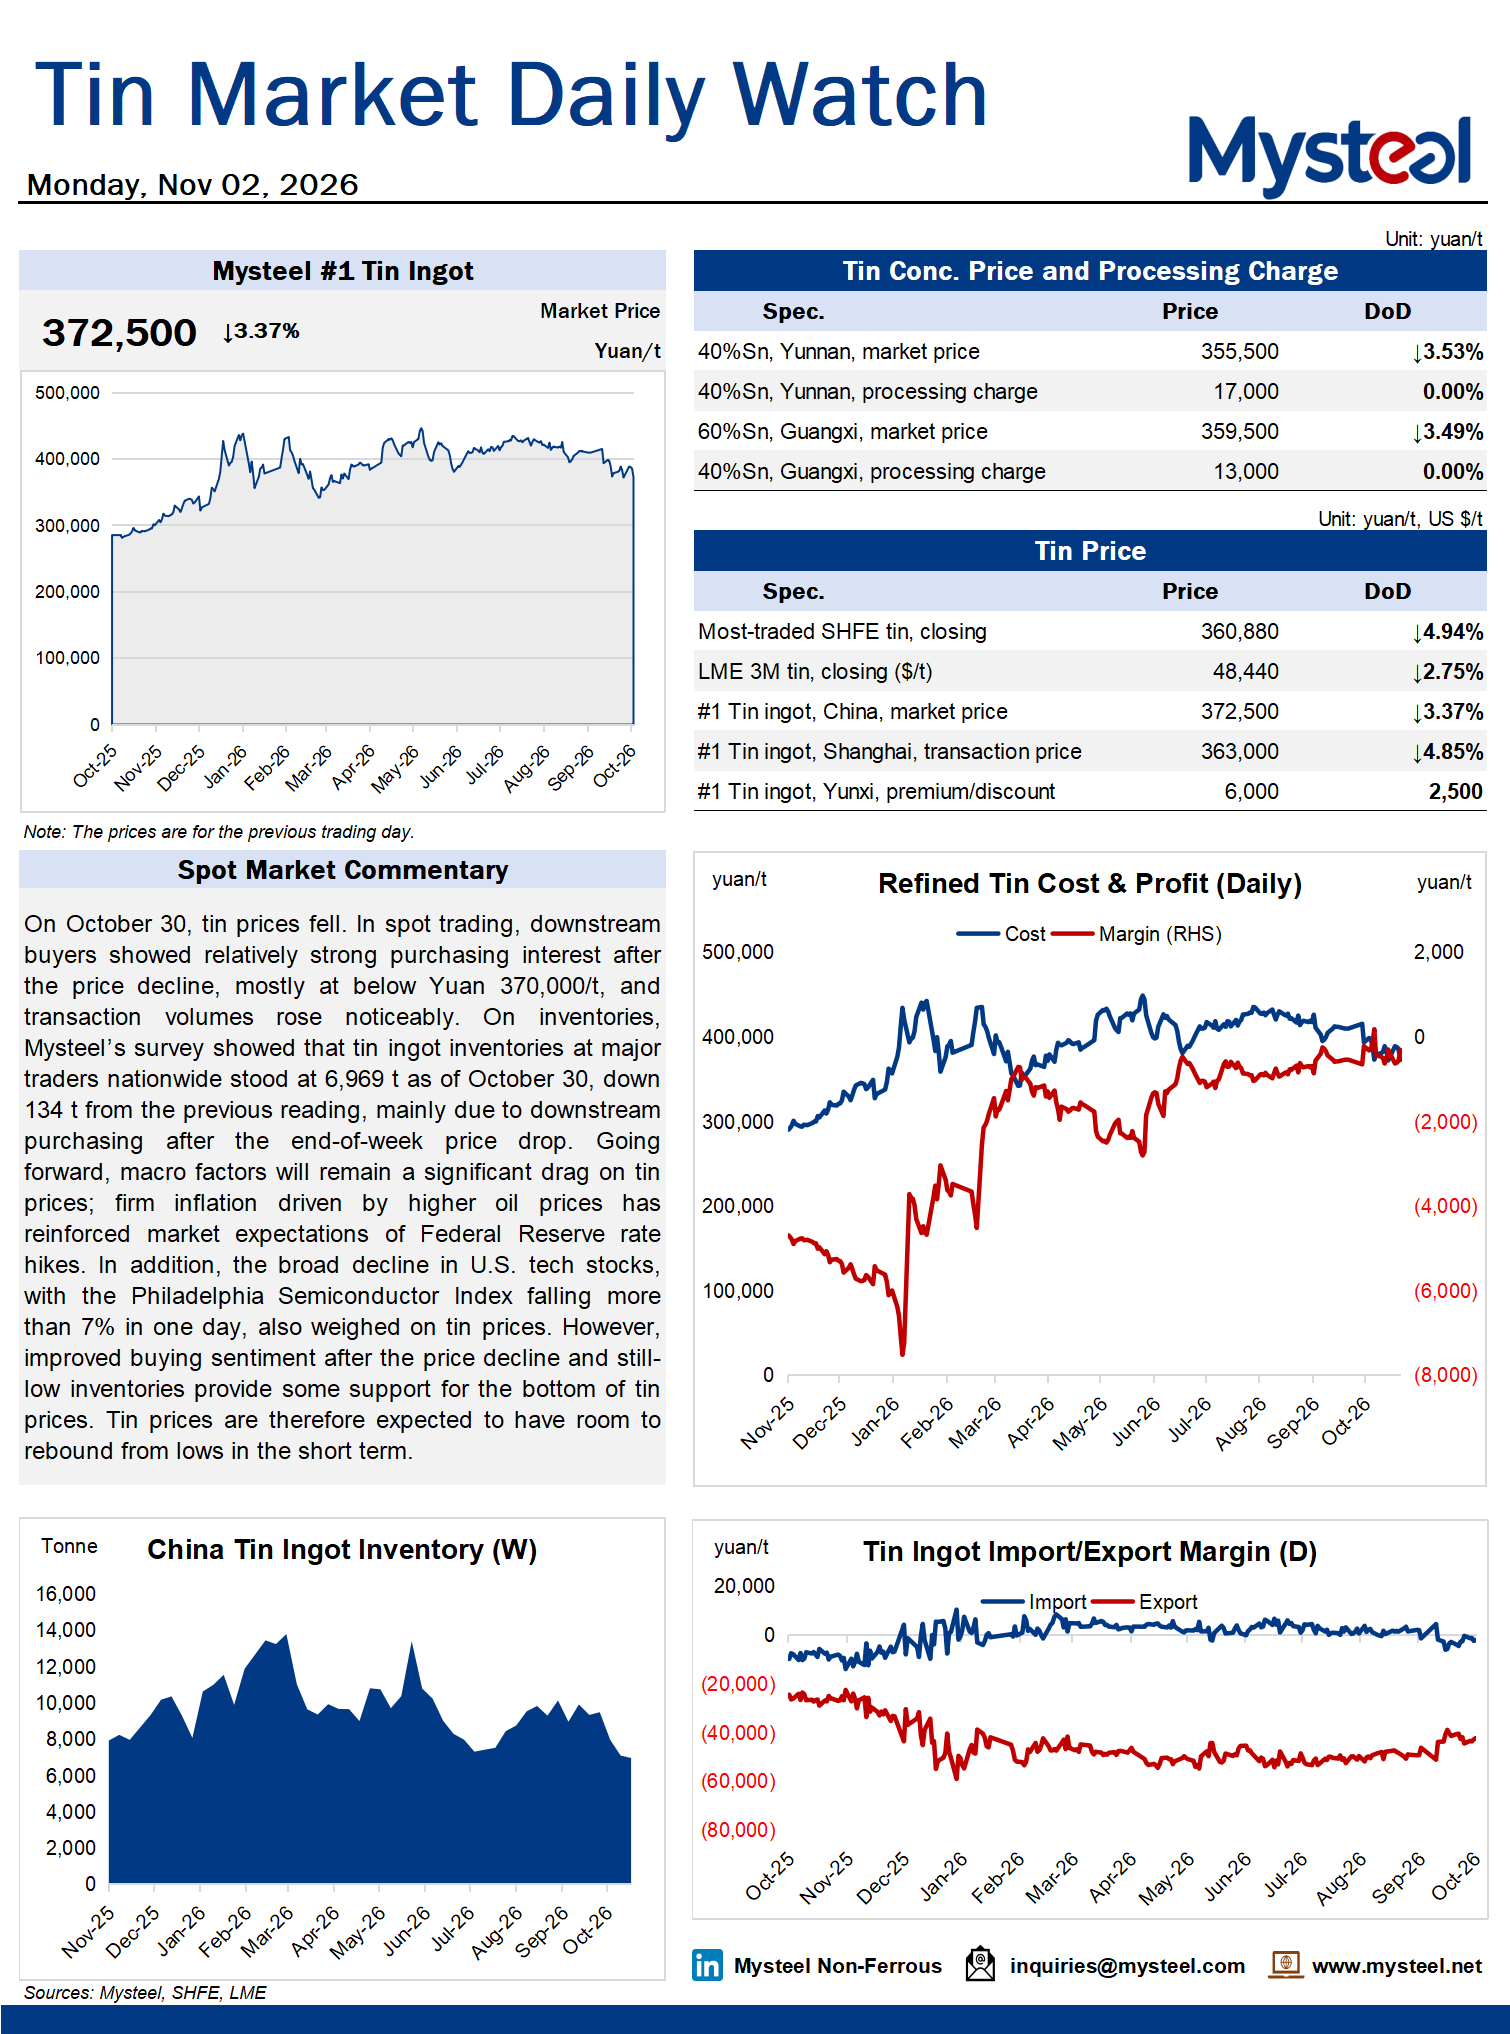
On October 30, tin prices fell. In spot trading, downstream buyers showed relatively strong purchasing interest after the price decline, mostly at below Yuan 370,000/t, and transaction volumes rose noticeably. On inventories, Mysteel's survey showed that tin ingot inventories at major traders nationwide stood at 6,969 t as of October 30, down 134 t from the previous reading, mainly due to downstream purchasing after the end-of-week price drop. Going forward, macro factors will remain a significant drag on tin prices; firm inflation driven by higher oil prices has reinforced market expectations of Federal Reserve rate hikes. In addition, the broad decline in U.S. tech stocks, with the Philadelphia Semiconductor Index falling more than 7% in one day, also weighed on tin prices. However, improved buying sentiment after the price decline and still-low inventories provide some support for the bottom of tin prices. Tin prices are therefore expected to have room to rebound from lows in the short term.