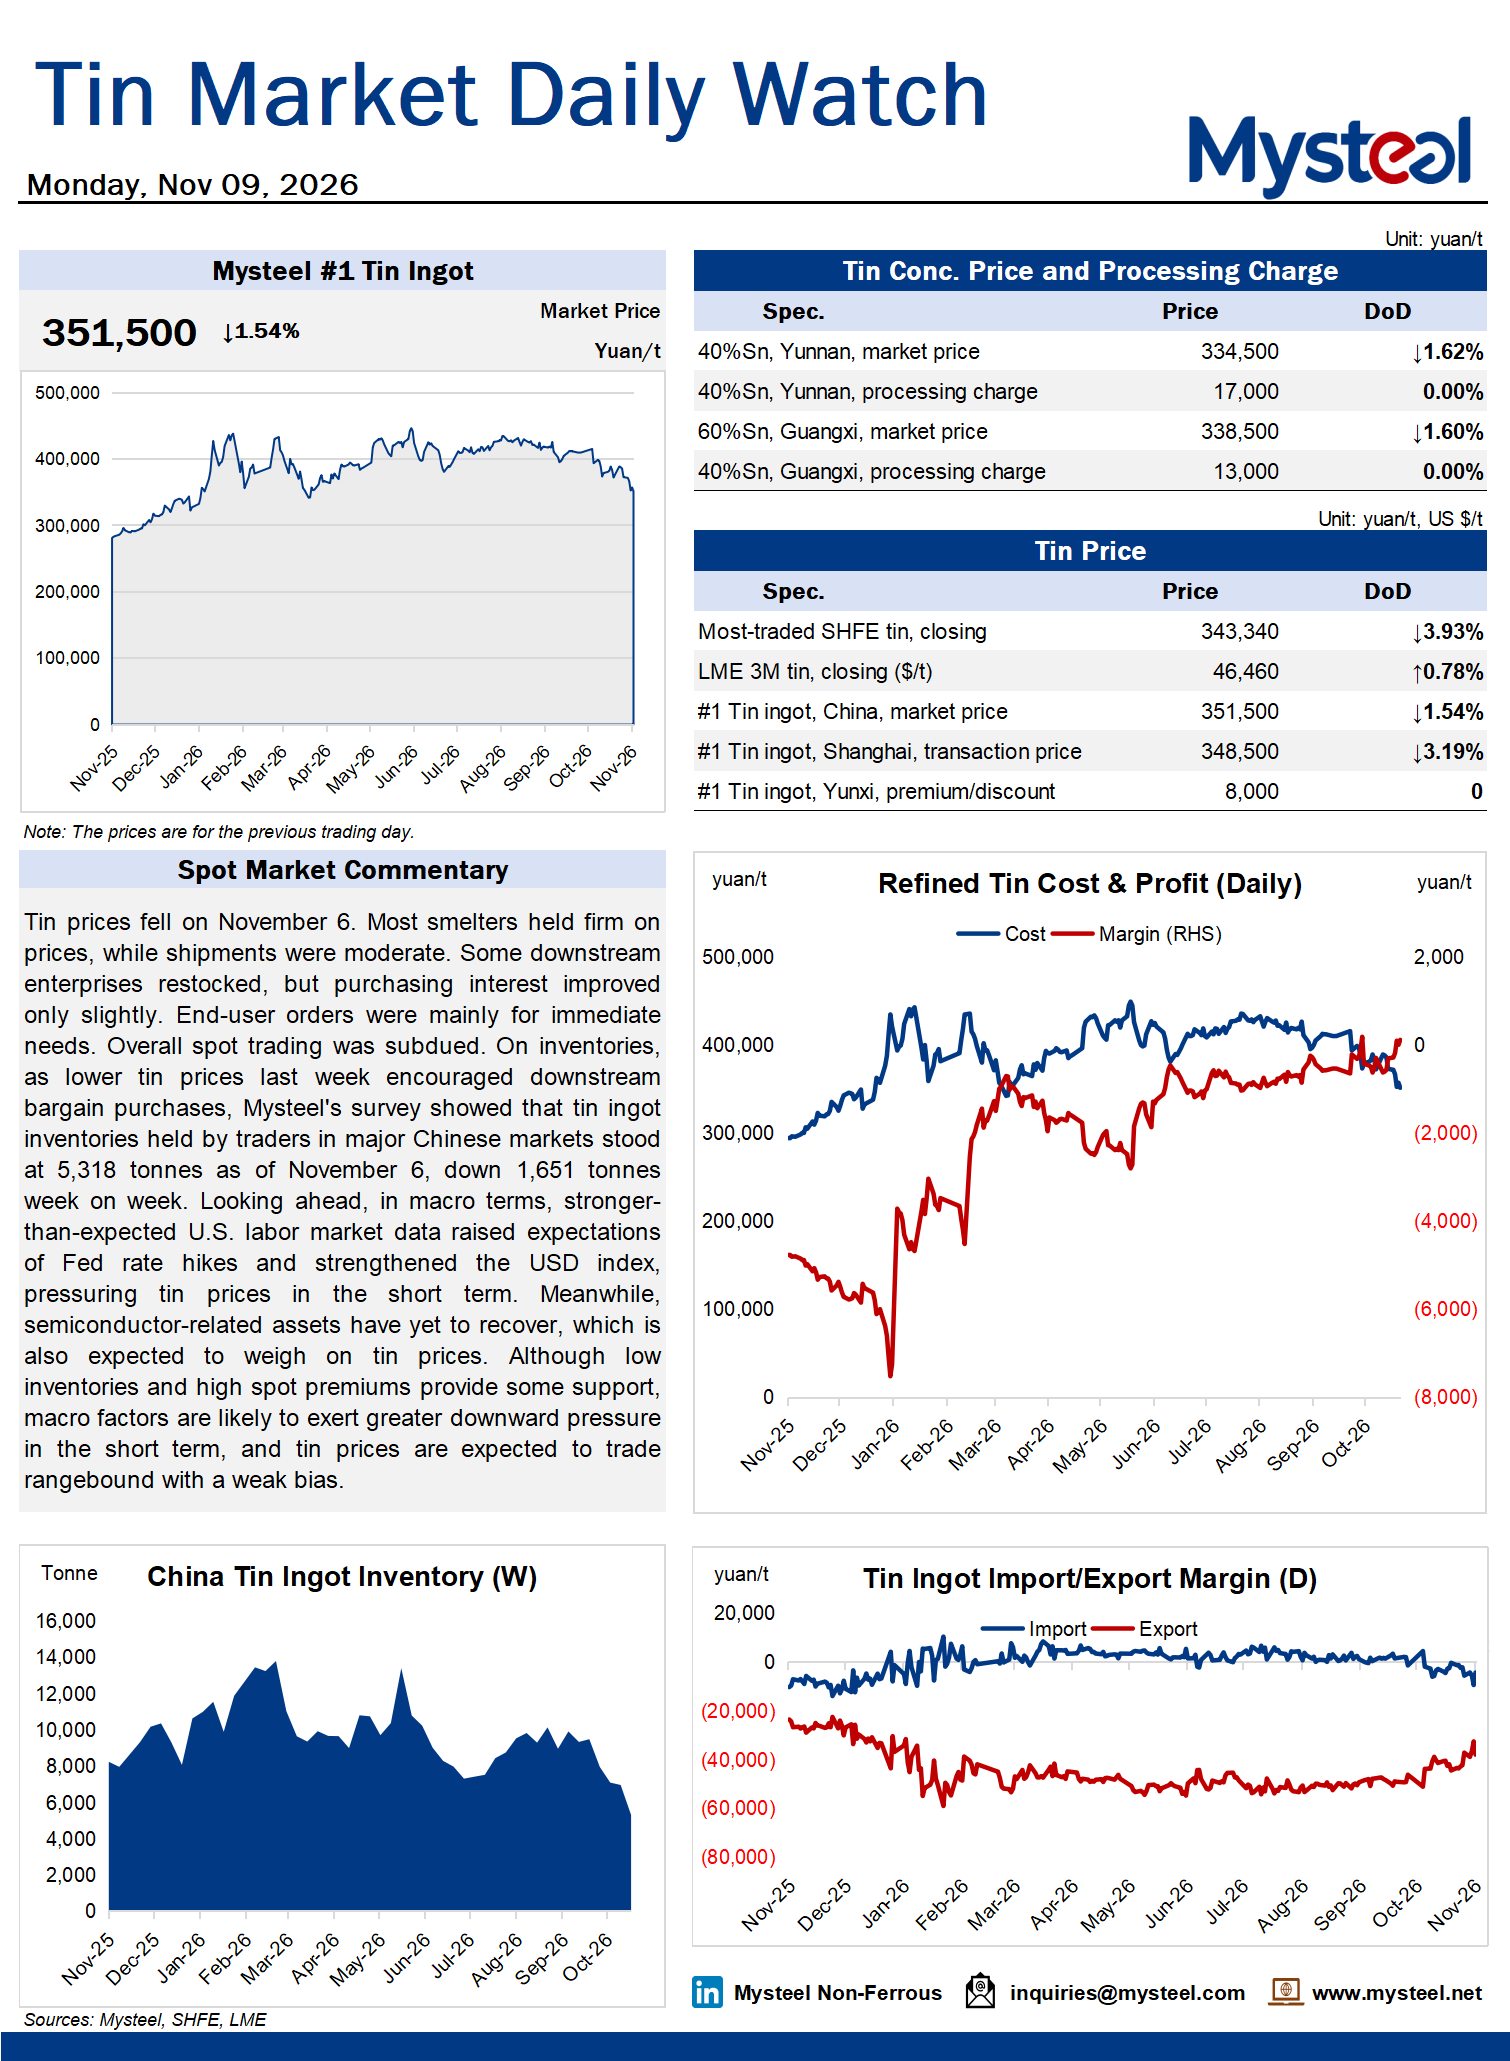
Tin prices fell on November 6. Most smelters held firm on prices, while shipments were moderate. Some downstream enterprises restocked, but purchasing interest improved only slightly. End-user orders were mainly for immediate needs. Overall spot trading was subdued. On inventories, as lower tin prices last week encouraged downstream bargain purchases, Mysteel's survey showed that tin ingot inventories held by traders in major Chinese markets stood at 5,318 tonnes as of November 6, down 1,651 tonnes week on week. Looking ahead, in macro terms, stronger-than-expected U.S. labor market data raised expectations of Fed rate hikes and strengthened the USD index, pressuring tin prices in the short term. Meanwhile, semiconductor-related assets have yet to recover, which is also expected to weigh on tin prices. Although low inventories and high spot premiums provide some support, macro factors are likely to exert greater downward pressure in the short term, and tin prices are expected to trade rangebound with a weak bias.