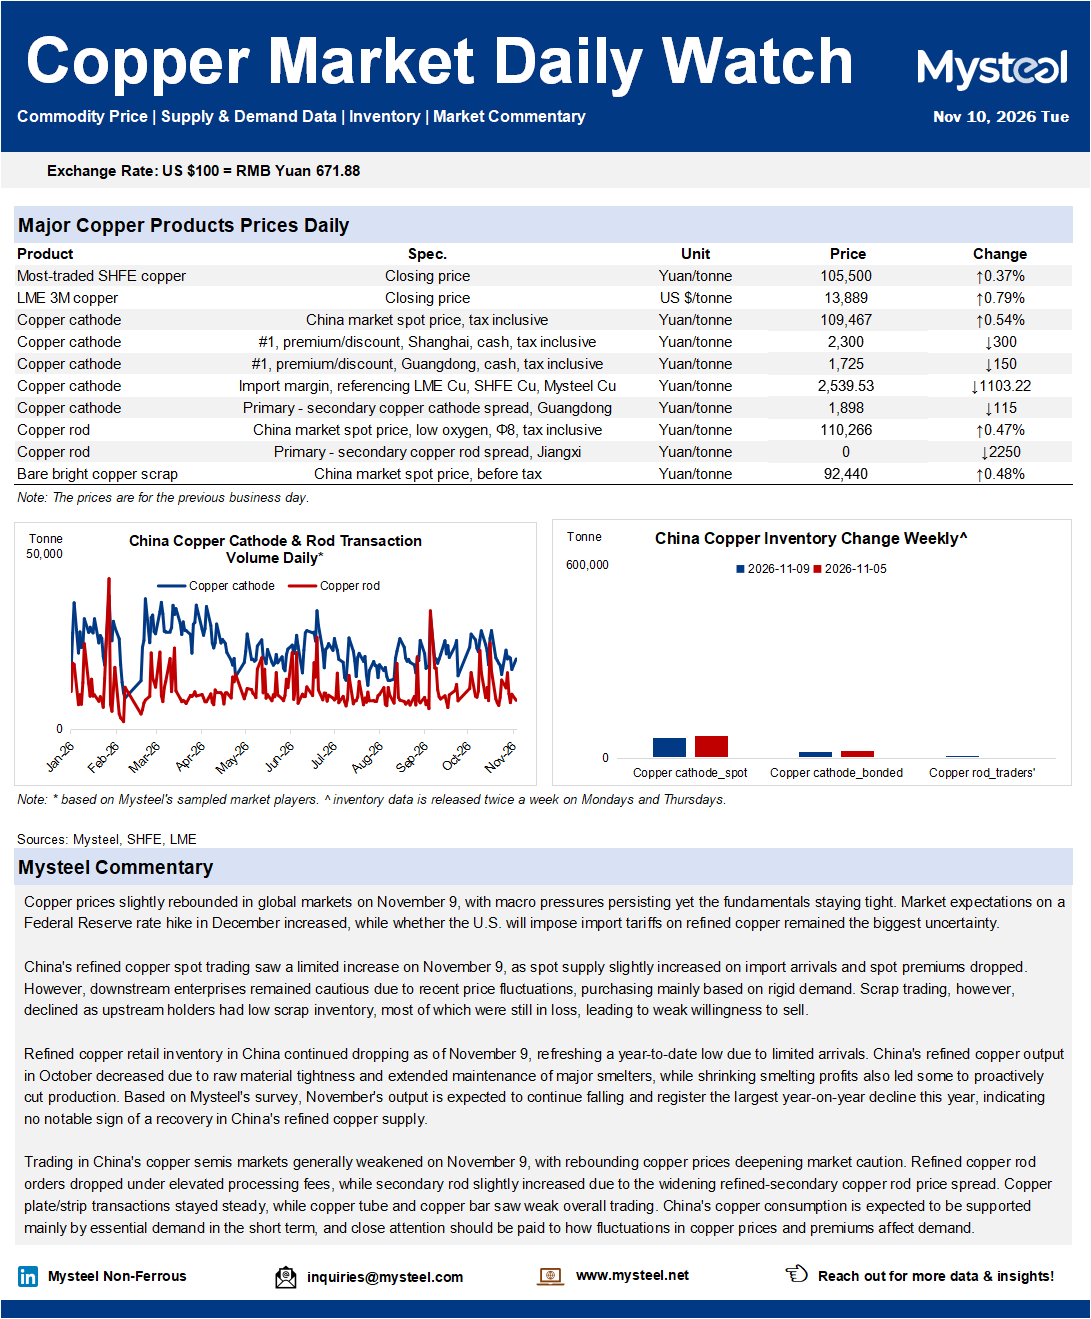
Copper prices slightly rebounded in global markets on November 9, with macro pressures persisting yet the fundamentals staying tight. Market expectations on a Federal Reserve rate hike in December increased, while whether the U.S. will impose import tariffs on refined copper remained the biggest uncertainty.
China's refined copper spot trading saw a limited increase on November 9, as spot supply slightly grew and spot premiums dropped. However, downstream enterprises remained cautious due to recent price fluctuations, purchasing mainly based on rigid demand. Scrap trading, however, declined as upstream holders had low scrap inventory, most of which were still in loss, leading to weak willingness to sell.
Refined copper retail inventory in China continued dropping as of November 9, refreshing a year-to-date low due to limited arrivals. China's refined copper output in October decreased due to raw material tightness and extended maintenance of major smelters, while shrinking smelting profits also led some to proactively cut production. Based on Mysteel's survey, November's output is expected to continue falling and register the largest year-on-year decline this year, indicating no notable sign of a recovery in China's refined copper supply.
Trading in China's copper semis markets generally weakened on November 9, with rebounding copper prices deepening market caution. Refined copper rod orders dropped under elevated processing fees, while secondary rod slightly increased due to the widening refined-secondary copper rod price spread. Copper plate/strip transactions stayed steady, while copper tube and copper bar saw weak overall trading. China's copper consumption is expected to be supported mainly by essential demand in the short term, and close attention should be paid to how fluctuations in copper prices and premiums affect demand.