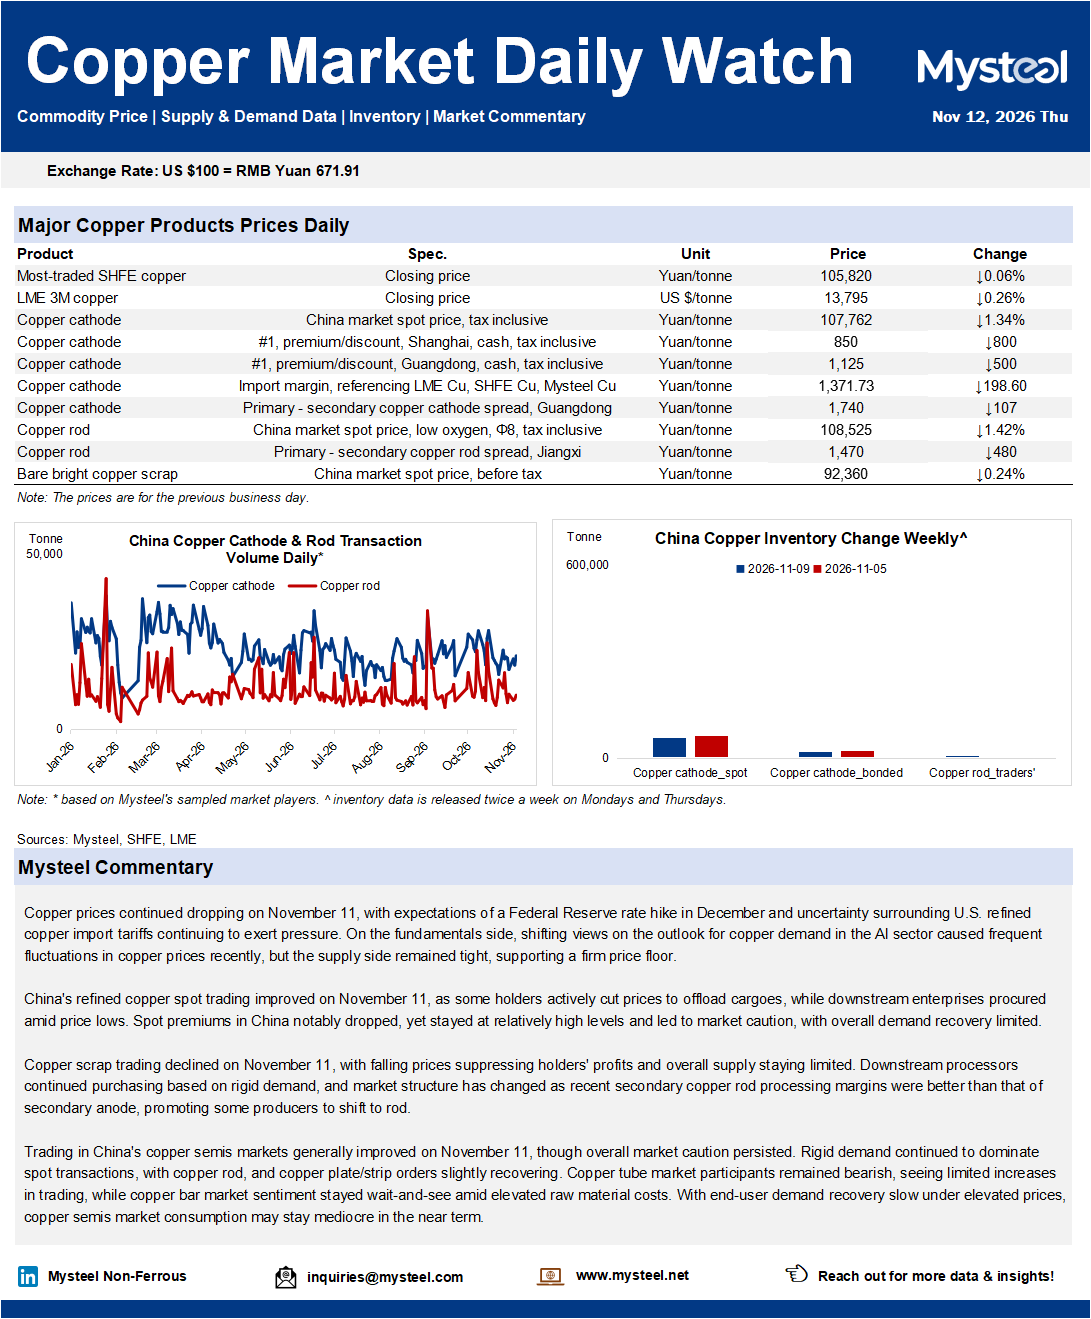
Copper prices continued dropping on November 11, with expectations of a Federal Reserve rate hike in December and uncertainty surrounding U.S. refined copper import tariffs continuing to exert pressure. On the fundamentals side, shifting views on the outlook for copper demand in the AI sector caused frequent fluctuations in copper prices recently, but the supply side remained tight, supporting a firm price floor.
China's refined copper spot trading improved on November 11, as some holders actively cut prices to offload cargoes, while downstream enterprises procured amid price lows. Spot premiums in China notably dropped, yet stayed at relatively high levels and led to market caution, with overall demand recovery limited.
Copper scrap trading declined on November 11, with falling prices suppressing holders' profits and overall supply staying limited. Downstream processors continued purchasing based on rigid demand, and market structure has changed as recent secondary copper rod processing margins were better than that of secondary anode, promoting some producers to shift to rod.
Trading in China's copper semis markets generally improved on November 11, though overall market caution persisted. Rigid demand continued to dominate spot transactions, with copper rod, and copper plate/strip orders slightly recovering. Copper tube market participants remained bearish, seeing limited increases in trading, while copper bar market sentiment stayed wait-and-see amid elevated raw material costs. With end-user demand recovery slow under elevated prices, copper semis market consumption may stay mediocre in the near term.